Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Income/expenses




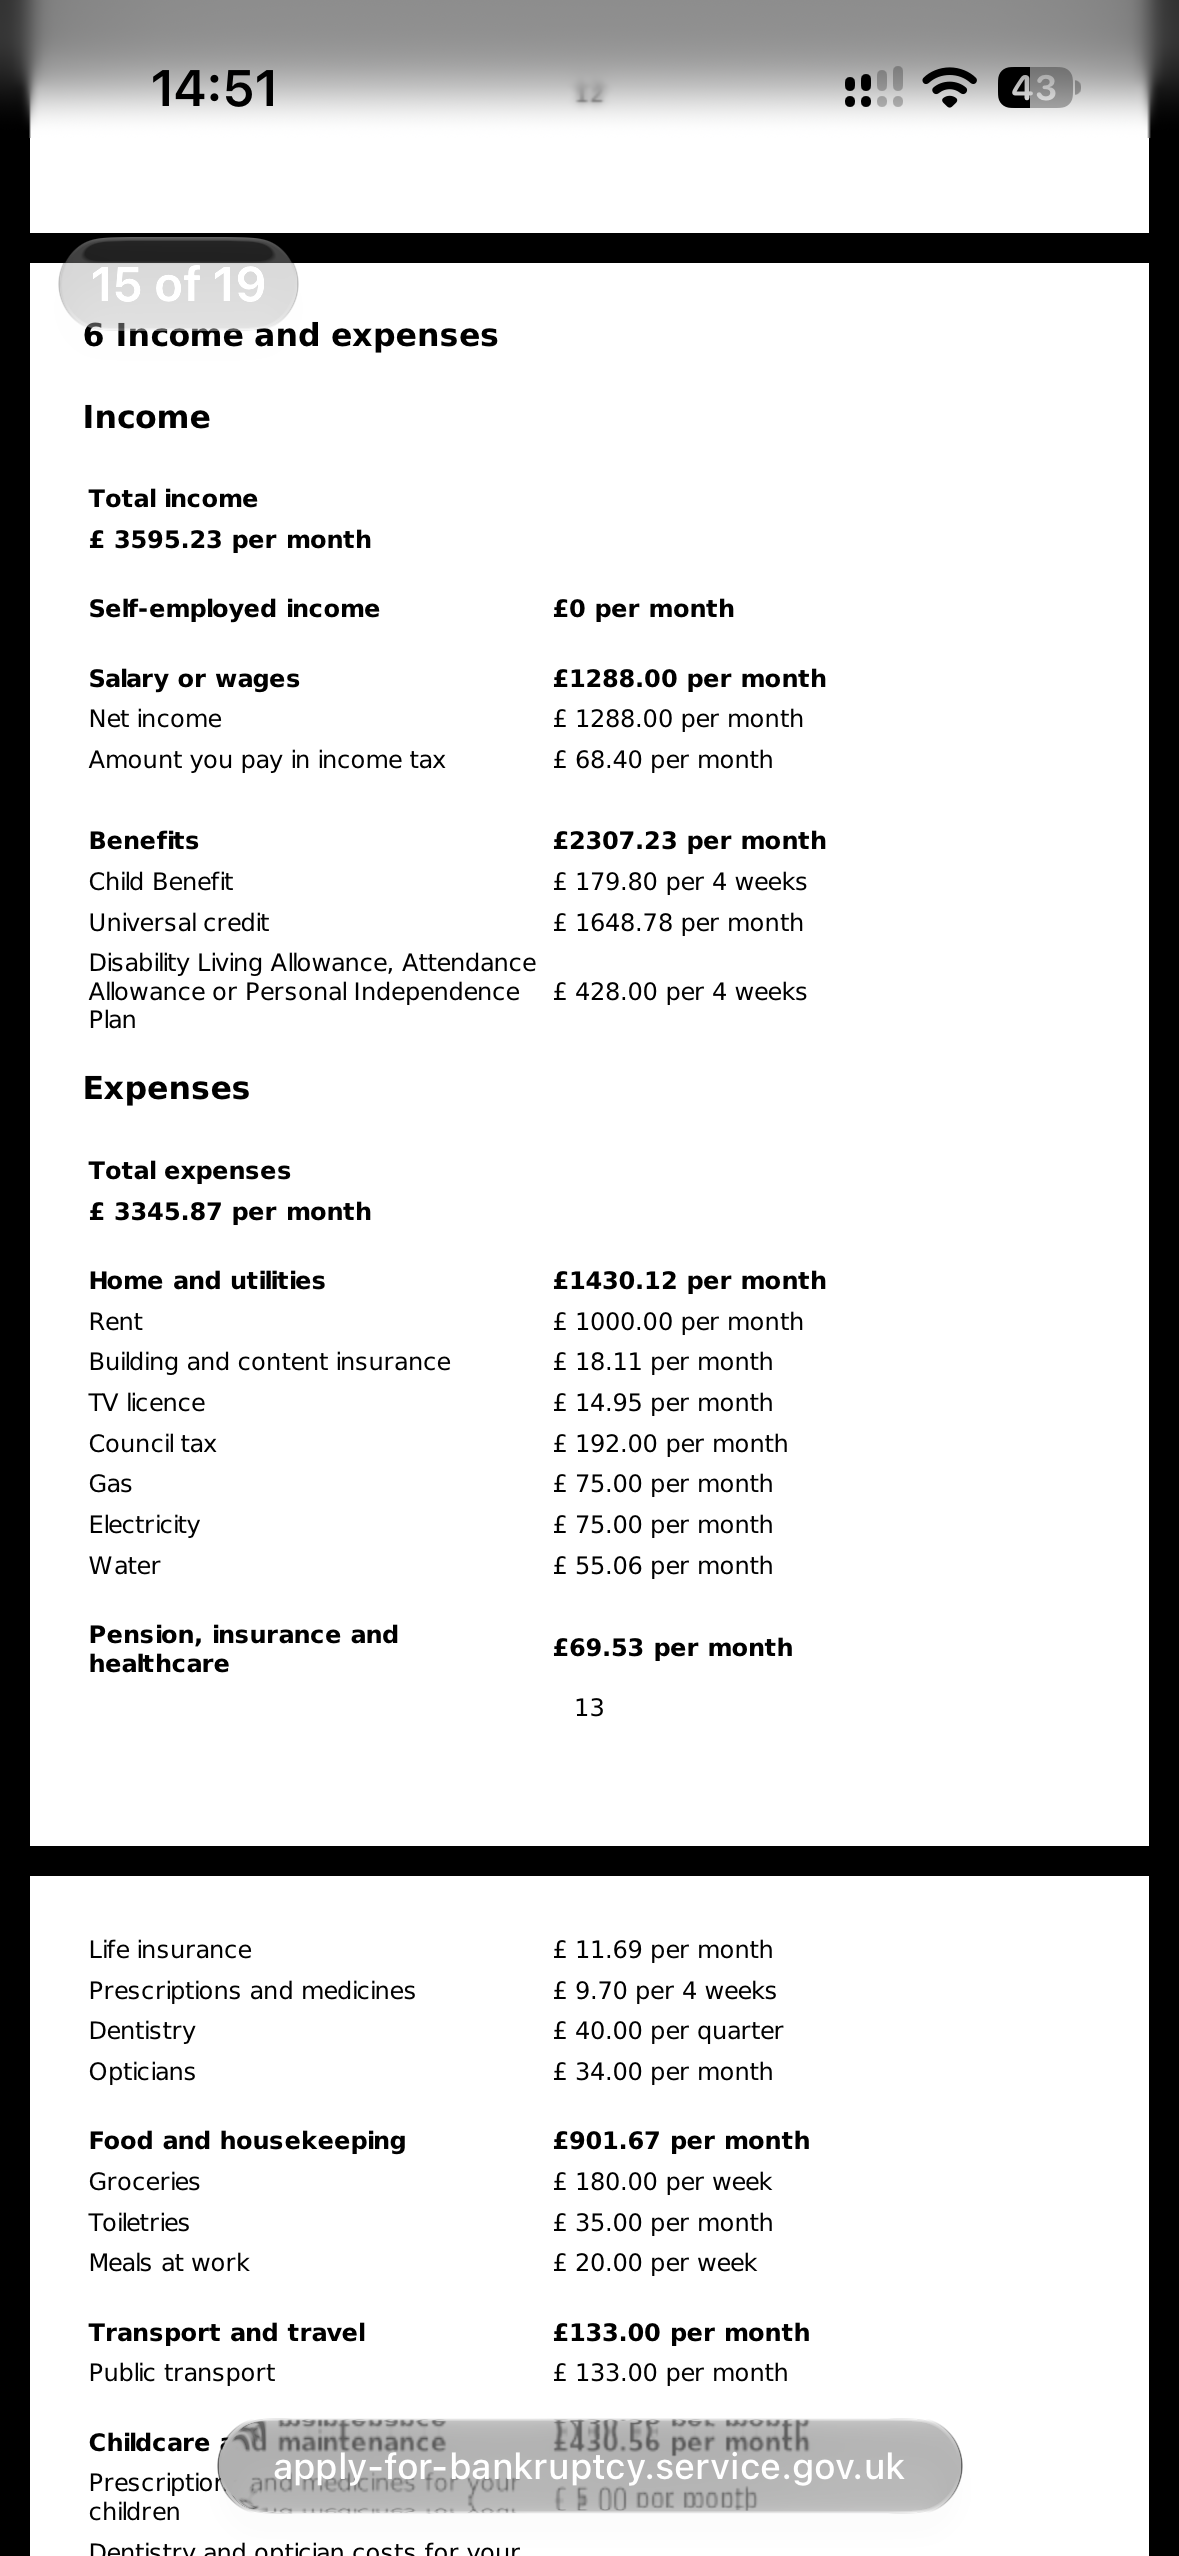
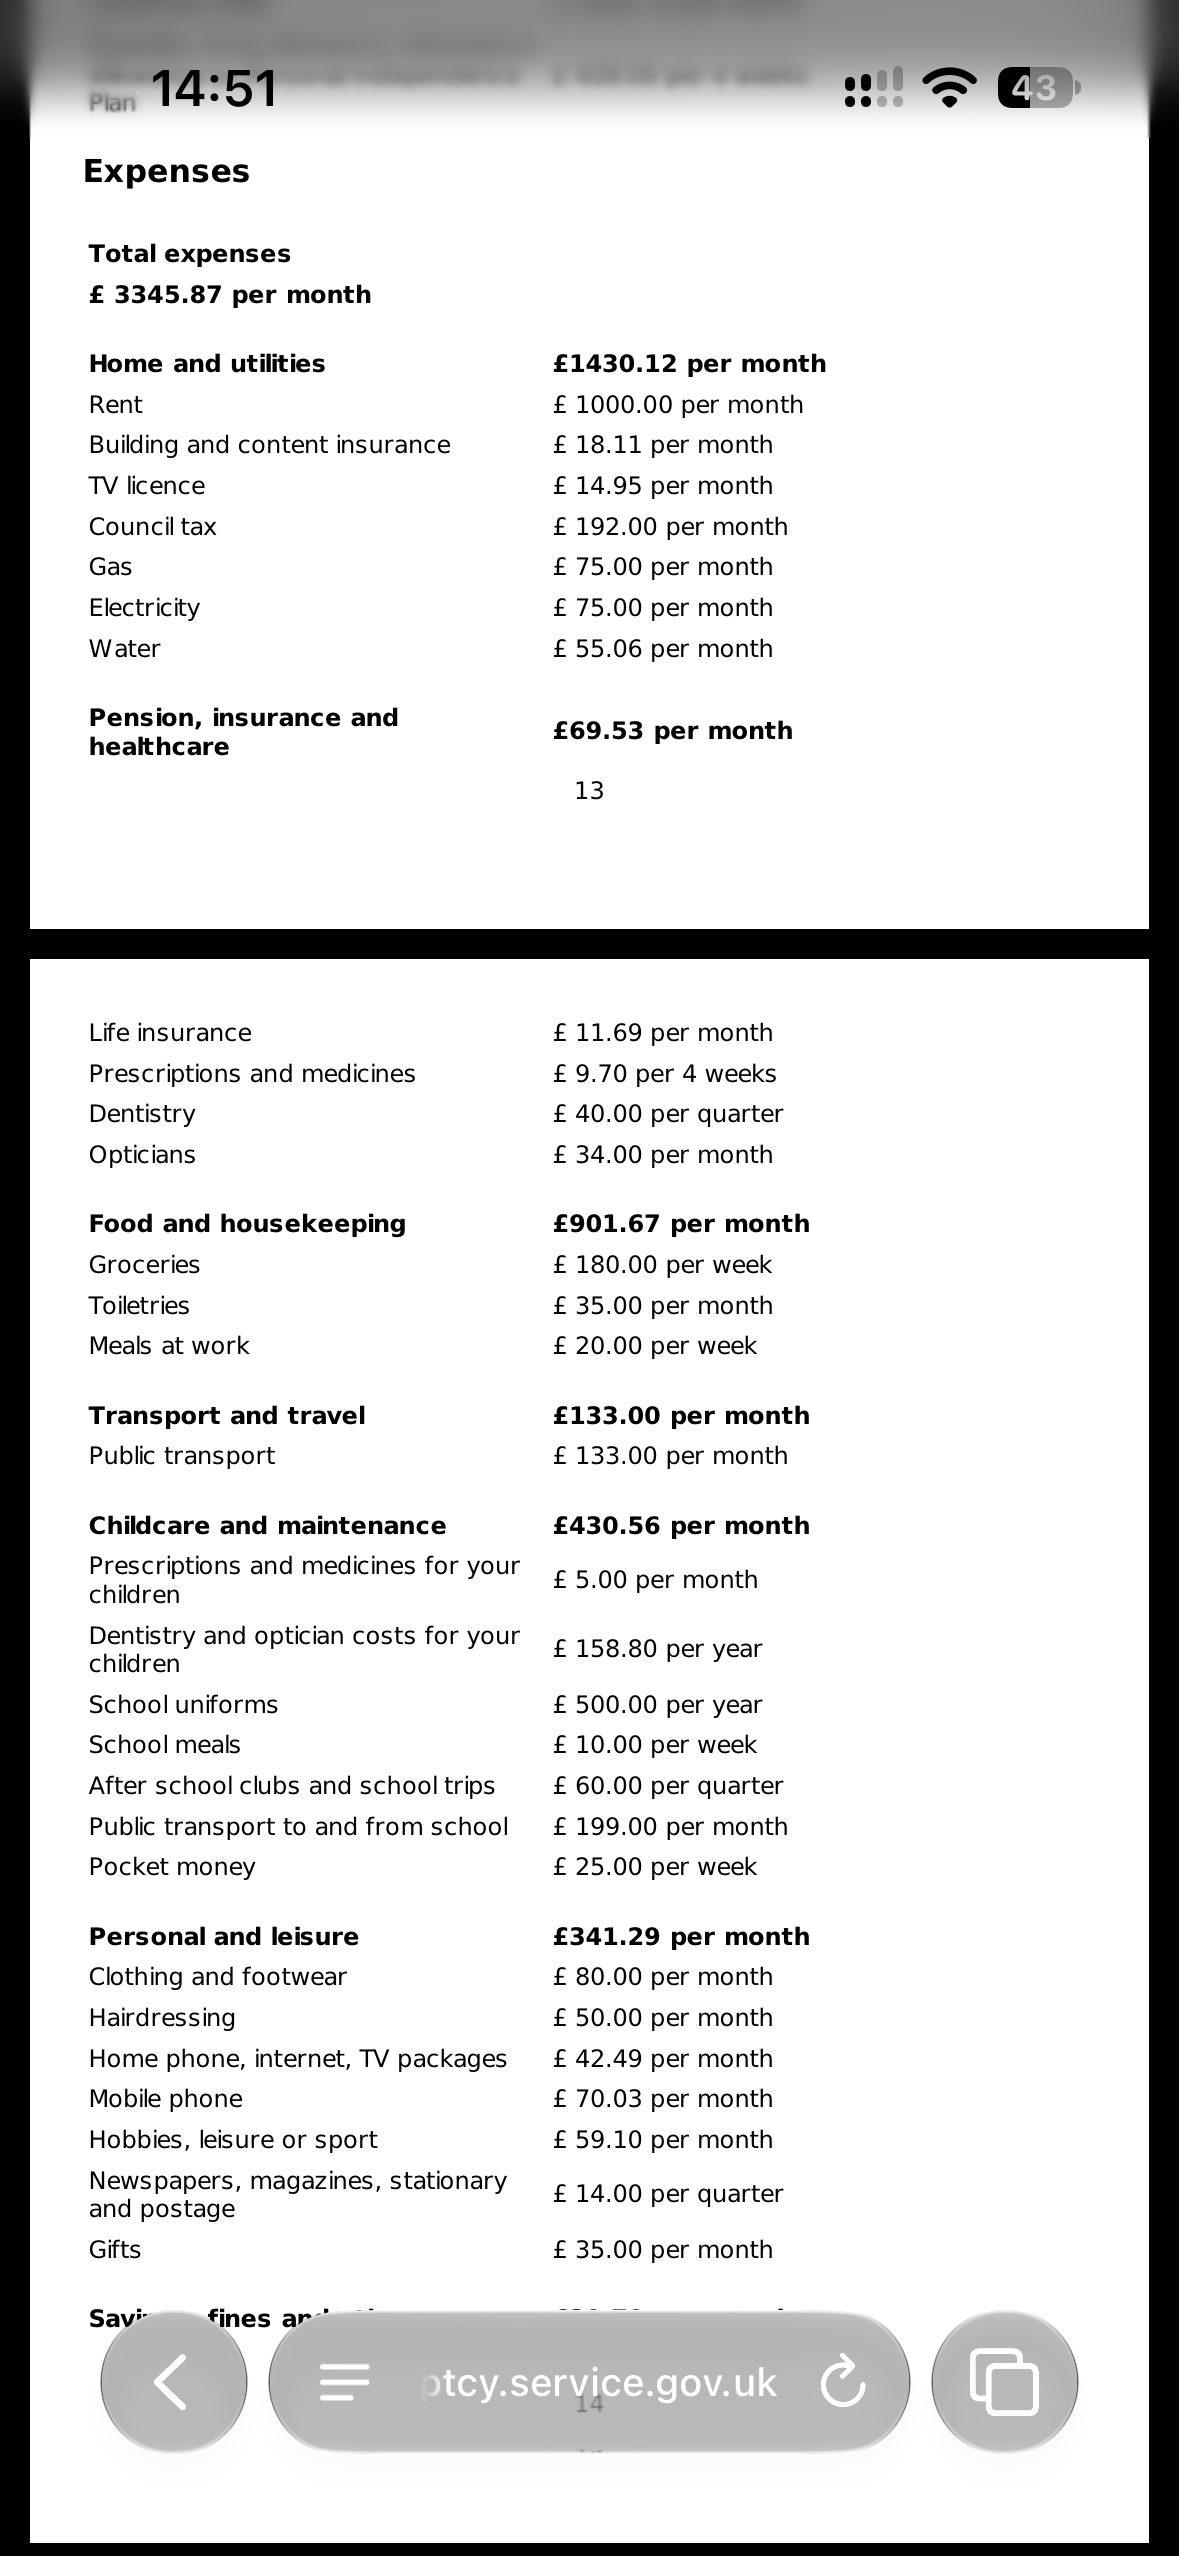
I have filled in my form. Do these figures look ok? Worried I’m totally out or have missed something. Household is 1 adult and 2 children ages 14 & 9 both in adult shoes. One child gets DLA does this get included.
thanks for any help
Comments
-
Exclude the DLA
Looks ok to me
0 -
oh really thanks, I thought it was unfair to include the DLA so that makes sense
0 -
DLA is your child’s money not your, although it will be paid to you. You can do what you want with it, savings account (in their name) or spend it on the things they need.
Proud to have dealt with our debtsStarting debt 2005 £65.7K.
Current debt ZERO.DEBT FREE0 -
Looking at page 13, it appears that if you remove the DLA from the income, you could to be in a negative situation?
Also is rent precisely £1000? Not £1002, say?
If you've have not made a mistake, you've made nothing0 -
yes rent is exactly £1000
What do I do about the negative. Should I reduce the uniforms or Christmas? Or should I put the school expenses like dinners and travel as a yearly amount as school is 9 months
0 -
this takes the “monthly” expenses to 3285
0 -
Not sure if this is in time, but I just did mine & had the interview with someone from the Insolvency Service, and from that my thoughts would be…
- They didn't allow budgeting for NHS dental expenses, other than check-ups.
- You will need to justify the optician expense, but mine was way higher than yours and I just said I needed varifocal reading & varifocal general glasses, each replaced avery couple of years, & have a complex prescription (all true) and they didn't push back.
- I put after school clubs & trips at £35pcm for 3 kids & this wasn't challenged. Think you could maybe go higher than you are.
- Your mobile phone cost looks high to me, so you might need to justify (just a guess - not an expert)
- Your groceries looks a bit high too (almost £700 pcm). Again you may need to justify (also again, just a guess - not an expert), and I don't know if you include alcohol in this - they asked me as a separate section & I think put me down for £20p/wk.
- After discussion they put c.£80 pcm gifts, for kids for xmas & birthday plus other family members. You have 2 kids I think so maybe a bit lower than that, but probably OK to allow higher than you are.
- Hobbies they allowed me £50p/wk - so much higher than you - including an allowance for taking the kids away for a break (which you aren't allowed as a separate category).
Some general observations:
- I didn't get the sense they were trying to cut me to the bone at all, and they even pushed back a little in some areas to make sure I was budgeting enough. It was a fairly friendly process and didn't feel adversarial.
- Overall if your budget doesn't show a surplus that you can pay to creditors I don't think they will be that bothered - your creditors will get your council tax and any income tax you pay anyway.
- I tried to be clear in saying that I've not been budgeting/monitoring how much I spend in these areas so a lot of the figures were an educated guess as to what seemed reasonable, and they seemed happy with that.
- I put in £25 pcm for emergency savings. They didn't allow this but said they do allow you to keep 10% of any surplus for that.
- At the end they don't share the agreed figures with you unless you ask, just the outcome: I was happy with my outcome so didn't ask (which is why I'm not 100% sure of the final figure in some areas) but if you don't think your outcome is reasonable then ou coudl ask and
The whole thing was a lot less unpleasant than I expected. Good luck with it.
0 -
Thanks. I’ll look again any tweak some bits. Like you I’ve not been able to afford some categories so it’s a bit of a guess.
0 -
@FisherKing036 how long did it take from submitting to being declared bankrupt to the interview?
just wondering so I have an idea.Thanks for your help!
0 -
Hi @george_112
from application to bankruptcy order was less than 48hrs, then from that to the income & expenditure interview was 3 and a bit weeks.
Prior to that though I had a call with an Examiner about 2 weeks after the order, who went through my position in overview and got me to forward on copies of bank statements etc. I got the impression he was getting everything lined up so that the asset team and the income and expenditure team within the Insolvency Service could do their bits, rather than being the person who makes the big decisions.
I'm now about 5 weeks in from the order and I have my monthly payment agreement in place but haven't spoken to anyone in the assets team yet, and as far as I'm aware I don't have a nominated Trustee in Bankruptcy yet. That might be unusual - my position is slightly complicated as I own(ed) some rental properties and also have a future interest in a trust, but they must deal with far more complex cases all the time.
More likely I suspect is that they are overworked and under-resourced like a lot of the public sector!
Hope that helps.
0





Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.9K Banking & Borrowing
- 255K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606.1K Mortgages, Homes & Bills
- 179.1K Life & Family
- 264K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards