We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Monthly drawdown v UFPLS logic




For those who want a regular income from their pension and know how much p.a (using £16k pa as easy example)
am i right in thinking have two best options
- UFPLS once a year for £16k - Vanguard sell £16k from the pension, on one specific date , then £4k would hit our bank tax free and the remaining £12k would get taxed - likely HMRC would use emergency tax code as they assume we are taking that amount monthly and we would need to chase HMRC to get the tax back, as it should be tax free ? We would keep the monies in an easy access bank and transfer £1333 pm into our current account (so end of year means received £16k)
2. Monthly drawdown - contact Vanguard and ask them to sell £16k from the pension (again it happens one specific date ?) - £4k would get sent to our bank , the remaining £12k we would need to specify goes into a money market fund (so less exposed to risk) and we would instruct vanguard to sell £1k per month from that funs and they would pay us £1k per month (tax free) ?
is that basically how it would work ?
what do most folk on here do ? unsure if we are missing something
thanks in advance
Mick
Comments
-
I don't know about Vanguard's fees / processes, but many people choose to withdraw once a year, as a) only one set of selling fees and b) only one set of paperwork / online form to complete each year.
2 -
what do most folk on here do ? unsure if we are missing something
What 'most folk on here do' isn't the important question. The so-called 'wisdom of the crowd' is only of value if the crowd are all in the same position and with similar aspirations/requirements - and when it comes to finance, that is rarely, if ever, true. Otherwise it could just be a case of (with thanks to Matt from the Telegraph):
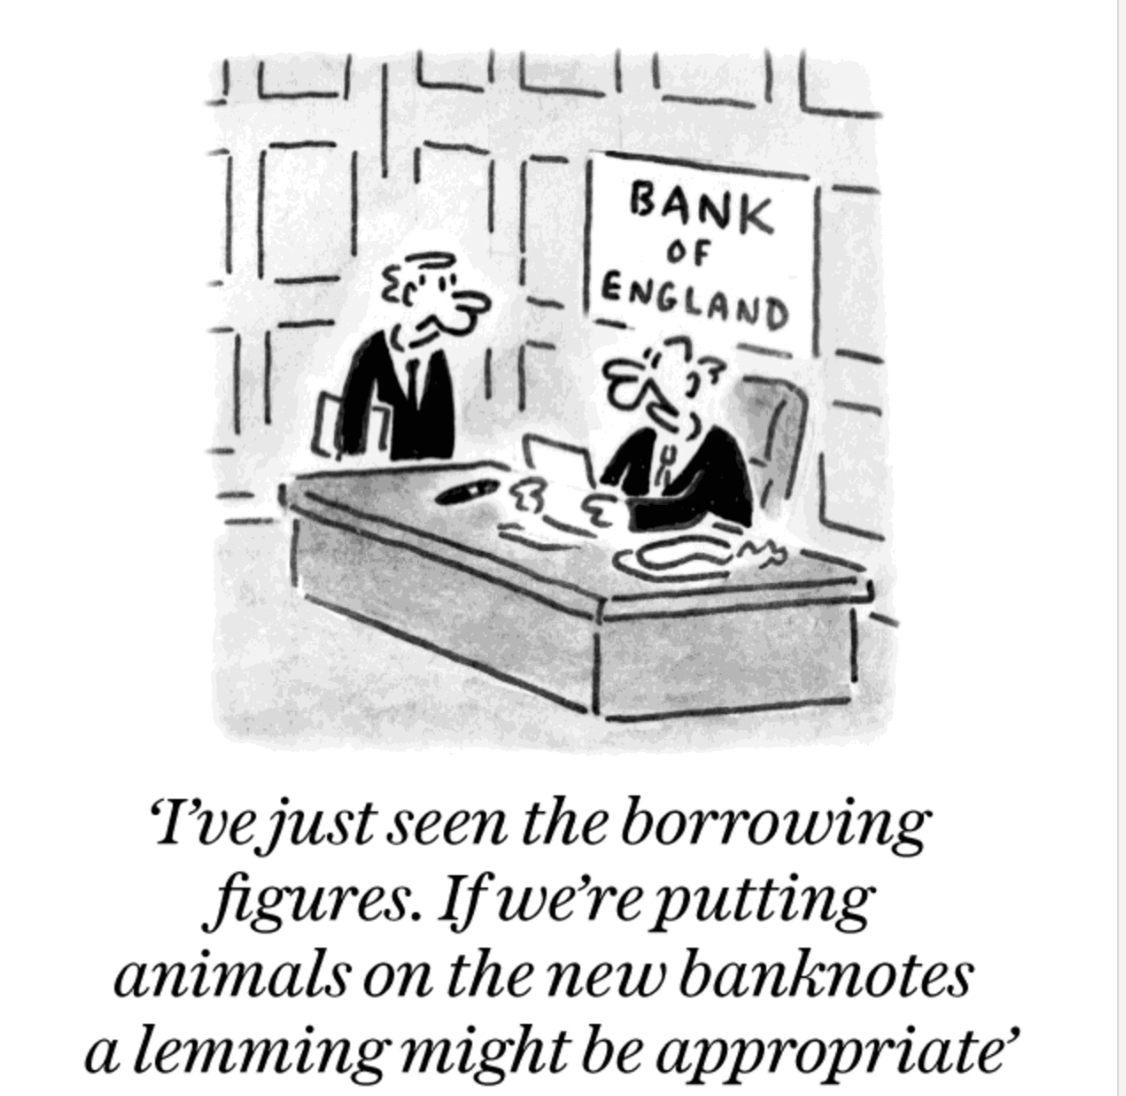
What matters is choosing an approach which is suitable for you and your needs - eg quarterly withdrawals to minimise costs and paperwork when compared to monthly withdrawals, but keeping more of your funds in a tax-preferred environment for longer.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!2 -
I took a 25% PCLS from my SIPP in the summer for a project. Since then I'm taking a payment roughly every quarter from the crystallised pot. This tops up the DB pension that I've had for a few years. The pot is intended to last three years so is all in STMMF. I sell enough units into cash two days before I request each quarterly payment. Other pensions will kick-in in future years so this pot will be emptied.
I took a nominal sum just after the lump sum to trigger HMRC into advising a BR tax code to the pension platform.
As has been stated, everyone's situation is slightly different, however the above is an option for the OP to consider.
1 -
What you suggest might be what most folk on here do is not what I am doing. I think that taking one big UFPLS of £16K in mid April each year is what is done by all the unhappy posters on here who complain about how they are mistreated by HMRC as a result. Indeed it is not even HMRC that is at fault, but how their provider has to apply HMRC processes. I am not sure how the silent majority extract an income from their from SIPP..
In the last 6 months I have retired and started to draw from a SIPP (as well as a DB pension) and a child has graduated and started work - we have had similar experiences as PAYE "new starters". The software used by payroll is required by HMRC processes to assume for our first payment that we will get paid the same each month of the rest of the tax year, and applies an emergency tax code. Data gets sent to HMRC who (discover that the same NI number has other income in the same tax year) and send payroll and taxpayer a tax code that gets used for the second payment. The last payroll of the tax year should finalise everything.
I don't understand the merits of taking a year's income in one go, getting unhappy at HMRC processes that are designed for monthly or weekly paid employees, and sticking the money in a savings account to live on. For me it would have to be a taxable saving account as DB PCLS is going to be filling ISA (and OH's) for a few years yet.
This "folk" asked AJBell to convert about 1 year of SIPP to drawdown, got a small tax free sum, and I take a monthly sum, currently taxed at BR 20%, from the crystallised portion. Yes, I have/choose to sell assets within the SIPP roughly every quarter and leave the money there as cash earning 2.65% tax free (I note that OP can do better than 3.3125% in a taxable EA saving account). I am mildly annoyed that there are not regular disinvestment tools as good as the regular investment ones. Due to, or despite, the actions of POTUS my SIPP seems to worth the same now as 6 months ago (that is political balance)
1 -
Monthly drawdown v UFPLS logic
You can also have monthly UFPLS. Indeed, that is the most common method we use. However, on the DIY side, hardly any providers support it. So, how others do it may not apply to you as you can't do what the majority of our drawdown clients do.
We have others that do a once a year draw using drawdown or UFPLS or PCLS only. Some do PCLS only on a monthly basis.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.2 -
Periodic income and extraction method are two different things. And separate decisions. Yes admin inconvenience can vary. Compliance can make crystallisations (more often for UFPLS) mildly more awkward than adjusting income for already crystallised benefits. But monthly (or any other periodic) income is achievable with either - with a matching provider who supports it (well). You can choose provider and optimise for what they do well or badly. Or choose a method and make it the selection criteria.
Many people favour UFPLS for the 25% tfc baked in as part of annual income tax efficiency and planning. It's handy for net income. Arguments about remaining invested are mostly moot. Aside from the income tax effects the other key argument around UFPLS being superior is "growing more tax free cash" (which applies below the LSA limit). Once TFC is extracted on a % of pension benefits. For that portion - no more TFC is created via growth.
The government (unhappily) has a long track record of fiddling with the rules on this and so "instability" can generally be expected. And you transact to your timing or don't. On rules at the time. But should take a view on how survivable any particular tax exemption looks (IHT 2027 on DC as example).
Others who want capital for any reasons - good or bad. Take some of their TFC as a lump (using a partial or full FAD event on a DC pot.
In which case a chunk of crystallised pension benefits is sat - invested. But marked for income. Still tax free for growth (now that LTA age 75 nonsense are abolished). Then fully taxable for income when extracted.
You can pick a platform and seek out a compliance paperwork efficient provider to do monthly or quarterly. If that's what you prioritise for UFPLS. Monthly UFPLS for DIY is not available everywhere. Or you can find a SIPP/pension provider - on other criteria - range, actual bonds allowed, costs, cashback, reputation, web site colour, guidance services, apps - whatever you like.
I am in the group who uses FAD where you mark a chunk for income. extract the 25%. Then leave invested. And then pay income tax on the income you set. Which can be adhoc, or a regular monthly payroll - which is what I do - like a salary.
My low risk element (portion of income secured ahead of time out of the market) forms part of my total sequence risk hedging i.e. essential income support "buffering". One can choose to have. Some people don't do this at all. And actively want to be invested until the last second.
It's a choice where neither answer is guaranteed to be "correct" for all cohorts and market conditions. It clearly carries an opportunity cost in a consistently rising market. Immediate cash for x months income in cash or mmf funds. I like it because nothing invested in growth assets is sold until I choose to sell it - no income sales. Only rebalancing. I can control the timing (within a period of a few months anyway) and also which funds are sold. For flash crashes and 2020 style dips this can be helpful for confidence in the stability of your plan. It's a technical argument (unwinnable) due to unknowns about the range of conditions in which this is better. Or worse. The answer is "it depends". In many conditions - worse. But you don't get an average. You get yours.
Nonetheless different people will have wildly differing views on the wisdom or folly of this. A generally supported view is that it is important that YOU have confidence in your plan - whether adviser assisted or not - to ride the rapids when they inevitably occur and pension deaccumulation investing becomes exciting.
At each rebalancing say 12-18 months - I move some investments into a cash "fund" for the next period of income. And I instruct the scheme to pay income - from available cash (SIPP), or a specific cash fund only not to consume across all.
Consume across all is a "no effort" approach. Your portfolio isn't reshaped by income being taken. Good.
But will be reshaped by investment returns fund by fund (unless a very simple self-balancing multi-asset style or similar). I use a few funds to diversify my portfolio from global equities. So I created my own "rebalancing" need. And I am happy (at the age I am at now) to do this now and then.
It is possible to simplify this to the point that all you need to do is adjust income amount once a year or to taste.
Or you can actively manage investments monthly and release money each month - if that's your preferred way of working.1 -
I am in the group who uses FAD where you mark a chunk for income. extract the 25%. Then leave invested. And then pay income tax on the income you set. Which can be adhoc, or a regular monthly payroll - which is what I do - like a salary.
I think this may be what I am tempted by. I have a SIPP with Bell, and I would like to take/crystallize (say) 30K per annum as a means of satisfying my day to day spend. I assume the partial TFLS of 7.5K would land straight into my current account? The remaining 22.5K would be taxable and I believe I can take that as a sort of taxable monthly income of 1875/month.
Would this be a reasonable method to employ as regards fees Bell may charge, and from an HMRC perspective?
Each year I'd consider matters/see what I am spending and perhaps vary the 30K up or down accordingly.
0 -
You can also have monthly UFPLS
Not automatically with Vanguard (who the OP is with) - you have to manually instruct them each month.
Since I (a) don't want to drawdown a year's amount in one go and (b) CBA doing the manual UFPLS thing, then PCLS part of it (for the next year, or whatever) and you can then auto-withdraw monthly from the crystalised bit is what I'll be doing next year when I'll be able to.
Which is basically OP's 2nd option.
Conjugating the verb 'to be":
-o I am humble -o You are attention seeking -o She is Nadine Dorries0 -
There are providers without those fees.
It's better to do it monthly so the tax sorts itself out
0 -
Move the pot elsewhere who do offer automatic drawdown options
0











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards