We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Bridging Strategy




My original strategy had been to start drawing my DB pension early next year alongside a 9 year IL Gilt ladder to State Pension age.
Having recently received an updated DB forecast the Early Retirement factors had worsened slightly so I took another look at the figures using Guiide. The figures on the left are the original plan and the figures on the right are an alternative plan where I condense the Gilt Ladder to just 5 years and leave the DB until NRD (2032 age 63).
The Gilt Ladder is represented by the yellow savings pot:
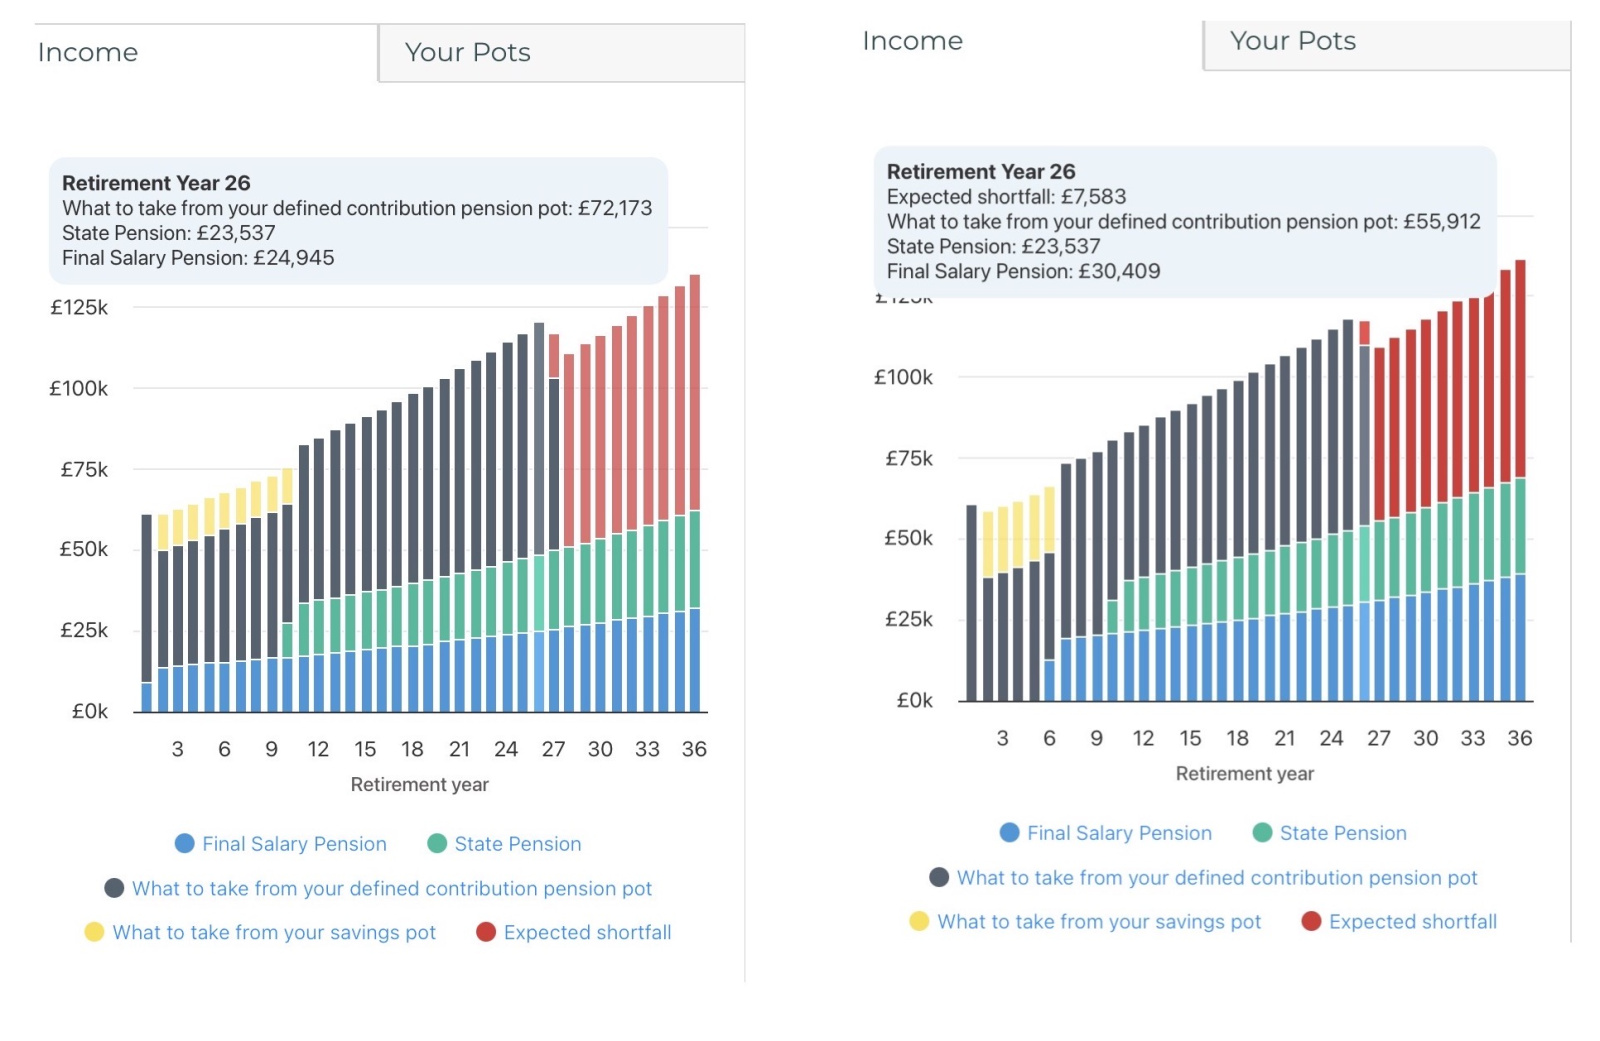
Collapsing the Gilt Ladder to 5 years instead of taking the DB early does mean that the pot is forecast to run out a year earlier (year 26 age 83 vs age 84) but the upside is an extra £5.4K guaranteed by the DB.
There is a 3rd alternative which is a little more dynamic, to review the core DC performance at the end of each year. If the DC has held up well despite withdrawals then stick with NRD for the DB and also consider rolling the Gilt Ladder back a year; if performance has been lower than hoped for then start taking the DB early.
Comments
-
What's the question?
I don't know if you're overcomplicating things. Why not forget about the gilt ladder and just take more from DC drawdown up until the times when DB at NRA and state pension kick in?
🐻 A little FIRE lights the cigar0 -
Clearly your original strategy was to build a gilt ladder specifically to cover the period until a deferred income stream (the state pension) started. That made perfect sense. If that worked for you then, why not just convert some of your DC funds into a further ladder to cover the new proposed gap until your DB starts?
I would also be looking to draw from the DC at a (hopefully) sustainable rate, or buy an annuity, rather than plan for it to run out in my early 80's.
0 -
I have already started taking money from the DC earlier this year. The Gilt Ladder is intended to work in conjunction with the early DB to protect the DC pot against SORR during the early retirement phase up to SP. Once I commit to taking the DB then that cannot be undone but I am now considering a more dynamic approach based on actual yearly DC performance.
Interested to know what others think?
0 -
There are tax advantages to taking more from the DC before SP age. I’m reasonably comfortable with the possibility of the DC pot running out in the early eighties as do not expect to need as much in later years, obviously I would be more than happy if there is still money left.
0 -
My first thought (being an avid Guiide fan) is would be do you really need your income to increase with inflation right up in to your 80's and beyond??
Do you really feel you would need an inflation equivalent income of £70-80K per year from that age onwards?
• The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.0 -
Quite possibly not in which case the pot will last longer.
It’s more a question of which is the right bridging strategy, if there is such a thing. Im definitely coming around to the idea of not taking the DB early unless there is an SORR issue.
0 -
"There are tax advantages to taking more from the DC before SP age."
Is the gilt ladder in a pension? If not, then I would definitely be taking the full 20% band from the DC every year and re-investing any surplus in ISAs as you are odds on to be a higher rate tax payer eventually.
I faced a similar situation, although a longer bridging period. I too left my DB until 63, but that was to maximise my guaranteed income.
One approach you could consider is to roll over you gilts if stock prices remain high, gradually increasing the proportion of your bridging needs that they cover as time goes by.
1 -
Is that State Pension figure (£23,537) correct ? It looks incredibly high to me - or are you planning for two people ?
0 -
Thats what Guiide estimates the SP will be in 26 years time….
1 -
The Gilts are in a SIPP but in my own mind I treat them as deferred cash rather than any form of investment
0









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.7K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards