We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
I need help understanding my civil service pension forecast please.





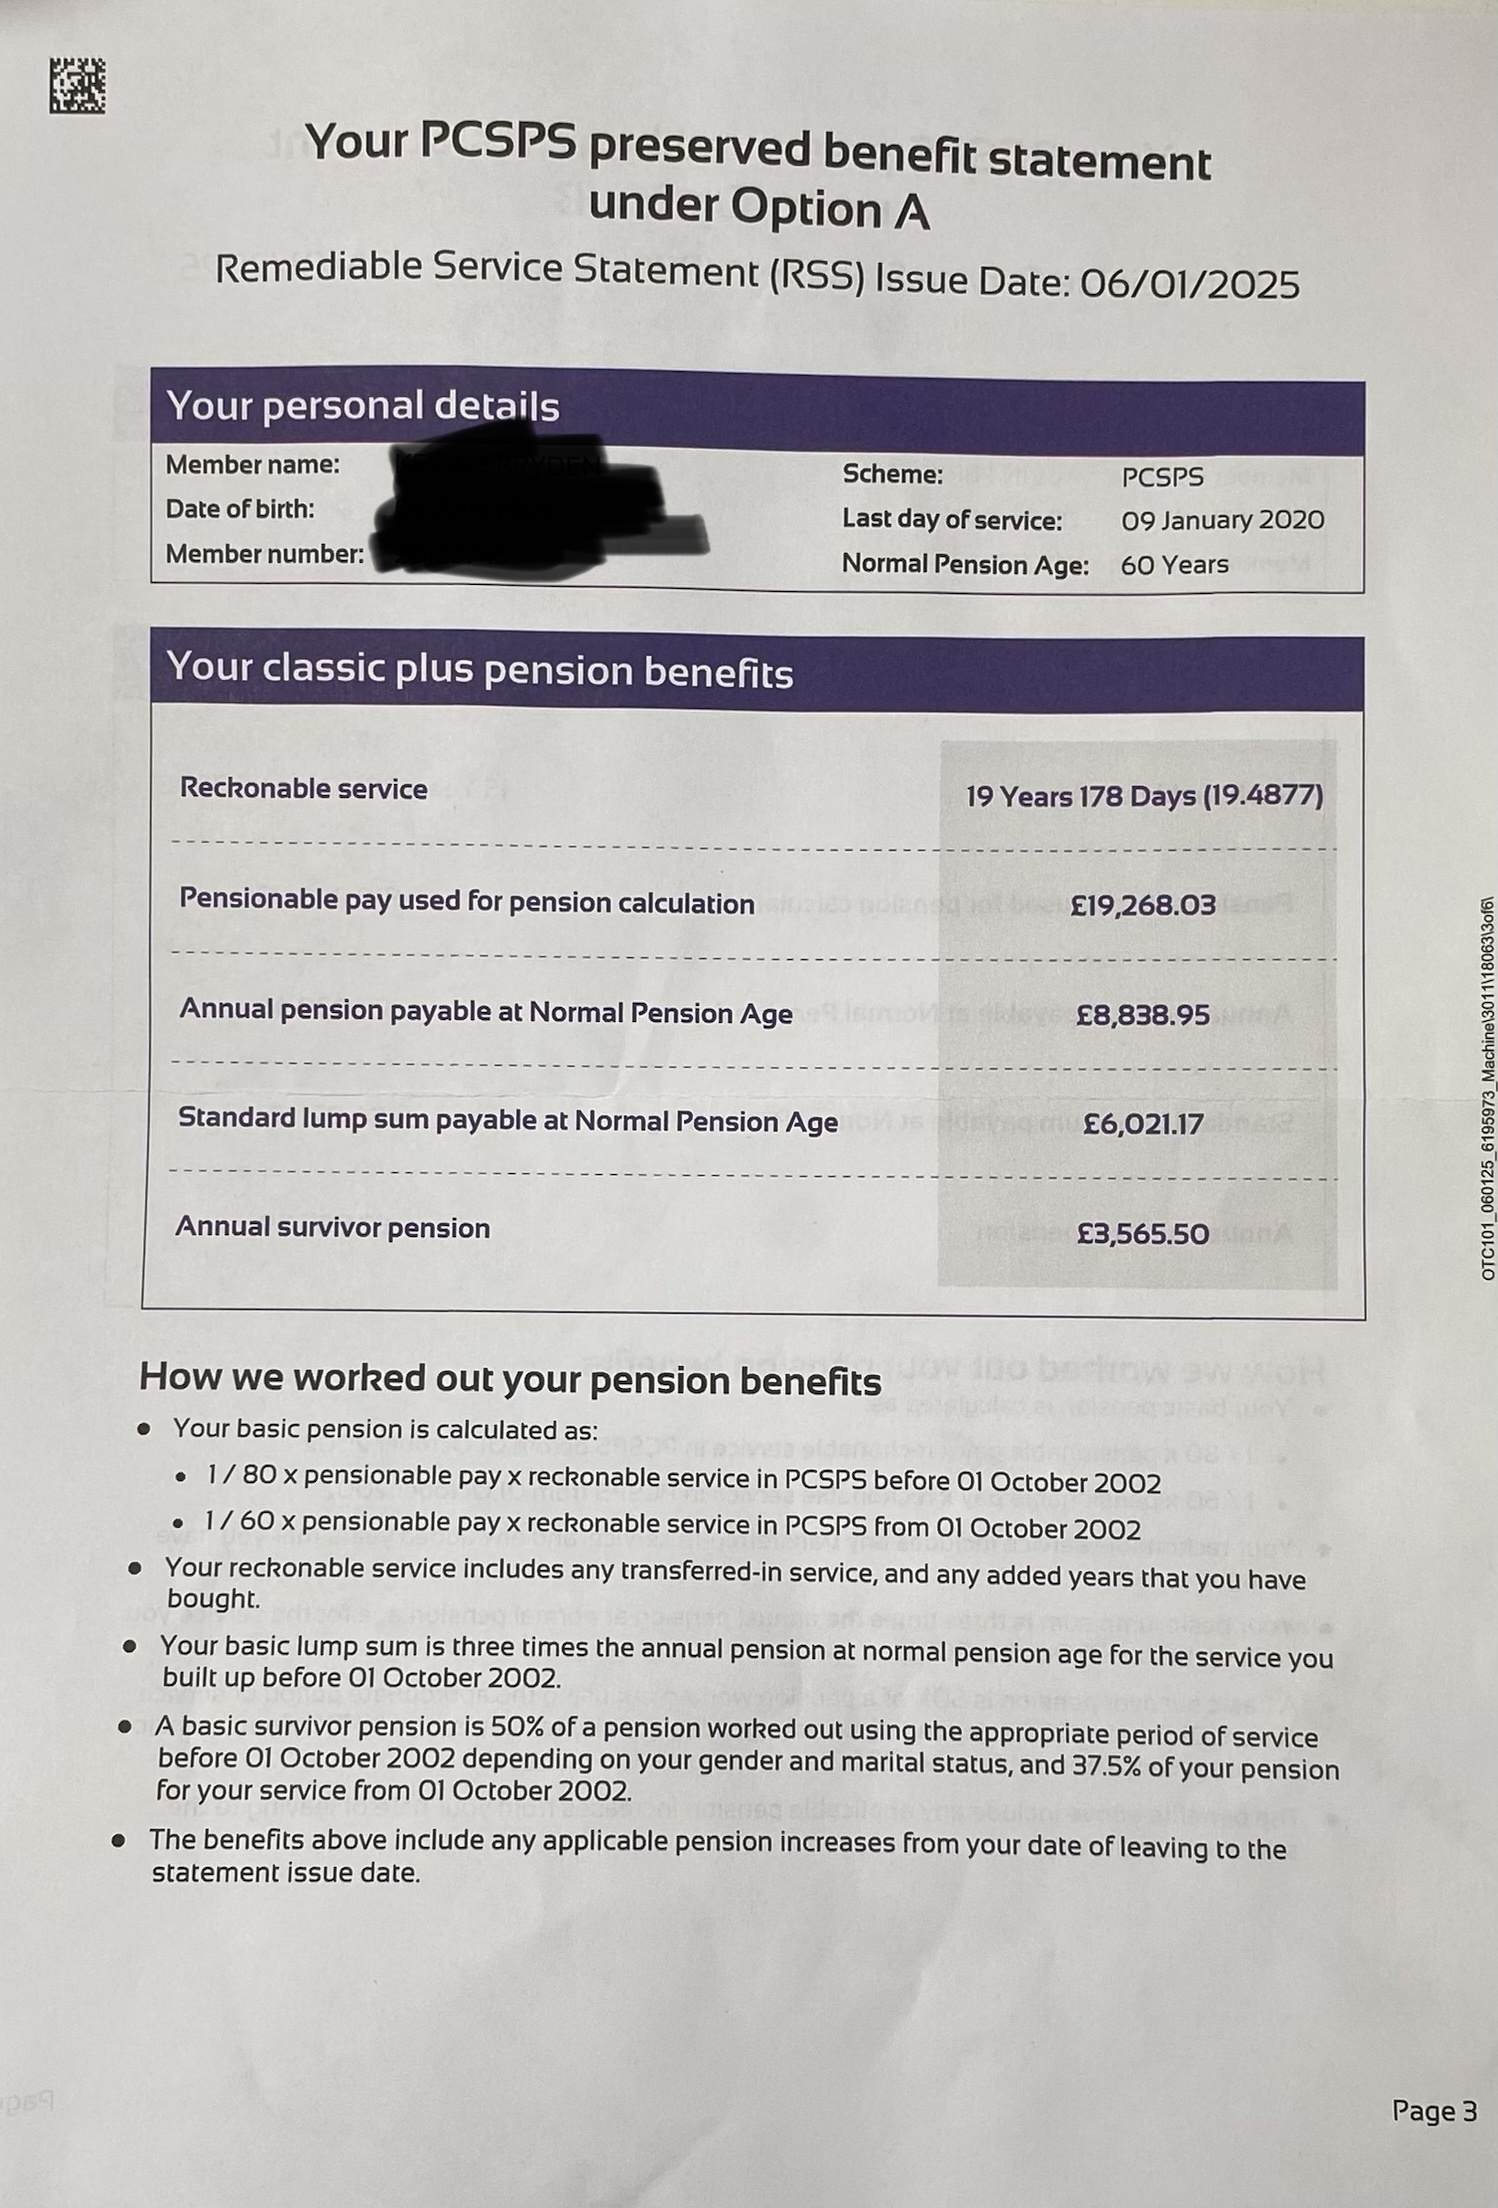
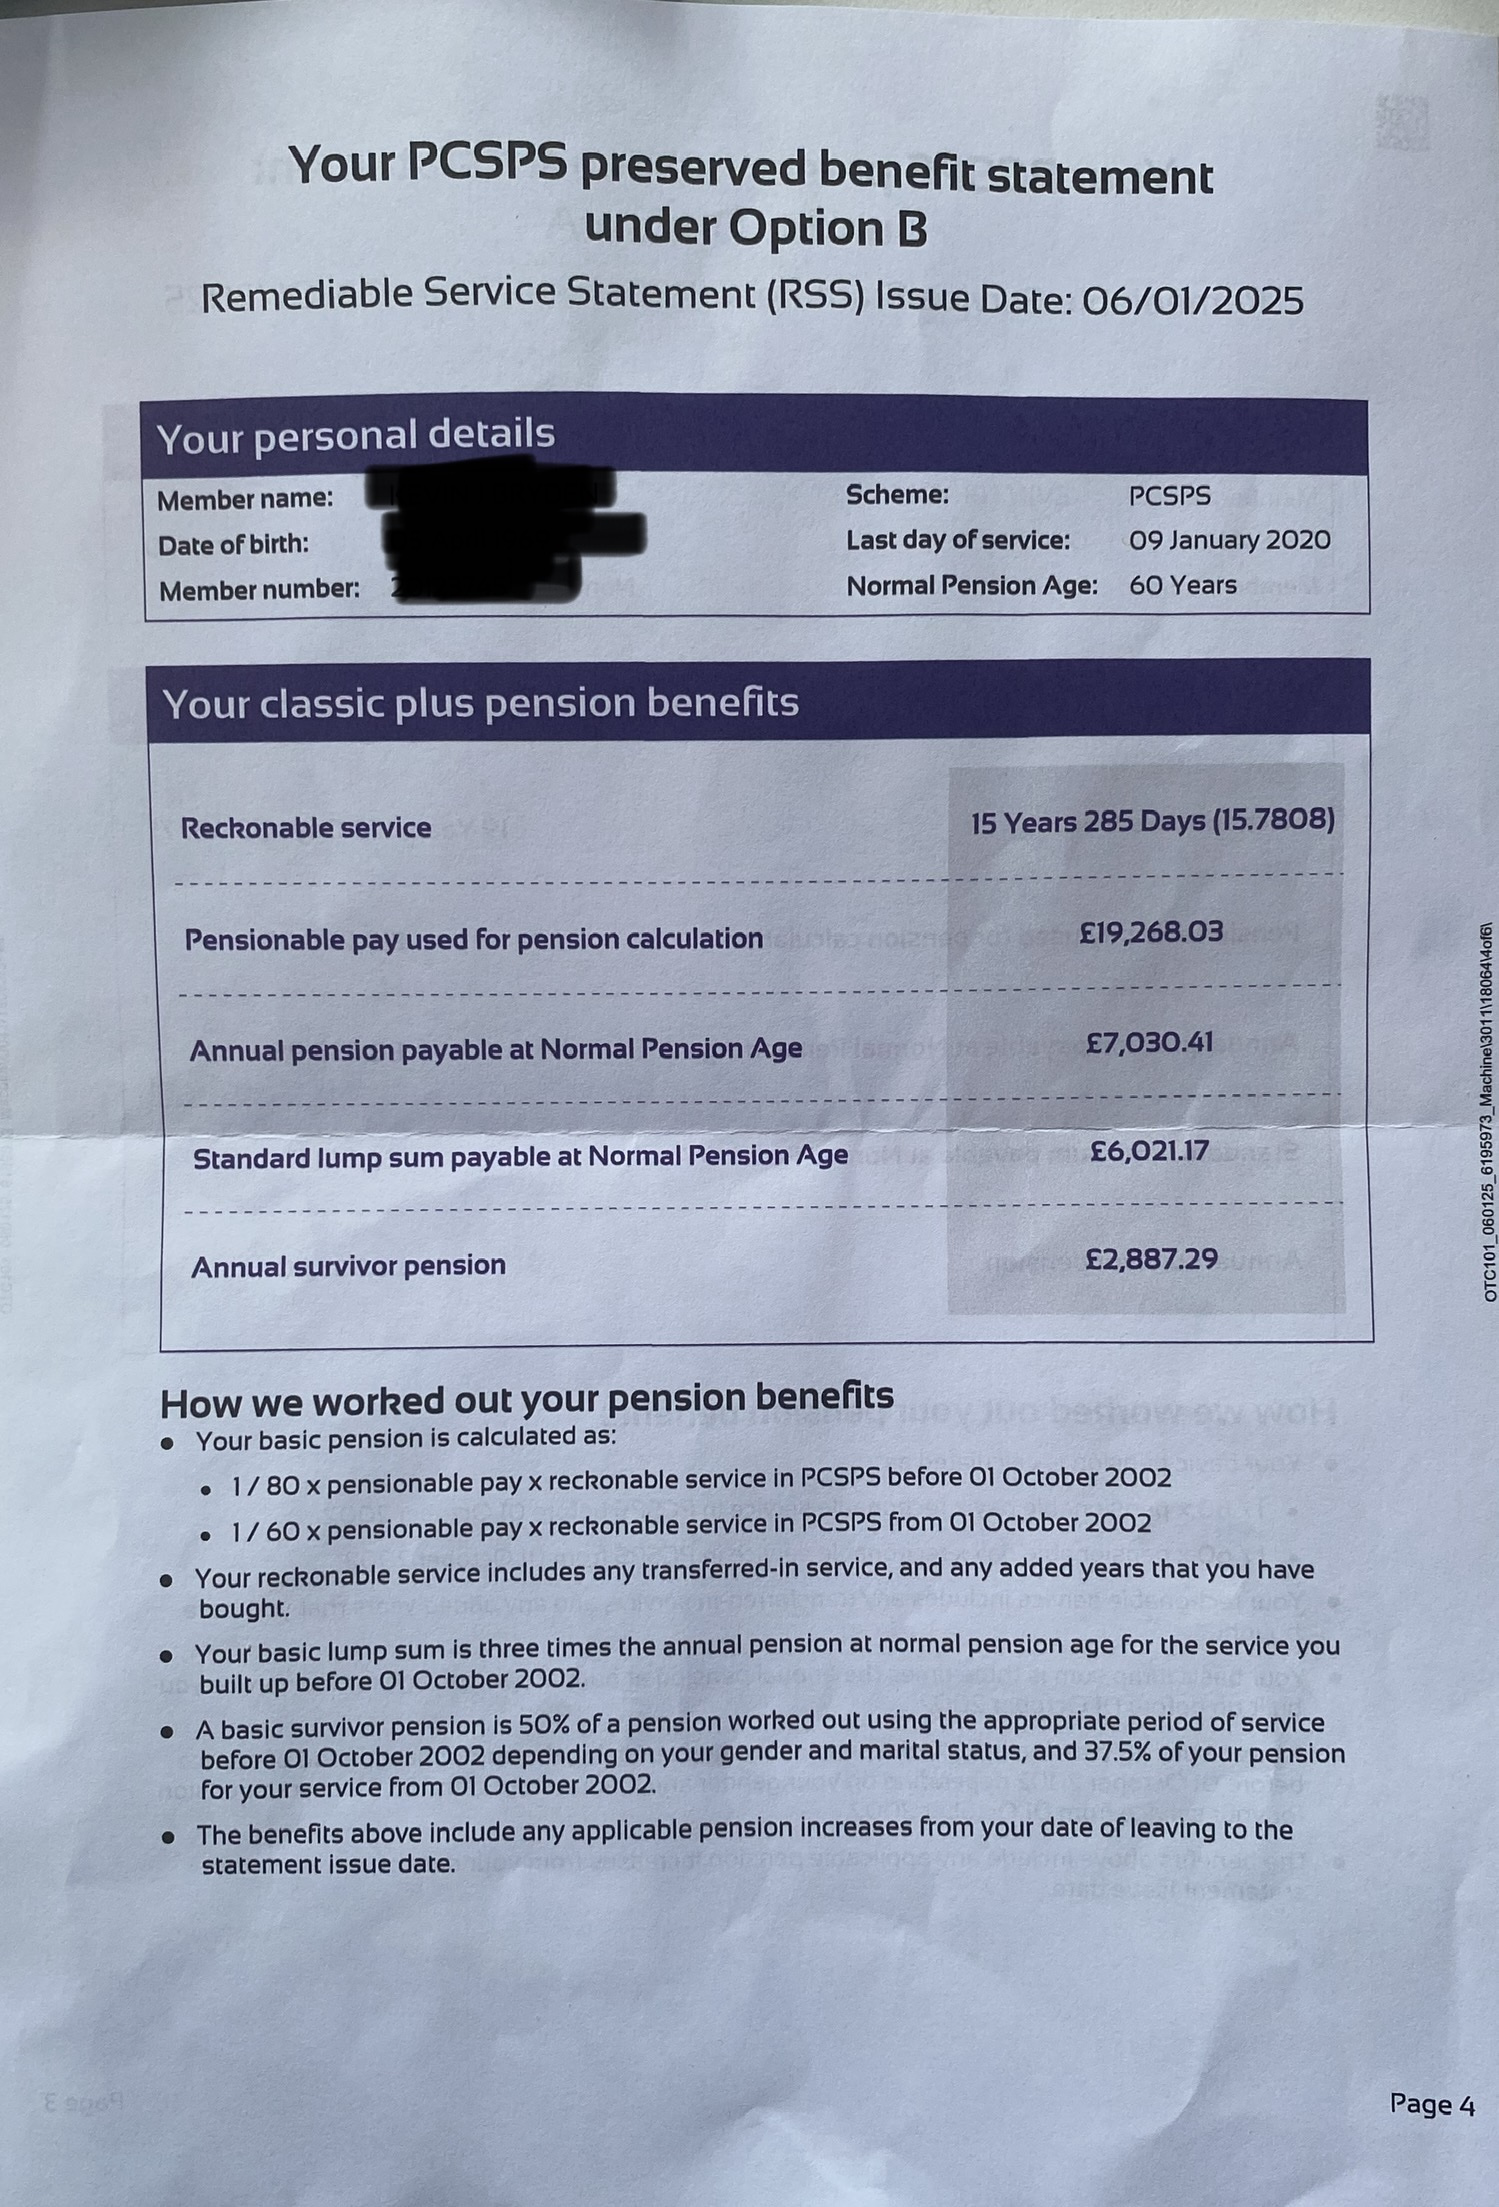
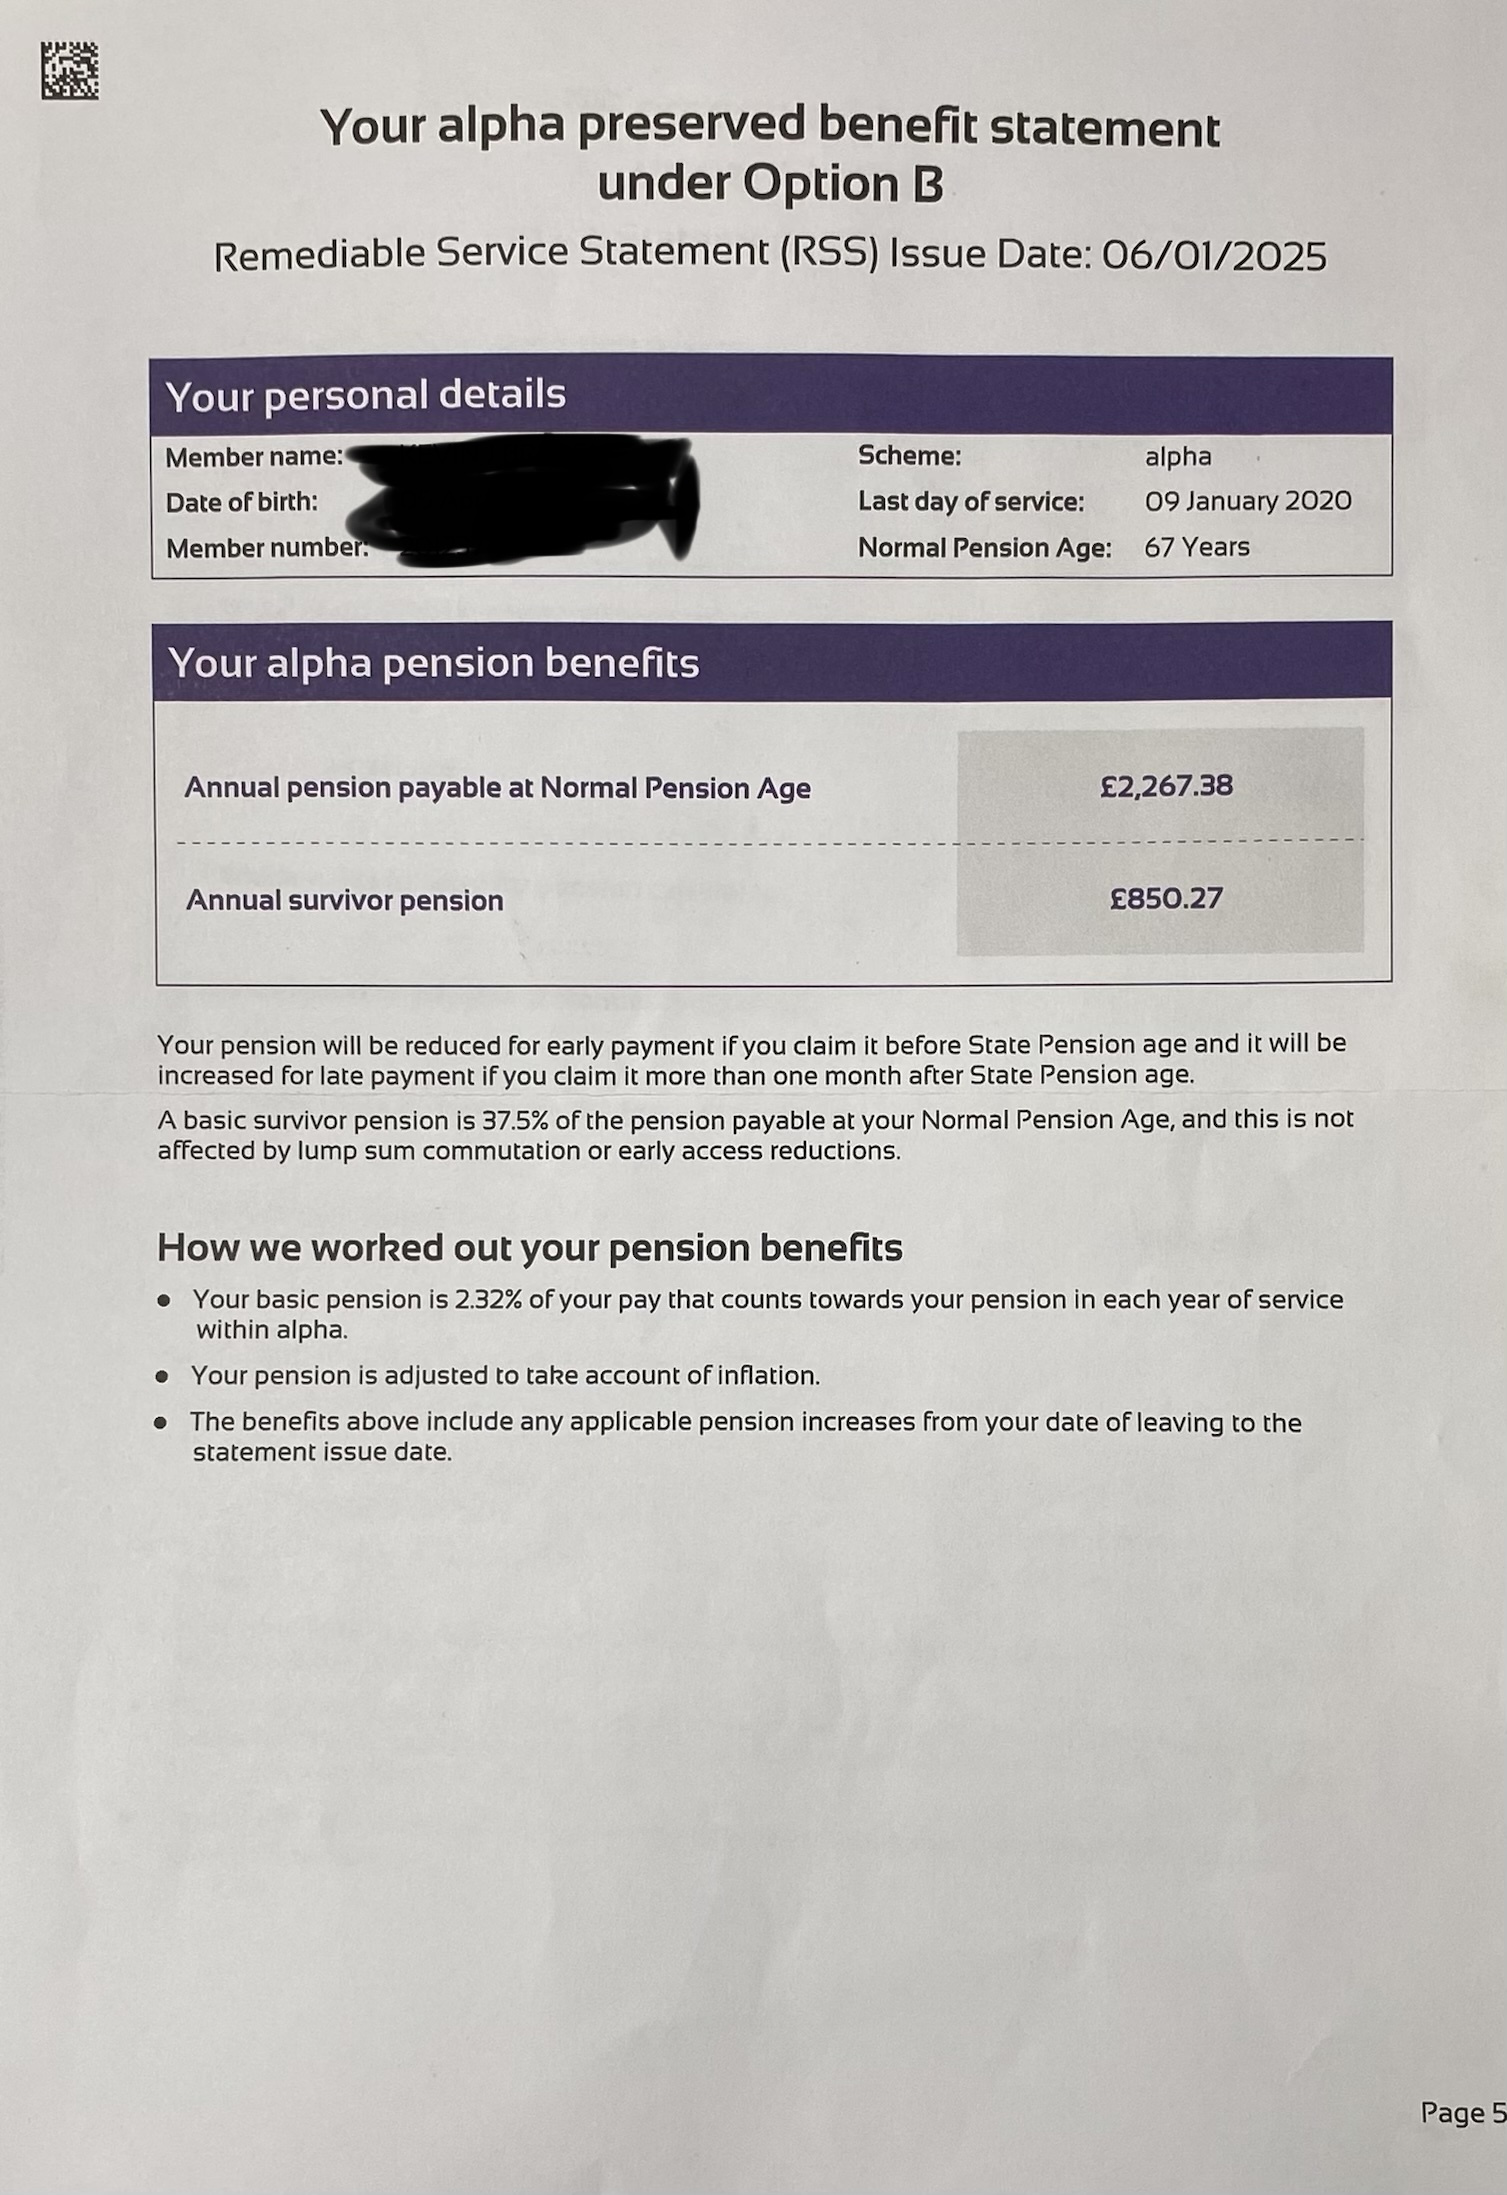
In January 2025, I received a letter from CSP regarding the 2015 remedy(McCloud). Attached were the pension options below.
My ex wife seems to think that the forecast should be broken down for classic and classic plus. That first image only shows the classic plus part. I joined in 1997 and left in 2020, so I was part time for part of my service.
There is huge difference between option A and B.
Is the 8838.95 figure the amount I'll actually get?
I've applied for a new estimate, it says it could take up to ten working days but it'll probably be months. ;o)
Many thanks in advance
Edit: I can't believe how stupid I've been. I didn't think to turn page three over. Just wasn't expecting double sided printing. I feel like such an idiot.
Comments
-
You've shared pages 3 and 5 of your forecast. What do the other pages say?
Page 3 says it's for Classic Plus, page 5 says it's for Alpha. Does one of the other pages relate to your Classic pension?
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.1 -
I wouldn't be surprised if other pages would be Alpha pension benefit under Option A and And Classic Plus pension benefits under Option B.
1 -
My ex wife seems to think that the forecast should be broken down for classic and classic plus. That first image only shows the classic plus part. I joined in 1997 and left in 2020,
The Option A statement includes both pre and post 2002 service, so there is no separate classic part to show.
It is worth being clear about what each option covers:
Option A
- Classic-like benefits within Classic Plus from date of joining in 1997 to 30 September 2002
- Classic plus benefits from 1 October 2002 to date of leaving in 2020
The amount you are due from age 60 is shown as £8,838.95. Since the statement there have been upratings in April 2025 (1.7%) and April 2026 (3.8%) so those will have increased the amount due under Option A at age 60 to £9,330.80.
Option B
- Classic-like benefits within Clasisic Plus from date of joining in 1997 to 1 October 2002
- Classic plus benefits from 1 October 2002 to 31st March 2015
- Alpha benefits from 1 April 2015 to date of leaving in 2020
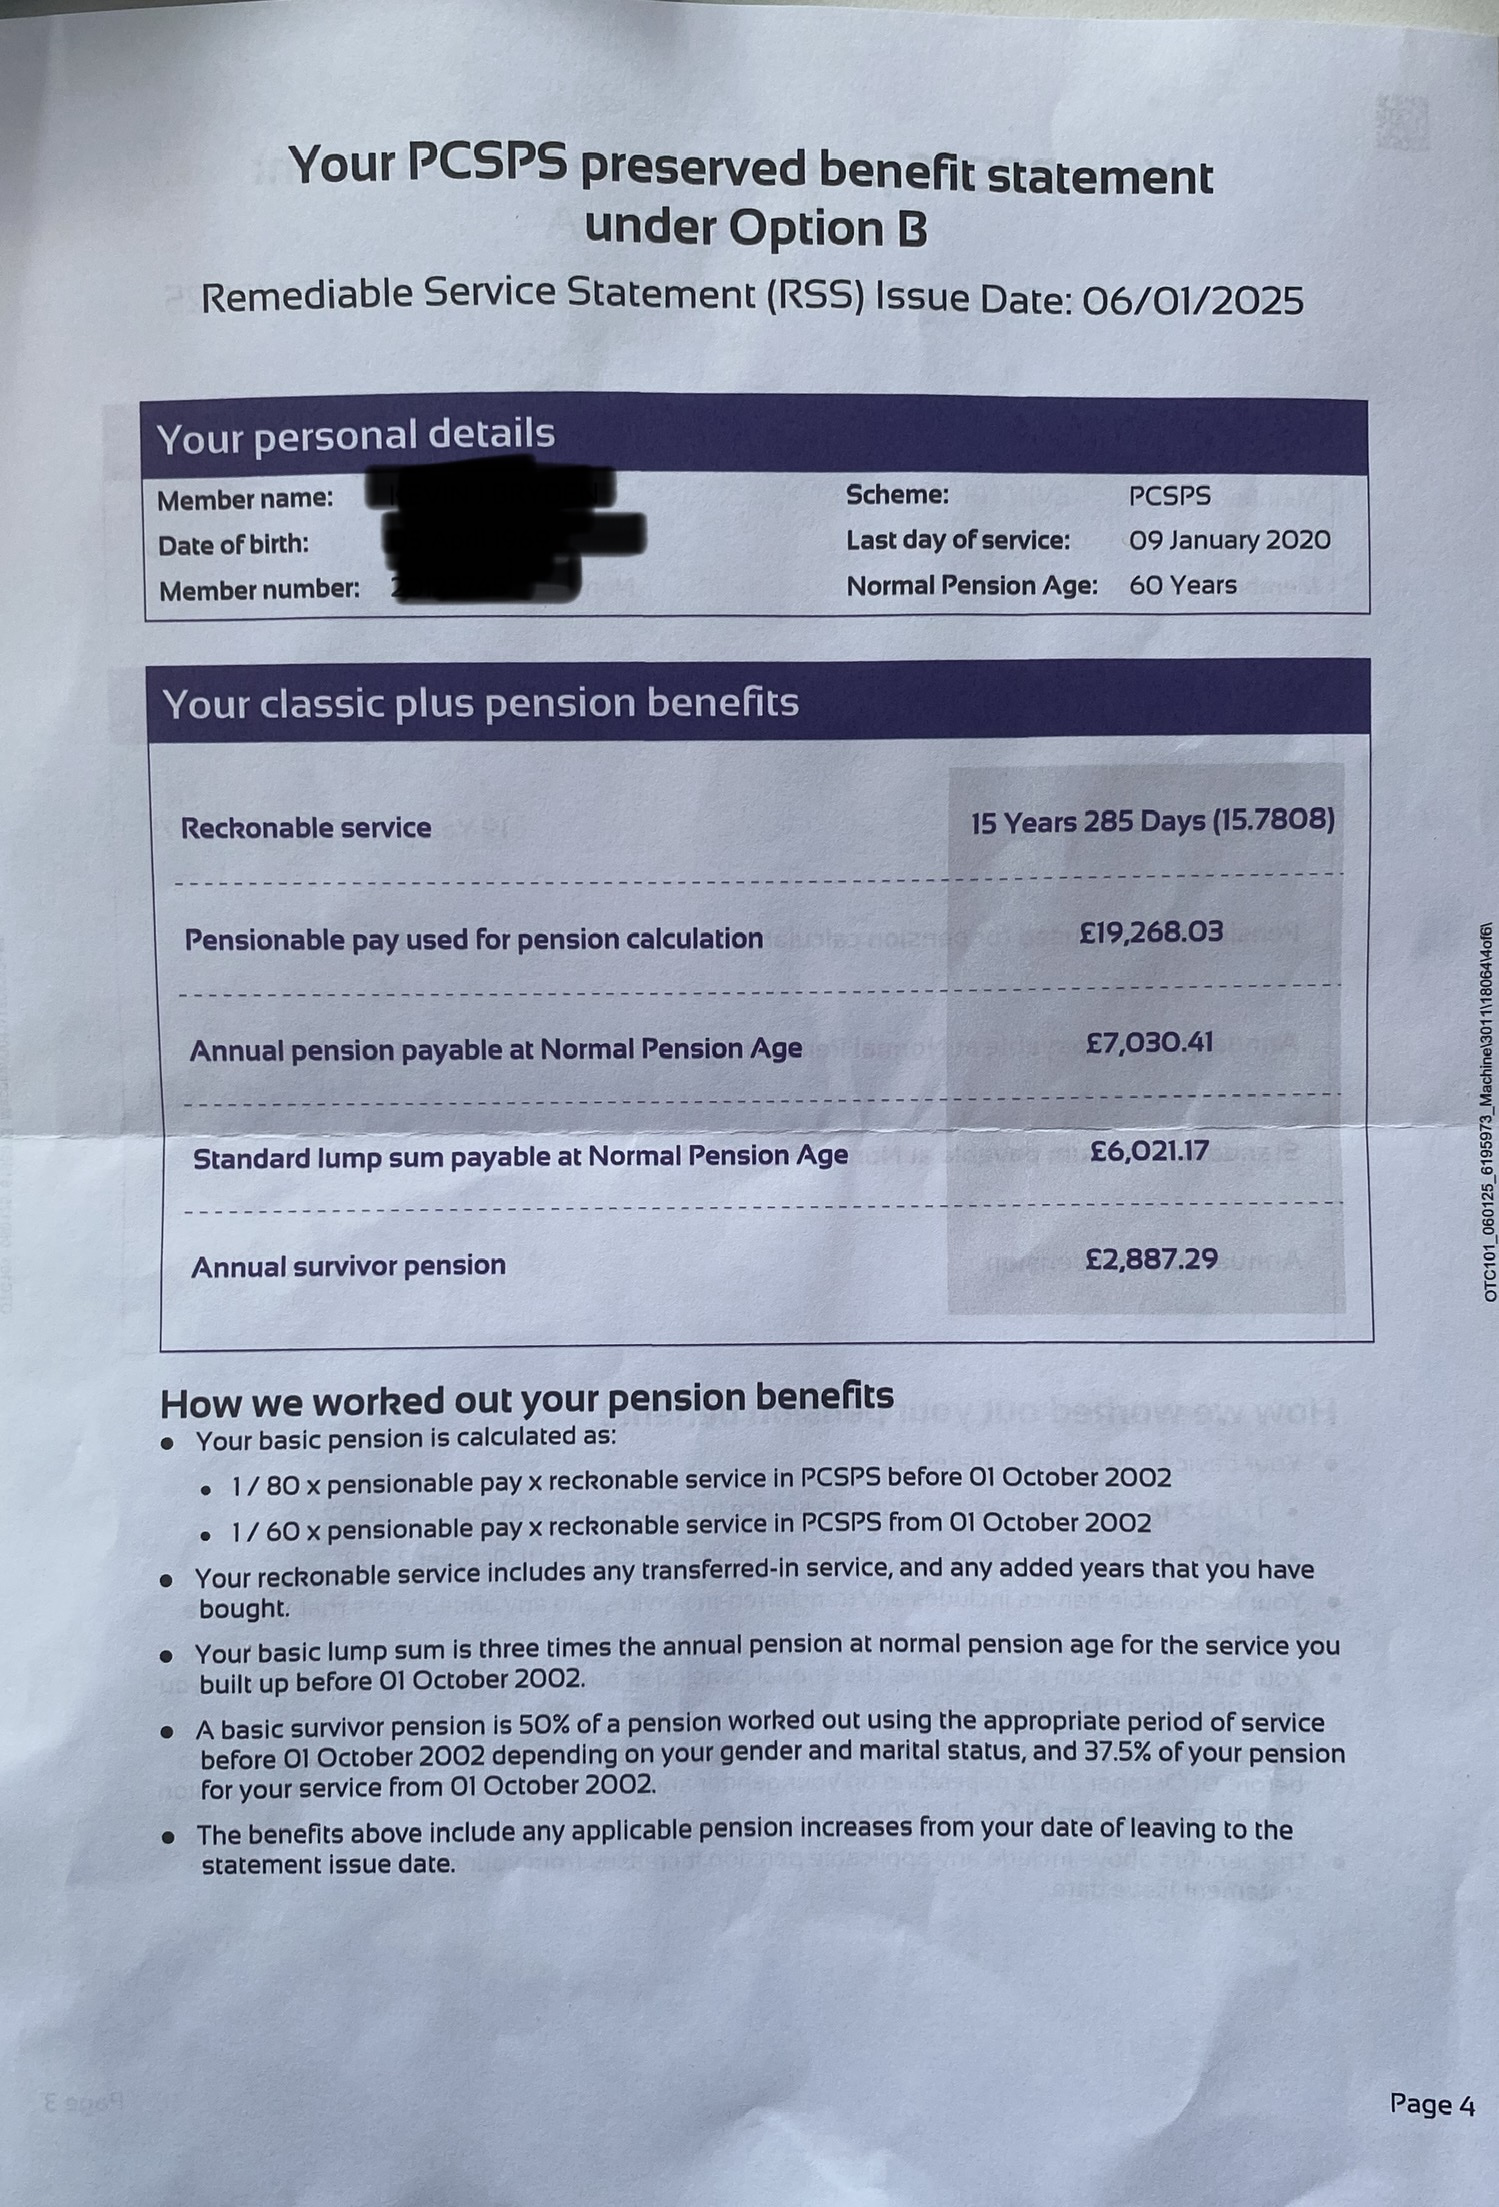
Page 4 of the statement probably shows your classic plus benefits under Option B. You would receive those in addition to the alpha benefits shown on page 5. You need to revalue both by 1.7% and 3.8% to bring them up to the present time.
You will almost certainly find the outcome under Option A and Option B is extremely similar after taking account of actuarial reductions for payment at 58.5 years of age. Option A is probably going to be slightly better, but it could go either way.
2 -
The McCloud case gave you the option of your pre-alpha pension up to 31 March 2015 or to 31 March 2022 and alpha thereafter.
in your case it seems you left 9 Jan 2020, so it would show option A as classic plus up to 9 Jan 2020 and in Option B it will show classic plus to 31 March 2015 and alpha from 1 April 2015 to 9 Jan 2020.
You pick the option that suits you best, which will depend on when you want to take your pension. If yours want to take the alpha before your state pension age then you need to use the factor which are on the actuarial reduction tables linked to on the capita civil service pension site. If you want to take the alpha at state pension age then the amount shown is what you you may get - it is adjusted by the Sept rate of CPI on 1 April each year, so just an estimate- if you take it after SPA then it is increased, factors are in the tables.
You get the choice now, and have a year in which to choose or capita will choose the option they consider to be best for you.
But without seeing all the figures it’s not possible to give an opinion.1 -
I don't believe I missed this. I'm such an idiot.
So as I read it, I'll get more in option B but will have to wait another 7 years to get the alpha element.
 0
-
Classic plus was one of the options in 2002 when you could continue in classic or convert your classic to premium or you could leave the classic you had as was and have premium thereafter, which was called ‘classic plus’
Premium accrued at 1/60 rather than classic’s 1/80, but had no automatic lump sum.
1 -
You get the choice now, and have a year in which to choose or capita will choose the option they consider to be best for you.
That is for the Immediate Choice population, which are those who had pension in payment as at 1 October 2023.
In this case, the individual does not yet have pension in payment and so will make their choice when they commence benefits. They can only commence benefits by making an election, Capita will not default them into either option if they do not make an election, the benefits simply are not put into payment until an election is made.
So as I read it, I'll get more in option B but will have to wait another 7 years to get the alpha element.
You can take the benefits early with actuarial reduction. Alpha is reduced by 30% if taken at age 60 rather than 67. You should calculate the benefits payable at a given age to compare which is better.
Option A would give you £9,330.80 pension and £6,356.22 lump sum at age 60, as calculated in my post above.
Option B would give you a pension from Classic Plus of £7,421.62 (£7,030.41 x 1.7% x 3.8%), a pension from alpha of £1,675.49 [(£2,267.38 x 1.7% x 3.8%)*70%], and a lump sum of £6,356.22. The combined classic plus and alpha pension is £9,097.11.
That means Option A appears better, which is usually (but not always) the case for Classic Plus where standard lump sum is chosen.
Taking Option A benefits at age 58.5 with actuarial reduction would mean a pension of £8,733.63 p/a and a lump sum of £6,203.67 being put into payment. This would increase in line with CPI each year, both before and after taking the pension (link to calculators here)
5 -
Taking Option A benefits at age 58.5 with actuarial reduction would mean a pension of £8,733.63 p/a and a lump sum of £6,203.67 being put into payment.
In the opening post of the OP's other thread they say they were hoping for £8600pa at 58.5, and that was with an assumption of full reverse commutation (ie. no lump sum). £8733pa plus £6203 cash is a significant improvement on that.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.1 -
Yeah, I've updated my post now. Thanks.
1 -
I know, I'm really happy with that. I'm glad I came.
1







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards