We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Should I pay into a pension or savings account in my situation


I'd really like some advice regarding pensions and savings accounts for when I get to pension age.
I'm 43 and I've always suffered from anxiety and depression from a young age and I've never been able to hold down a job. I went to see a therapist when I was younger and realised the only way my life was going to get better was to stop worrying about working if I could survive without work.
I'm lucky enough to have a wife who works and provides for me. She is very understanding and we have managed very well in life so far.
I'm not entitled to benefits as my wife works so since I was about 21 I've never earned money so I don't have a pension and I'm worried when I get to pension age and my wife does we will struggle. Even though we have made it this far.
I was lucky enough to of came into some money £150k which year on year we put it into a year savings account and earn about 4-5 % interest on it and we simply reinvest it. As I'm not a tax payer from what I have read I can earn this amount of interest without paying tax on it as I have no earnings.
My question is do we carry on doing what we are doing or should I start paying into a private pension. Would this benefit me more then doing what I currently do?
Thanks
Comments
-
Without any earnings, the amount you can pay into a pension and get tax relief, which is one of the benefits of a pension is £2880 per year (will become £3600 in the pension after tax relief).
If your wife is earning, it may be better to add to her pension instead.
0 -
As a non-earner the most you can pay into a pension is £2880 in a tax year. You will get tax relief of £720 on top which takes it to £3600. The earliest you can access it, for someone your age, is 57 but this could rise in the future.
Other options is a stocks and shares ISA, which could get a better return than you are getting.
Final point, you say 'we invested it' - does this mean it's in a joint account or solely yours. If joint your wife would need to pay tax on her half.
0 -
If you're planning to keep the 150k long term for it to provide additional income, surely you would want to consider funds regardless of what tax wrapper you use? Also note if your wife isn't saving much then you've got stocks&shares 40K per year ISA availability (or cash ISA if you insist until April after which it reduces to 12k I think.).
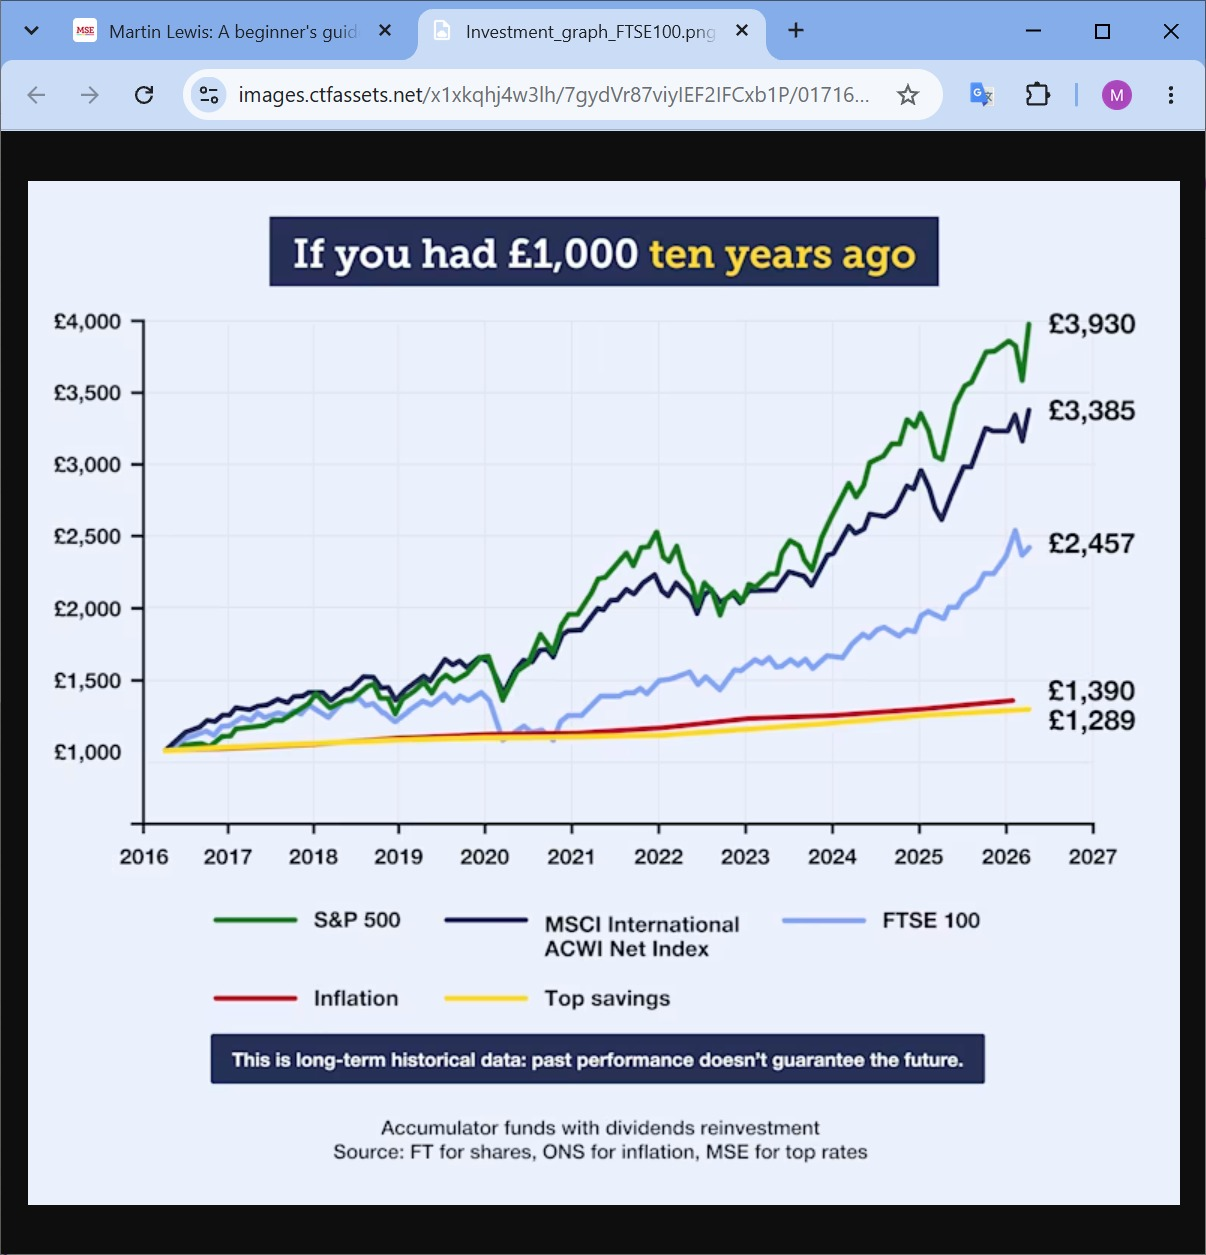
This graph is from MSE itself. I don't know if the years were picked in order to emphasise their point, but I think it makes the situation crystal clear. I guess you'd be on the yellow line at the bottom - earning nothing above inflation.
 0
-
AS above your wife could add more of her earnings to her pension, and you could drip feed some of the £150K to pay for day to day expenses to compensate for her lower take home pay.
0 -
How much state pension have you earned, will you earn by the time you are 67? If you have money to save for a pension then you may be better buying NI credits. If you are not claiming benefits now then you might not be able to claim pension credit, or whatever that looks like in future.
1 -
Hopefully I'm asking something unnecessary - have you transferred a portion of your tax allowance to your wife already?
And poking my nose in….is there any "work" you might consider? delivering pamphlets? gardening? Anything where you aren't under someone's thumb and you could stop and start as you wish. Having a small income like this would allow you to put more into a pension.
I’m a Forum Ambassador and I support the Forum Team on Debt Free Wannabe, Old Style Money Saving and Pensions boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.
Click on this link for a Statement of Accounts that can be posted on the DebtFree Wannabe board: https://lemonfool.co.uk/financecalculators/soa.php
Check your state pension on: Check your State Pension forecast - GOV.UK
"Never retract, never explain, never apologise; get things done and let them howl.” Nellie McClung
⭐️🏅😇🏅🏅🏅🏅🏅🏅1 -
Aside from what's been mentioned already - are you able to earn at least a small amount of self-employed income (even just doing some surveys for example) and pay voluntary NI contributions so you build up some state pension entitlement at least? That could likely be very helpful in your situation.
0 -
reconsidering things….you say you have suffered from anxiety and depression from an early age. And also that you can't get benefits because of your wife's income. Have you considered applying for PIP? That at least would give you something to contribute to the household finances. I don't if it is considered income per se or whether it would cover you for NI but if nothing else it would give you the money to contribute to "buy your stamps" so that you would get something when you reach state pension age.
I’m a Forum Ambassador and I support the Forum Team on Debt Free Wannabe, Old Style Money Saving and Pensions boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.
Click on this link for a Statement of Accounts that can be posted on the DebtFree Wannabe board: https://lemonfool.co.uk/financecalculators/soa.php
Check your state pension on: Check your State Pension forecast - GOV.UK
"Never retract, never explain, never apologise; get things done and let them howl.” Nellie McClung
⭐️🏅😇🏅🏅🏅🏅🏅🏅0 -
Wow didn't expect so many replies so quickly
So basically my wife works full time and pays into a work pension. If I'm honest I don't know how much she pays in currently.
Ive always suffered from anxiety and depression. Started when I was about 18. Went in and out of a few jobs when I was.younger. nothing lasting more then 3 months as I got really unwell mentally. I used to be able to claim a benefit but when Iet my now wife and we moved in together 13 years ago now I was no longer able to claim anything and was dependant on her.
After seeing a therapist for a long period of time I made the decision to just accept I probably wasn't going to work and by doing that hopefully I would live. Slightly less stressed life. Don't get me wrong it will always bug me how I have not managed to work and provide like my wife but from a health point of view it felt I had no option.
We have been lucky enough to save money even with my wife's low wage and she got made redundant and we paid our mortgage off. My wife cannot have children unfortunately but this ha also helped us financially I guess.
The money I came into is in a savings account in my name. I currently earn about 7k interest yearly which is fine for me as I won't pay tax on that.
We don't have a ISA
I'm just wondering if we carry on doing this or should we look to put into a private pension.
I have very little contact with the benefits people after they stopped my benefit at the time 13 years ago. However I think they may still be paying my national insurance contributions I would need to double check this.
Im sure what the 150k we have is currently fo . I suppose it gives us a option to move in the future but then it's gone.
Im assuming I would get pension credits when I hit the right age again it won't be much which is why I'm seeking some advice really
Thank you
0 -
Just to update my NI is being covered via credits I looked into this on the gov site which showed all my previous year's are full which suggests I'll receive state pension if my current situation is unchanged
1











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards