We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
How safe is my pension?
Comments
-
Why do you have a SIPP if you have all these concerns about them?
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
If you google Client Assets Sourcebook (CASS) audit, it may ease your mind a little. I haven't actually done anything like it myself since back in the days of paper share certificates though so don't ask me for details!
1 -
Let us suppose that someone like AJ Bell did go under completely and all the money was gone, leaving ordinary (albeit well-off) investors facing the loss of 6-figures or millions, the FSCS having confirmed that they nominally only cover £85,000. Let's leave aside that a theft of this magnitude is, for all intents and purposes, logistically impossible. This would be an unprecedented financial scandal; every previous major scandal has involved investors who were overexposed to a single company (Equitable Life, Allied Steel, Madoff). There has never, in financial history, been a case where investors holding diversified portfolios via mainstream providers providing returns in line with the global market suddenly found their investments had vanished. (Unsurprisingly as it is logistically impossible.)
You're probably alluding to it with the "logistically impossible" comment, but it's worth pointing out that AJ Bell have something in the region of £9 billion in assets under management. If the directors did steal it all, what would they do with it? You can't spend £9 billion on cocaine, fast cars, loose women and round the world cruises. Well, I would gladly volunteer to test this theory experimentally, but in practice most of the money would still be sitting in my bank account when the fraud was uncovered (assuming I could even find a bank willing to take £9 billion without asking where I'd got it), so it would easily be recovered and returned to it's rightful owners...
1 -
I had some P2P investments - some in a IFISA wrapper. I largely managed to escape any losses when it all came tumbling down.
However it has had no effect whatsoever on my confidence in mainstream investment platforms, pensions etc.
It is a totally different world.
2 -
Who was the poster on here who was always extolling the virtues of P2P? They haven't been around for a while.
0 -
Yes, this. There is a good regulatory system n place where institutions have to demonstrate they are reconciling what they say they are holding for their clients, to the official registers for those assets.
It's certainly not perfect in that it will typically be looking at an aggregate level of holdings for the same stock/fund/ETF rather than what is in your own account specifically, but it does mean that it would be very difficult for a regulated institution to create a phantom book of assets and just siphon off your cash.
Unlike Marcon, I don't think it's unreasonable to want to get a bit more assurance than simply taking the FCA Authorised/Regulated badge as being a panacea, but then I've seen (from the inside) the effects of when regulation fails!0 -
jamesd
Hasn't been on here for nearly three years.
2 -
Unlike Marcon, I don't think it's unreasonable to want to get a bit more assurance than simply taking the FCA Authorised/Regulated badge as being a panacea, but then I've seen (from the inside) the effects of when regulation fails!
….as have I. I'm astonished that you think I've taken any such view re the FCA.
Look again: I didn't say anything like that. Given earlier posts in this thread (quoted below for ease of reference), I merely asked why OP has chosen to have a SIPP rather than a non-SIPP personal pension.
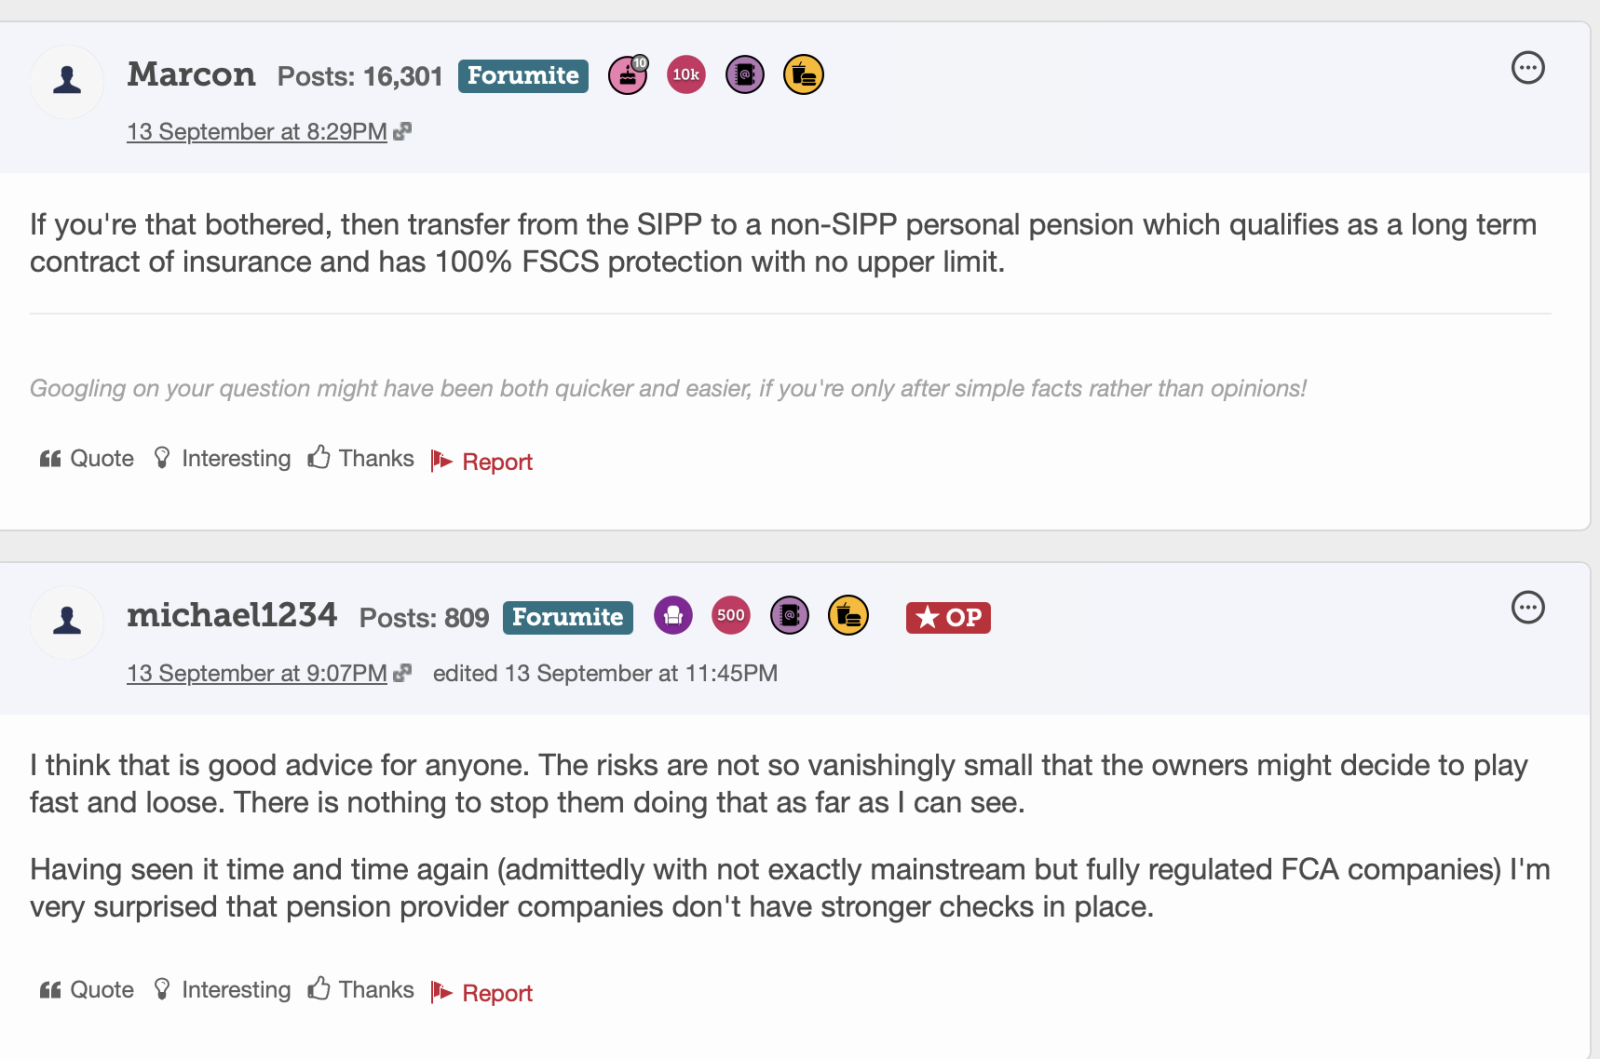 Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0
-
I think you might be looking for the wrong bad actors. A bigger and higher probability risk is probably an AI facilitated cyber-security breach. That's likely to be what keeps Risk and Compliance teams busy.
0 -
I'm not really convinced that whether it's a SIPP or non SIPP really makes much difference to the question about whether the manager could make off with your money (yes, sure, insured funds etc etc but ultimately fraud is fraud and if the money isn't invested there at all, it's all the same thing)
But fair enough, it read that way to me, but if that wasn't your point then I completely accept that!0











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards