We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Mortgage Broker





Is it worth getting a mortgage broker? I dont forsee any difficulty getting a mortgage base on my finances and the amount im looking to borrow. Not sure if it would be quicker for me going directly to the lender or getting a broker involved. In the past ive always gone direct to lender but wondering now whether a broker can access any deals or offers I cant?
Comments
-
I think most products are the same whether you go direct or via a broker. There might be some differences, but unlikely if you are mainstream.
Its more about whether you want someone to do the leg work for you and take the headache away or not really.
I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.2 -
I didn't use a broker, so I cannot really answer your question.
I compared the best mortgages using this link. I chose a 10-year fixed mortgage 9 years ago, which with the high rates of today, was a good choice.
https://www.moneysavingexpert.com/mortgages/best-buys/home-purchase/results?mortgageChannel=HomePurchase&repaymentMethod=Repayment&addFeesToBalance=false&requiredTermYears=25&propertyValue=400000&depositAmount=170000&sortResultsBy=MonthlyPayment&firstTimeBuyer=false&borrowMore=false&onlyShowWithNoUpfrontFees=false
1 -
Erm… Im not sure about that.
You would have missed all of the ultra low rates and paid a premium for the 10 year deal as there were only a couple of lenders offering them. Im 99% sure you would have been better doing 2 x 5 year fixed rates or even a 5 year then a 10 year.
I did a few 2 year fixes at 1.x% and then 4 years ago switched to a 5 year fix at 2.5%.
I remember doing a 10 year fix for a couple 11 years ago - it was 3.99%. I tried to get them to change to a 5 year fix as everything suggested rates would continue to come down or at least stay steady and 10 year fixes came at a premium. They came out of their deal last year - they missed all of the ultra low rates and came out of their deal just as rates were back to 4%ish.
But in fairness it is all in hindsight, nobody knew what the future held - ok we knew about Brexit but we had no idea about covid/lockdowns, a mini budget, 2 wars etc.
I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.2 -
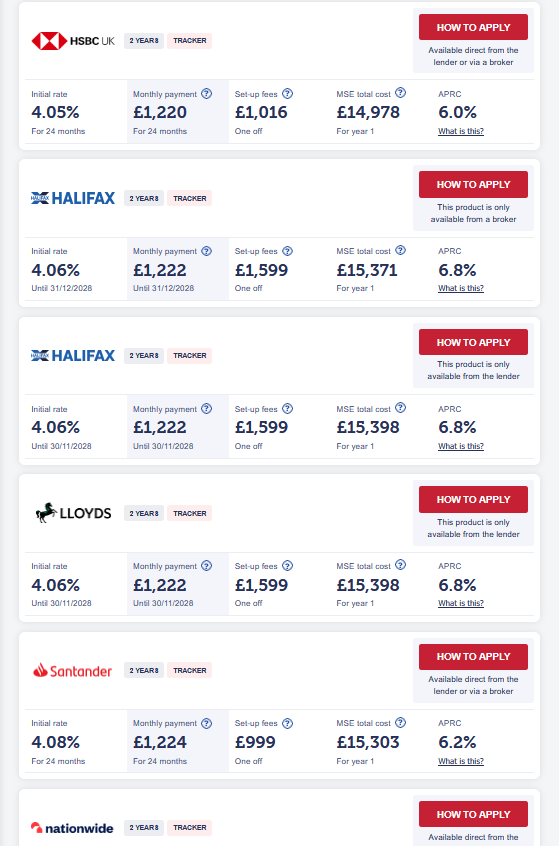
My 10 year fix was 2.69% compare that to the cheapest that you can get now and you will be paying 3+% more, rates have been coming down since 2024, but are now more likely to go up.
 0
-
Thats compared to now.
After you took your mortgage out, there were rates as low as 0.99% (although they did come with large fees so only suitable for larger mortgages).
During your 9 years, my mortgage rates were 1.24%, 1.45% and now I am on 2.5% and my deal ends the same time as yours more or less. Depending on the size of your mortgage, arguably you would have saved by taking a little more risk. But then on the flip side, you might have got caught short and been hit with the higher rates if they had not fallen right.
Its all hindsight, nobody could have known what was coming. I suppose 2.79% wasnt massively more and you didnt have to worry about applying etc.
I am a Mortgage AdviserYou should note that this site doesn't check my status as a mortgage adviser, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.0 -
Fixing for 10 years means no more setup fees and it means security; base rates were above 5% for over 12 months in 2023. Imagine getting various fixes and having to fix in 2022 at 4% or fixing in 2023 at 6%
Rates are now said to be going up from 4%, but no one can predict further than 2 years ahead, oil prices, climate change, Trump and Putin; the world is very unstable.
0 -
- Speed - A broker will usually be much quicker and easier than going direct.
- Active - A broker, in principle, has a better idea of what they are doing as they understand the market rather than being trained on what an employing lender tells them
- Responsiveness - A broker, in this volatile market, will alert you if rates and options change during the process
I am a Mortgage Broker
You should note that this site doesn't check my status as a Mortgage Broker, so you need to take my word for it. This signature is here as I follow MSE's Mortgage Adviser Code of Conduct. Any posts on here are for information and discussion purposes only and shouldn't be seen as financial advice.1






Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards