We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
High income child benefit charge tax question




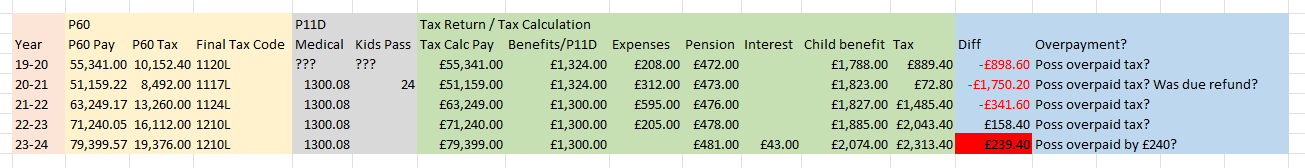
I’ve been claiming Child Benefit to collect National Insurance credits. A few years ago, my wife’s salary went over the threshold for the High-Income Child Benefit Charge. We registered her for Self-Assessment and began paying the charge each year. Her salary has since increased to the point where we now repay the full amount of Child Benefit.
My concern is that we are paying more tax through Self-Assessment than the Child Benefit we received. I contacted HMRC to query this and to ask whether the repayment could be collected through her tax code instead, so we could stop filing Self-Assessment returns. I’m worried she is being double‑charged tax on her P11D benefits. My accountant warned this might be what’s happening when I queried it with him, but HMRC insist it isn’t the case. They confirmed her P11D benefits are already included in her tax code, but also say they must still be included on the Self-Assessment return.
So, my questions are:
- Why did we have to pay nearly £240 more in tax than the Child Benefit we received in the 2023–24 tax year?
- If we hadn’t claimed Child Benefit and hadn’t filed a Self Assessment return, would we have avoided this extra tax?
- If we stop claiming Child Benefit and deregister from Self Assessment, what happens to this additional £240? HMRC say we would still receive a bill for it — but how? We never received such bills previously, and her colleagues on similar salaries with the same benefits don’t receive them.
Thanks for your help in advance.
Comments
-
The tax code is just an attempt to get the tax right in year. The final tax calculation ignores it.
The tax code looks too high, so it looks like it's not been set correctly for some reason. Why did it change in 22-23? The previous tax code looks more accurate. It looks like she isn't being taxed enough before even considering child ben tax.
What is the pension column? Is that pension conts into a workplace pension? If so before or after tax? Or into a personal pension eg SIPP, gross or net?
Are the benefits payrolled - ie included in the P60 figure? If that is the case they shouldn't issue a P11D. Check this if you're worried about double taxation.
1 -
subject to the treatment of the "pension" figure £2,313 tax payable looks to be in the right ballpark
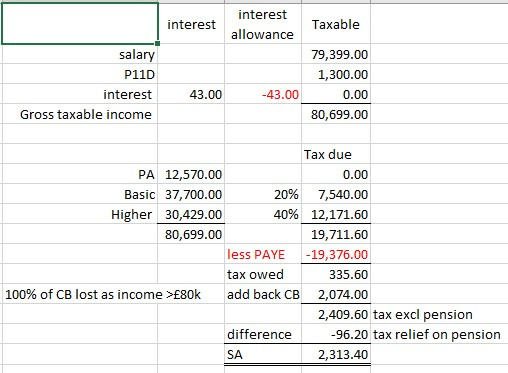
if the pension is indeed £481 then it gets higher rate tax relief of an additional 20% (to bring it up to 40% assuming 20% already given at source). So £481 x 20% = 96.20
re the tax code, it is wrong and you are underpaying tax through PAYE because the code has failed to reflect the full P11D value. That is why you would get a "bill" anyway outside of SA because 335.60 - 96.40 = 239.40 tax still owed irrespective of CB
for illustration purposes only, given PAYE should be calculated on a monthly basis without the rounding inherent to a lump sum annual calculation, your PAYE is based on the fact your tax code has reduced your free pay by only 470 from 12,570 to 12,100 instead of the full P11D amount. Hence the PAYE of 19,376 (19,379.60 annualised approx) is lower than it should be leaving you with the net underpayment irrespective of CB.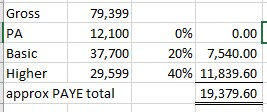 2
-
You don’t have to claim the payment of Child Benefit to get the NI State Pension credit.
1 -
So, to answer your questions:
Why did we have to pay nearly £240 more in tax than the Child Benefit we received in the 2023–24 tax year?
Because the tax code was too generous and your wife didn't pay enough PAYE tax during the year.
If we hadn’t claimed Child Benefit and hadn’t filed a Self Assessment return, would we have avoided this extra tax?
No. The tax would still be due.
If we stop claiming Child Benefit and deregister from Self Assessment, what happens to this additional £240? HMRC say we would still receive a bill for it — but how?
It's possible that HMRC would adjust her tax code to reclaim it in future years. Or they might send you a tax demand. But don't think that you can necessarily cease Self Assessment simply by stopping your Child Benefit claim; HMRC doesn't work like that.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.1 -
Agree. There is an option to claim the credits but not the payment which would make sense in this case.
1 -
Something to consider is increasing pension contributions as you'd get over 50% tax relief
1 -
Thank you, everyone. I didn’t realise I could claim Child Benefit without receiving the payments. It’s only in the last two years that we began paying back more than we received. We’ve now registered to have the charge collected through my wife’s tax code.
I’ve also just learned that National Insurance credits only continue until your youngest child turns 12, and my youngest is now 11½, so I’ll need to make new arrangements soon. His birthday is in January, so does anyone know when will the credits stop?
My wife receives an annual bonus of around £10,000. She can choose to pay the entire amount into her workplace pension, but it must be all or nothing. Would you recommend doing this? Based on the 2023–24 figures, how much would she need to divert into her pension to avoid higher‑rate tax?
Thank you again.
0 -
Just to clarify, you won't be 'paying back more than you received' - as discussed above if there is more tax to be paid back it will be for other reasons.
I believe the credits will stop on the week after your youngest turns 12.
With regards to making new arrangements, have you checked your state pension forecast to see what position you are in and how many more years you need ? It's not necessary to fill every year to qualify for the new state pension
1 -
Thanks. From 1995–96 up to and including 2025–26 I have 24 full qualifying years, and 7 years that aren’t full. I’m currently 47.
After discussing it with my wife, she’s going to divert her bonus into her pension, and then increase her regular contributions. She also plans to merge her small private pension into her workplace pension.
I can see I’ve been earning 52 or 53 National Insurance credits each year, depending on the year. So I assume I’ll need to start buying credits from the week our child turns 12 to make the year count. Before we had children, I used to pay myself enough salary to trigger employee NI contributions.
0 -
You need enough qualifying years by the time you turn 67, and the number may not be 35 years. You have 20 years to build about 10 years of contributions. Might you return to work when child reaches 18?
0





Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards