We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Help with defaulting debts



Comments
-
hello, I am coming back here after posting a thread last year when my 0% cc deals were coming to an end. Unfortunately my debts have just got worse and with a mortgage increase of £300 from November I know I need to enter into a DMP.
When I have submitted my budget on Stepchange it is saying I only have enough for £63 pm split between my 4 creditors (all credit cards, £24k) and that it would take me 29 years to pay back. This has terrified me as I will be 70 by then! I know I will be able to up payments when my children grow up, but is this really something that is going to be with me for the rest of my life?
I have not stopped my minimum payments yet but intend to for Sept so I can start building my EF.
Thank you for reading, this thread has been so informative for me at a really difficult time.
1 -
hello, this is just a follow up on my last post as I haven’t had any replies so am wondering if I need to start my own diary/thread instead?
I’m pretty new to posting on forums although I have been lurking here for a good while.I also have another question - two of my CCs are with Natwest and I also have a mortgage with them. I’ve just locked in to my next fixed with them for 5 years - completed it quickly online and it was accepted no probs. That will start in December once my current fixed ends.
My question is about defaulting on the two NatWest CCs - will that impact on my mortgage with them?
Like many other posters here I am really scared about doing this, so would be so grateful of any advice. Thanks again for reading
1 -
Hi,
You posted in the DMP support thread, which to be honest, does not see as much traffic as it used to do as people are managing their arrangements just fine, so I have moved your post to a new thread in the main DFW forum, where your post will be seen.
Secured debts and unsecured debts are like chalk and cheese, with a mortgage, the lender has the security of a charge over your property, so if you don`t pay, they can in theory sell the house to recover the debt.
With unsecured debts they don`t really have that option, best they can do most of the time is a CCJ to repay what you owe, basically they are treated very differently, and what you do with one, will not reflect on the other.
And in answer to your first posted question, lots of DMP`s start out over a much longer period that you would like, but there are ways to reduce the time you are in debt, one of those ways is by full and final settlement.
Later in the process, most of your debts will likely be sold, and bought up by companies that pay as little as 10% of their face value for them, there should be opportunities to settle for much less than is owed, which is why we stress the importance of a settlement fund.
You can also submit affordability complaints, and do CCA requests.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter1 -
My question is about defaulting on the two NatWest CCs - will that impact on my mortgage with them?
Like many other posters here I am really scared about doing this, so would be so grateful of any advice. Thanks again for reading
The difference between secured debts (e.g. a mortgage) and unsecured debts (e.g. a credit card) is very significant - regardless of whether they are with the same organisation. Secured and unsecured debts are treated very differently, have different consequences, and someone assisting you with your debts would in all likelihood advise you to prioritise secured debts for repayment over unsecured debts.
You may want to seek advice on what to prioritise and how to prioritise (or indeed on what offers to make to unsecured creditors). As noted by others, unsecured debts are frequently traded between various companies who buy these debts for pennies in the pound - they buy them cheaply because it is frequently difficult and costly for such companies to get any sort of payment/settlement by debtors because their leverage is limited.
Not paying a credit card may ultimately lead to a county court judgment (and adversely impact your credit rating for future borrowing) but it will not directly impact your mortgage as these are separate debts under separate contracts - you may also find that despite being under the same organisation (NatWest) that the different loans are actually with different companies under the NatWest umbrella.
1 -
Natwest does not make any affordability checks or credit checks if you just want a new mortgage fix, and they are very clear about this on their website
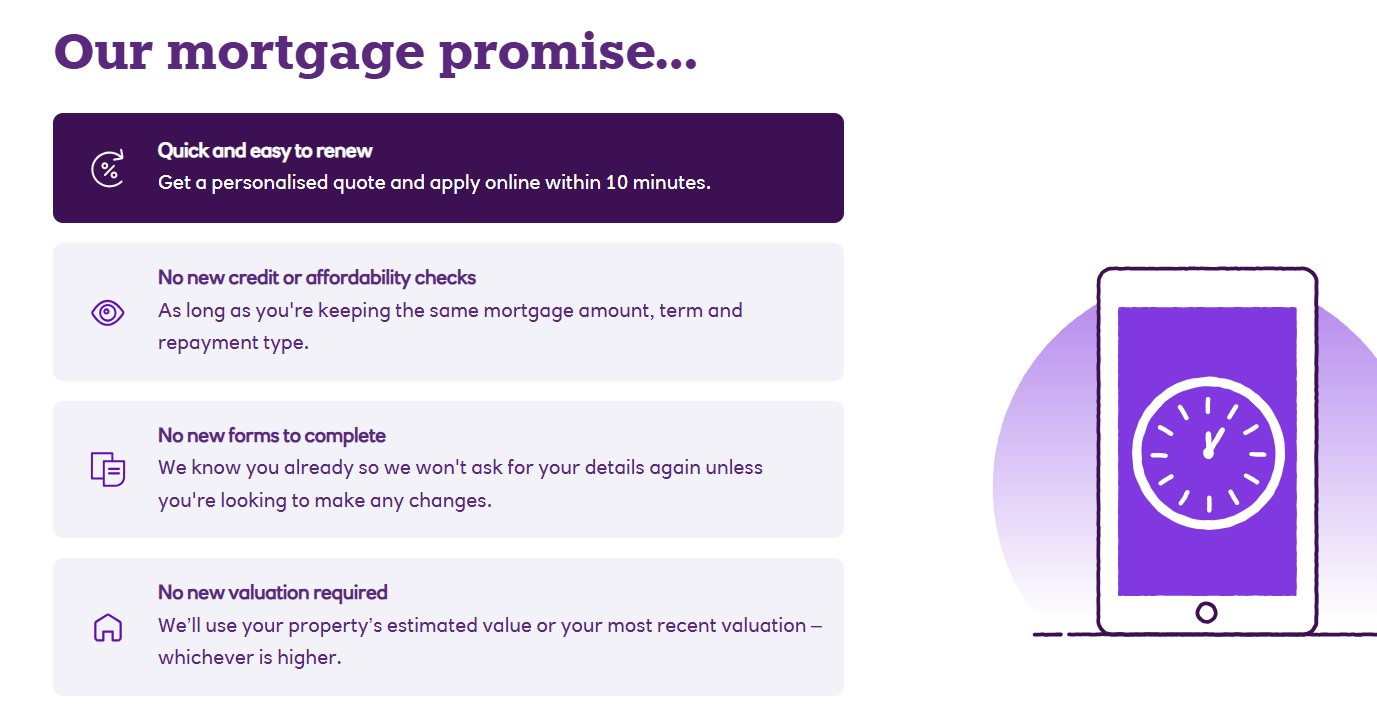
The same will apply if you have made complaints about your Natwest credit cards. They will not even notice these.
1 -
As explained, your mortgage will not be affected.
But you need to ensure that your income is paid into an account that is no associated with any banking group with whom you have any debt.
If there's any association, you need a new account, Monzo, Starling or any basic account for which credit checks are not made. Then get your income paid in and essential DDs moved manually. Do not use the Switch mechanism as your creditors can re-establish cancelled DDs if you use it.
If you've have not made a mistake, you've made nothing1









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards