We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Pension overwhelmed





I am 56 hoping to retire at 60, very big chance of redundancy then if not year earlier. This would be 95k payout and my plan would be to take the 30k tax free and put balance into pension. I know not a guarantee but if it happens this is plan.
I have one final salary which offers 11500 per year with tax free £75k which is how I plan to take it otherwise taxed if I take 14k annually which is other option. Total pot is £380k.
I have a current 5k pension as crystallised pension with employer they pay 9% and as off next month I will pay additional £350 which they will match, I earn 62k nearer 70k after tax with bonus.
I have 2 crystallised pension pots totalling 125k which I have no intention of touching until I am no longer earning.
I save £200 per month in share save and 20k savings but I was thinking of using 10k of this for debt.
mortgage free and wife has small civil service pension of about 6k both still working.
I still have one loan to pay that will finish in couple of years but nothing else am I on track to retire at 60 but maybe with very part time job so have something to do.
Advice so far has been very mixed and I just wanted to know if I was on target for both of us to retire on this at 60 with small part time jobs around 1k each, my wife would continue in her job and still build her civil service pension just reduce hours more
thank you
Comments
-
I am 56 hoping to retire at 60, very big chance of redundancy then if not year earlier. This would be 95k payout and my plan would be to take the 30k tax free and put balance into pension. I know not a guarantee but if it happens this is plan.
I have one final salary which offers 11500 per year with tax free £75k which is how I plan to take it otherwise taxed if I take 14k annually which is other option. Total pot is £380k.
I have a current 5k pension as crystallised pension with employer they pay 9% and as off next month I will pay additional £350 which they will match, I earn 62k nearer 70k after tax with bonus.I have 2 crystallised pension pots totalling 125k which I have no intention of touching until I am no longer earning.
I save £200 per month in share save and 20k savings but I was thinking of using 10k of this for debt.
mortgage free and wife has small civil service pension of about 6k both still working.
I still have one loan to pay that will finish in couple of years but nothing else am I on track to retire at 60 but maybe with very part time job so have something to do.
Advice so far has been very mixed and I just wanted to know if I was on target for both of us to retire on this at 60 with small part time jobs around 1k each, my wife would continue in her job and still build her civil service pension just reduce hours more
thank you0 -
Did you mean this to appear on the forum for mobile phones?
0 -
no how do I move this 🙈
0 -
You've said a lot about your likely incomings, but nothing on your likely outgoings?
How do you expect to live in your retirement?
It sounds like you may currently have possible income of at least £22k per annum, not including the redundancy (plus the state pension when it comes online), assuming your wife only has the small civil serve pension of £6k. Combining your private and state pensions puts you and your wife in the 'moderate category' according to Pensions UK: (though these guidelines are fiercely debated on this forum, as with all things, YMMV). Of course there would also be a gap between your planned retirement date and the SP, and it looks like there's inadequate savings to bridge the gap, so it means either living on less for a few years, releasing equity or working longer.
For some this would be plenty, for others it's not enough - it all depends on your expectations from retirement.
Know what you don't2 -
Without knowing your required income in retirement, nobody can tell you if you're on target or not, as we don't know the target.
0 -
my outgoing in a few years will be normal household bills/food around about 1200 as will have no debt. I plan to top up 11k pension with 2 part time jobs 1k each - 3k total. Also use the 75 or 105k dependent on redundancy to top up each month so income would be the same as just now.
1 -
I have one final salary which offers 11500 per year with tax free £75k
which is how I plan to take it otherwise taxed if I take 14k annually
which is other option. Total pot is £380k.Just in case any one else reads - there is no "pot" with a final salary pension, just a promise of a certain income (withor without TFLS).
The pension co may offer a CETV amount to get you off their books, but transferring out isn't a good idea and the advice is expensive.
0 -
I am 56 hoping to retire at 60, very big chance of redundancy then if not year earlier. This would be 95k payout and my plan would be to take the 30k tax free and put balance into pension. I know not a guarantee but if it happens this is plan.
Have you factored in the fact that the Annual Allowance (including tax relief on any personal contributions, plus any employer contributions) is £60K per annum and there's no suggestion that will increase? Unless you have carry forward available and your employer is willing to make most of that 'balance' an employer contribution to your pension, you won't get tax relief on all of it. If the employer won't do that, then you are limited to making personal contributions no greater than your earned income in the year in which you make such contributions.
https://www.moneyhelper.org.uk/en/pensions-and-retirement/tax-and-pensions/carry-forward
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
I have one final salary which offers 11500 per year with tax free £75k ... Total pot is £380k.
OP are you sure about this?
£11500pa plus £75k isn't a particularly generous offer for a pension with a CETV of £380k. You'd potentially get more on the open annuity market.
£380k would get a 60yo a £95k TFLS and a single life RPI annuity of £13.6k.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
£380k would get a 60yo a £95k TFLS and a single life RPI annuity of £13.6k.
We don't know how long ago that CETV was quoted. In any case, you're not comparing like with like. The annuity rate you are looking at is:
- for someone currently aged 60
- for a single life annuity. OP's final salary pension provides a spouse's pension (and OP has said they have a wife, so that might be important to them)
- does not have a guarantee period, whereas the final salary scheme is likely to have one (at least five years if it's a fairly typical scheme).
OP is only 56, so their final salary pension will continue to revalue between now and the time they access the benefits - potentially another 4 years of increasing in value. It's certainly gone up since they posted about it in December 2024:
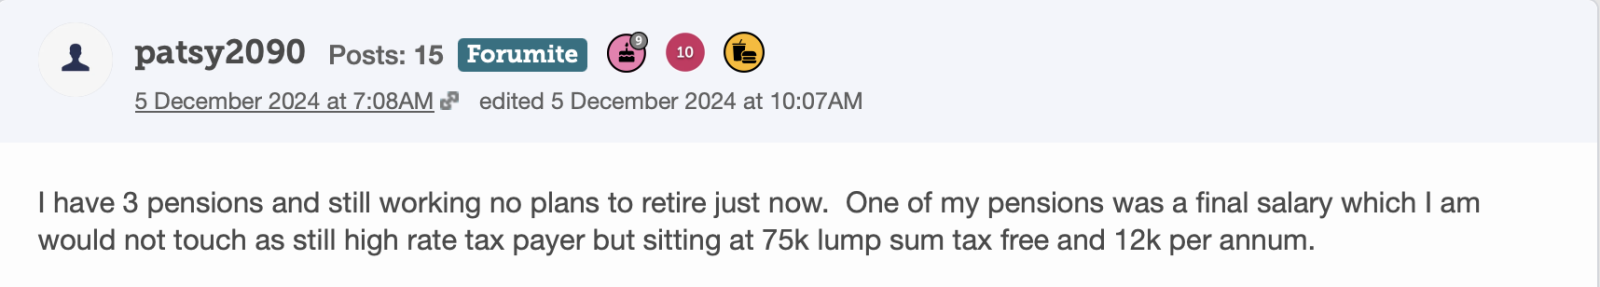
Without much fuller details of the final salary scheme and its benefits, it's not possible to draw any meaningful comparisons with annuities which might or might not be available in the future - and a CETV which could have gone either up or down in the meantime!
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0










Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards