We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Teachers pensions and divorce


Hi,
I have gone through an amicable divorce and we have decided to split our pensions 50:50. My ex husband's providers have followed the pension order without any charge but Teacher's pensions have been a nightmare and it looks like they want to charge us over £3000 for following the court order which is disgusting. If I opt to take it off my benefits at retirement then they said it will follow inflation rates so I might end up with barely anything left. I was just wondering if anyone has any experience of this as it seems grossly unfair, especially as a single parent now?
Thanks
Comments
-
If I opt to take it off my benefits at retirement then they said it will follow inflation rates so I might end up with barely anything left
It could only be a higher percentage of your pension at retirement than now if the growth in your fund(s) was below inflation, which shouldn't be a likely outcome if invested sensibly…
0 -
Given the generosity of teacher pensions it seems like a small price to pay.
0 -
My ex husband's providers have followed the pension order without any charge but Teacher's pensions have been a nightmare and it looks like they want to charge us over £3000 for following the court order which is disgusting.
This is going to be cold comfort, but that is well within the range typically charged where a defined benefit scheme is split between the member and their ex. It is complicated to implement, and there are also the ongoing administrative costs of maintaining member records for not just the member, but also the ex who becomes a 'Pension Credit Member' with TPS benefits in their own name.
I suspect your ex has a defined contribution pension arrangement, which is much more straightforward to deal with.
If I opt to take it off my benefits at retirement then they said it will follow inflation rates so I might end up with barely anything left.
I think you probably added the latter part of the sentence, since it's unlikely in the extreme that TPS would vouchsafe such a misleading remark. You've referred in your post to charging 'us' (not just you) - make sure that any agreement about who pays what is honoured if your ex is on the hook for some of the costs.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
Thank you for your comments. I have no problem paying a small admin fee but I just object to the amount they are quoting when other providers don't charge anything, it just seems like they have you over a barrel.
0 -
A majority of DB pension schemes charge the administrative fees btw.
0 -
A DC scheme divorce split is little more than taking the total fund valuation and applying the % allocation. On the other hand, a DB divorce calculation is on of the most complex, time consuming, - and therefore expensive - procedures. The amount quoted by TPS isn't excessive for the amount of work involved, especially when you consider that it includes the cost of setting up and maintaining the recipient's pension record for life.
0 -
I have no problem paying a small admin fee but I just object to the amount they are quoting when other providers don't charge anything, it just seems like they have you over a barrel.
I doubt there is a defined benefit scheme in the land which doesn't charge for dealing with a pension sharing order. Most can be expected to follow these charging guidelines, and as you will see, the TPS charge is well within them - and indeed, at the lower end of the scale for what is classed as an 'internal transfer':
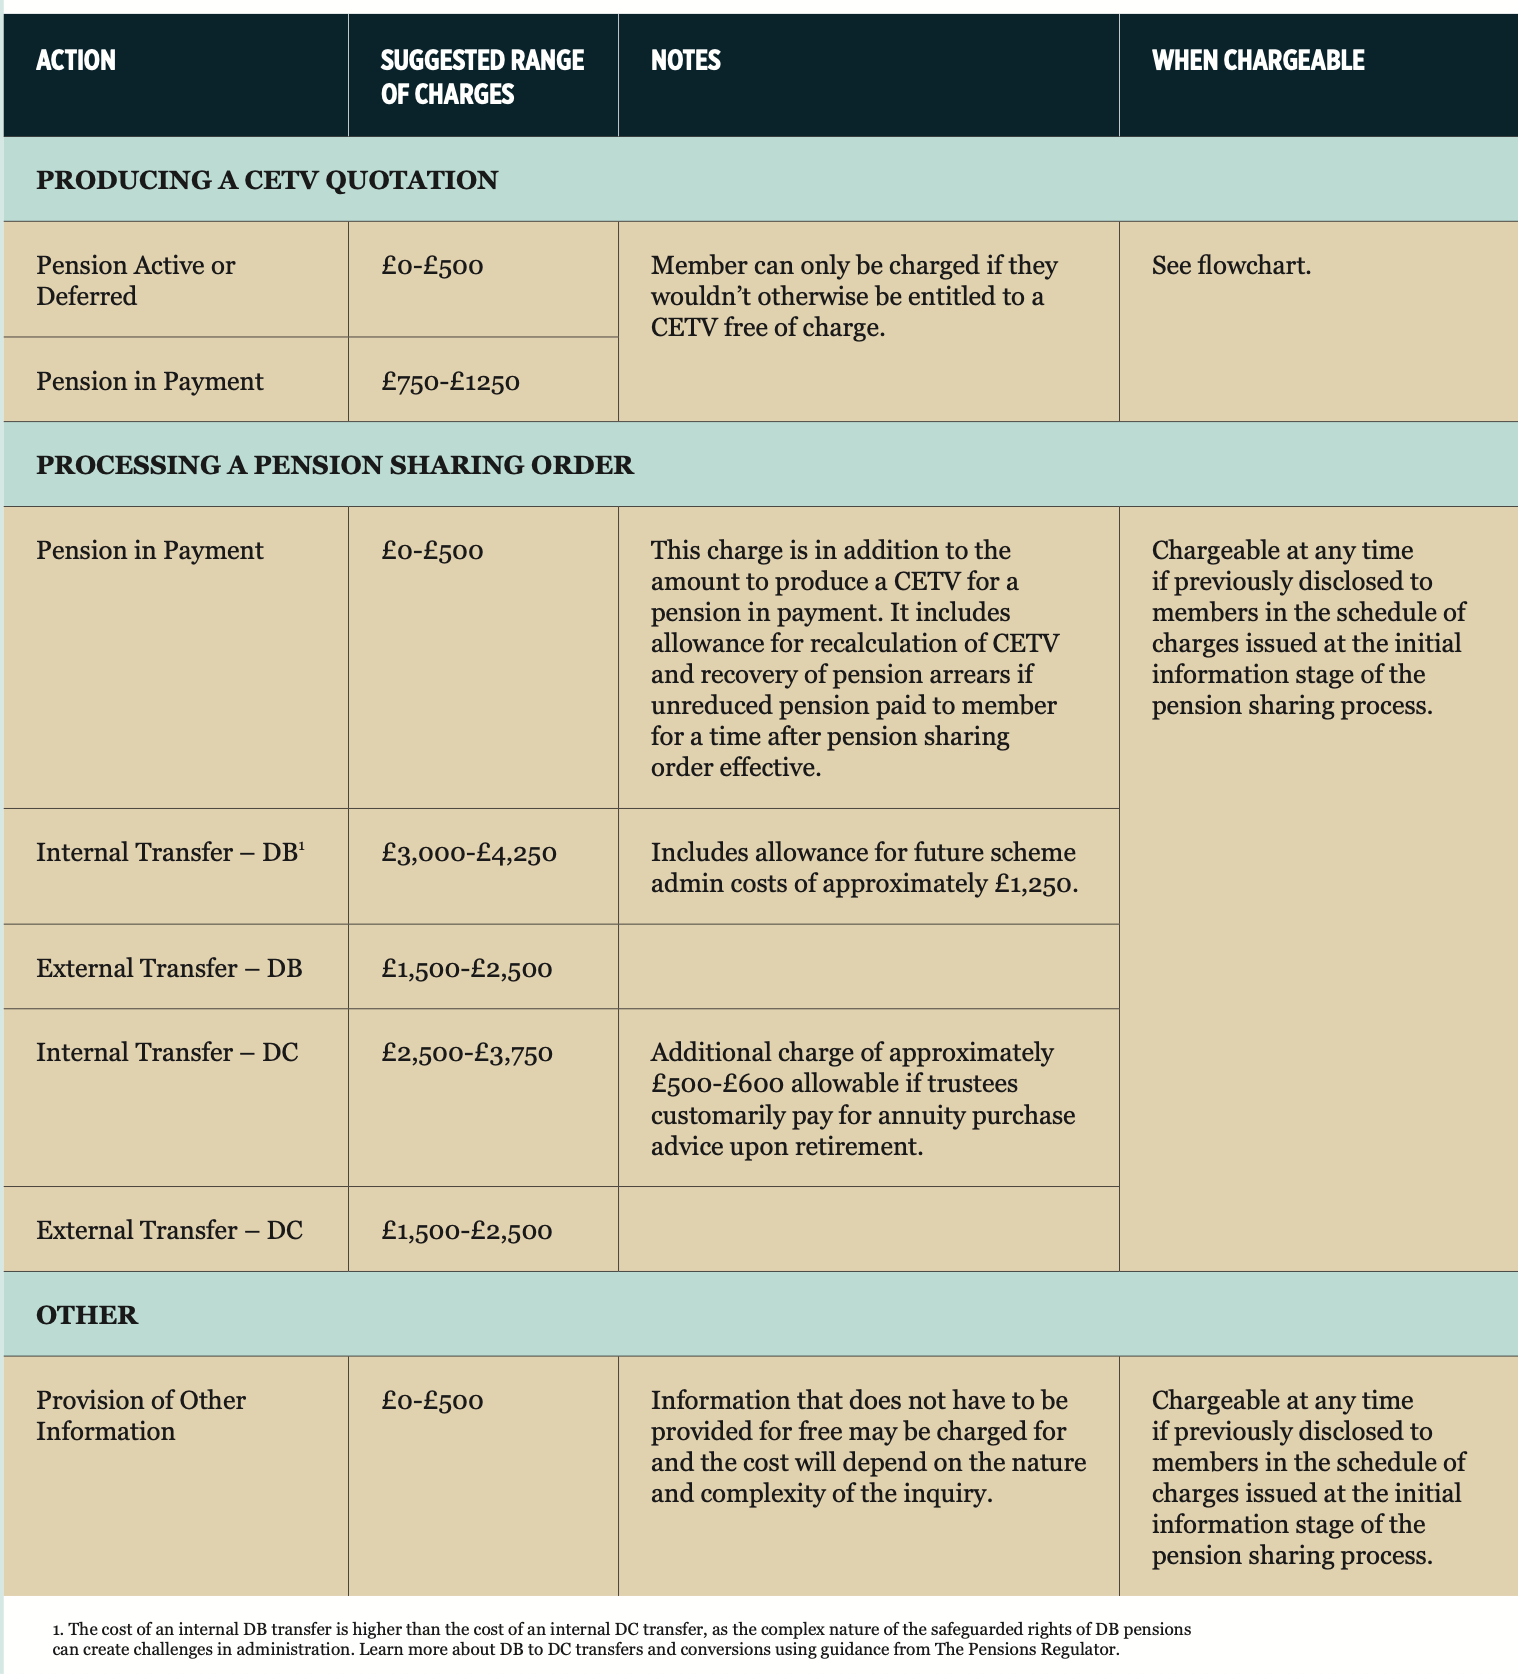
Source:
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!5 -
TPS is an unfunded defined benefit scheme, so there are no investment decisions to make in respect of the main scheme - only in respect of AVCs (if any) with the Prudential.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
OP - what exactly do you mean by 'taking it off my benefits at retirement? Do you by any chance mean not going ahead with the division now but, instead, giving your ex £X per month out of your eventual pension payments? Because, if that is the case, then let me count the ways that would end up being way more expensive than paying the admin fee now.......
1 -
The charge sounds reasonable to me.
Maybe you could find another way to divide the assets 50:50 without dividing the DB scheme.
0








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards