We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Flexi Drawdown v UFPLS
Comments
-
The first payment always has the code operated on a non cumulative basis, so only £1,048 allowances, not the full £12,570.
0 -
even in March at year end? thats mad.
0 -
That is how the PAYE tax system works, in the absence of a tax code being provided 1257LX must be used. That is why the small withdrawal is needed early in the first year to get things set up, once a code is allocated the normal x / 12ths of the allowance applies exactly the same as in any employed scenario.
Never associate with idiots on their own level, because, being an intelligent man, you'll try to deal with them on their level - and on their level they'll beat you every time.
Being hated by idiots is the price you pay for not being one of them.
Jean Cocteau 1889-1963
0 -
on the positive side that likely puts me back to drawing monthly not annually and FAD rather than UFPLS. So take the TFC whenever and a ‘annual taxable /12’ amount via regular FAD monthly from April
(Likely with a year in cash as a buffer for cashflow so the pension pa0 -
In my case I am entitled to a full state pension, which I have deferred for a few years so this will take up ALL of my personal tax allowance.
Therefore any money I take as draw down or UFPLS will have the 75% taxed at 20%.
When I start to take my ii pension they will not have a tax code for me, I will have to wait and see what happens.
However it was my understanding that ii should use BR or W1M1 tax code and apply this to the 75% which is taxable.
Regards Mike0 -
That is highly unlikely.
The first payment will have the emergency code applied (1257L) and the HMRC will no doubt then issue a K code (negative tax allowances) so the pension company can deduct basic rate tax and the tax due on the State Pension.
NB. Assuming you have put the State Pension into payment.
0 -
Just grabbed this from the HMRC web site, as you can see "1257L" is NOT an emergency tax code.
"1257L W1" or "1257L M1" would be. Is what you mean?
I have personally only ever seen a K suffix when a large benefit in kind (such as a company car) is takin into account.has a full break down, which includes BR which is what I would expect a pension company to use for one's first draw down or UFPLS.
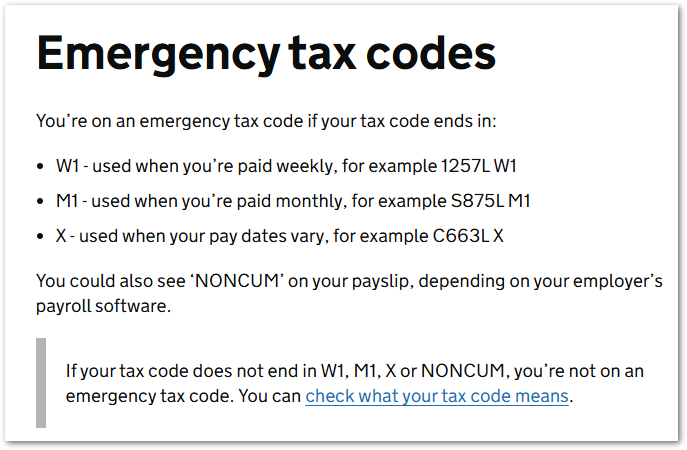 Regards Mike0
-
1257L definitely is the emergency tax code
W1 and M1 aren't part of the tax code, they show that the code is being operated on a non cumulative basis.
K codes are going to be ever more common now for a lot of people given the combination of frozen Personal Allowance and triple lock on the State Pension.
0 -
The standard UK tax code is 1257L. This means you have a tax-free Personal Allowance of £12,570 for the year. The number (1257) is your annual allowance divided by 10, and the letter "L" indicates you are entitled to the standard UK tax-free allowance.
This is NOT an emergency tax code.
Regards Mike1 -
HMRC wouldn't agree with you though.
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.7K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards