We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Class 3 voluntary NI contributions: why was the 6th back year calculated differently?


Hello everyone!
I recently filled all the gaps in my National Insurance record through voluntary Class 3 contributions. I applied before April 2025, received the calculation, paid the required amounts within the deadlines, and my record is now fully up to date.
There is one technical point I am still curious about and would like to understand for future reference.
As we know, contributions can generally be paid retrospectively for up to six years. In my case, the most recent five years were calculated using the ordinary rates applicable to each respective year (£907.40, £824.20, £800.80, £795.60). However, the sixth year back (2019/20) was calculated using the fixed rate provided under the pension reform transitional arrangements (£824.20), rather than the ordinary rate for that year.
I am not questioning the calculation and have no issue with it. I would simply like to understand the legal or regulatory basis for treating the sixth year differently. Does anyone know the relevant legislation, regulation, or official guidance that explains this?
Was this the normal treatment for everyone who applied before April 2025? What do you think is the rationale behind this approach?
Many thanks in advance for any insights.
Comments
-
You effectively paid in 24-25 which puts 19-20 at £824.20. There was no "fixed transitional rate", there was though a special rate if paid prior to April 2019. Years stay at the in year price until 2 years after the end of the year. They then increase to the current year price. The 2 year rule was paused for the extension to the April 23 deadline but 19-20 had already increased to the 22-23 rate in April 22.
Never associate with idiots on their own level, because, being an intelligent man, you'll try to deal with them on their level - and on their level they'll beat you every time.
Being hated by idiots is the price you pay for not being one of them.
Jean Cocteau 1889-1963
1 -
Thank you so much for the reply. I finally feel like I’ve grasped something I’ve been reflecting on for weeks without quite catching the point.
Based on your explanation, I understand that the '2-year rule' (Reg 48) was suspended for the years covered by the April 2025 extension, allowing me to pay historical rates for 2020-2023.
My understanding of the rate application is now as follows (applied to a “paying in 2025” case):
- 2006/2007 to 2019/2020 (£824.20): These years fall outside the 2-year window (Reg 48 expired before the 2023 extension), so they were re-priced to the 2022/23 standard rate. And I was able to pay these thanks to the 17+2 year extension window provided by the reform.
- 2020/2021 (£795.60), 2021/2022 (£800.80), and 2022/2023 (£824.20): These years were effectively 'held' at their historical rates because the 2023 extension suspended the standard Reg 48 re-pricing mechanism. Right? They did not jump to the current year's higher rates because of this policy intervention.
- 2023/2024 and 2024/2025 (£907.40): These reflect the current standard rates, as they fall within the normal two-year cycle at the time of my application.
Do you think my understanding is correct and accurate, or have I missed any nuances?
0 - 2006/2007 to 2019/2020 (£824.20): These years fall outside the 2-year window (Reg 48 expired before the 2023 extension), so they were re-priced to the 2022/23 standard rate. And I was able to pay these thanks to the 17+2 year extension window provided by the reform.
-
That is correct. For timeline purposes all years 06-07 to 16-17 were treated as 16-17, with a slight modification to the 06-07 to 09-10 and 10-11 to 15-16 rates, so increased to the current year price from April 2019.
(5) Notwithstanding section 13(6) of the Act, the amount of a Class 3 contribution payable under this regulation shall be—
(a)in respect of contribution years 2006-07 to 2009-10, the amount payable in relation to tax year 2012-13; or
(b)in respect of contribution years 2010-11 to 2015-16, the amount payable in the contribution year to which the payment relates.
(6) Paragraph (5) does not apply to a Class 3 contribution paid on or after 6th April 2019
Never associate with idiots on their own level, because, being an intelligent man, you'll try to deal with them on their level - and on their level they'll beat you every time.
Being hated by idiots is the price you pay for not being one of them.
Jean Cocteau 1889-1963
1 -
I created this small table/outline based on the information you provided and other sources. Once again, I’d like to take advantage of your kindness and precision to ask whether, in your opinion, it is technically complete and correct:
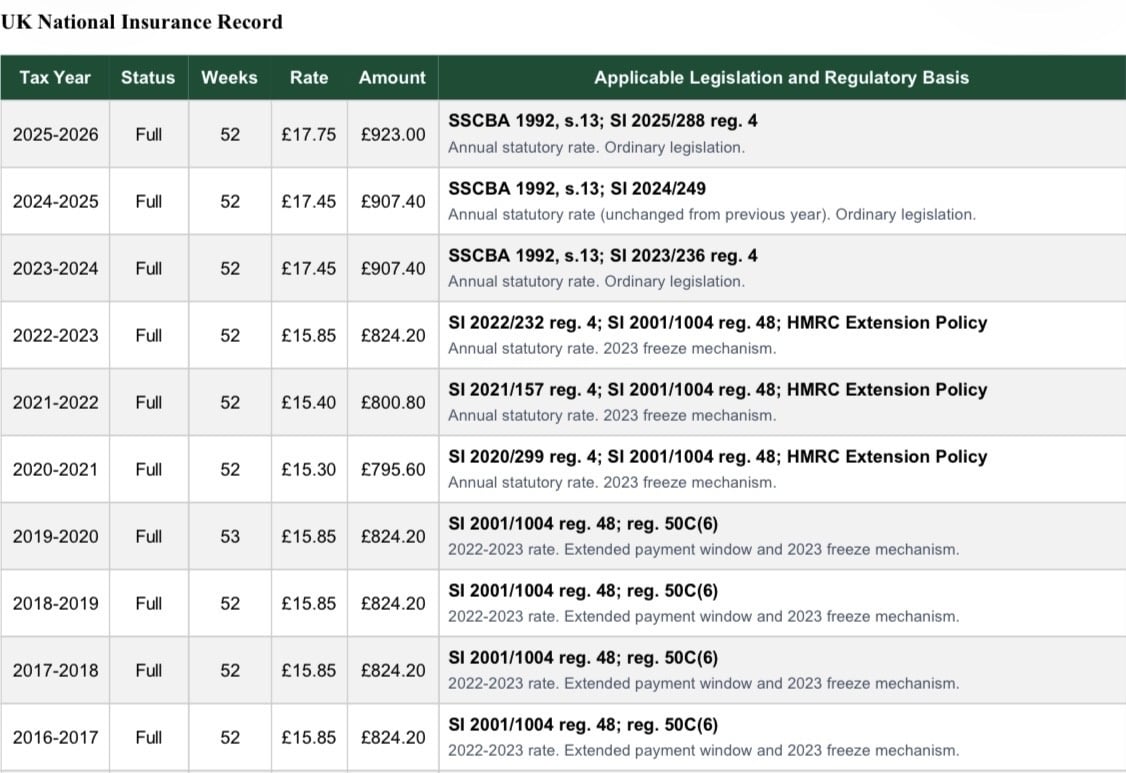
I often create this kind of table because I find it very useful even years later, especially for remembering details that might otherwise be forgotten..
Thank you very much!
0 -
Can you explain what the table is meant to show?
Are you tracking what you actually paid for those years, or what they would have cost to buy?
If the latter, at what date are you taking your snapshot? For example, today you could buy 2025-26 at the price you list but you can't buy 2016-17 no matter how much you offer.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.1 -
No, no, I just want to make myself a simple table showing what amounts I paid, under which rules, and in which years. That’s my fixed historical record. I was just wondering whether the references are correct and complete.
I’m sure that at some point in the future I’ll find myself wondering again (as I already have in the past) what the mechanism was and which rules applied to me at the time. And, of course, I won’t remember any of it. By keeping track of it now, I’ll have everything in one simple table whenever the question comes up again.
Going forward, the relevant reference will always be whatever the current pension and tax rules are, together with any later amendments, reforms, transitional arrangements, and so on. If you think about it, over the last twenty years there have been at least three significant reforms (the Pension Acts of 2007, 2011 and of course 2014, plus the recent tightening of the rules for voluntary Class 2 contributions). So I think it’s useful to keep a record of how those rules applied to my own circumstances (which is also the case for many others, btw).
My full table goes back quite a few years and also includes a mix of Class 1, etc. But I was mainly interested in the most recent period because, before posting on this forum, I wasn’t entirely clear on the technical reason why some of those contribution rates had been applied.
0





Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards