We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Teachers Pension Help



Hi, new starter in the TPS and very confused!
I am 45 and would like to retire at 65. I would like to contribute additional payments to enable me to do this with a reasonable annual pension.
Having looked at the TPS website I have read about ‘Buy Out’ and ‘Faster Accrual’ but am still none the wiser about my best way forward.
Is anyone able to explain the options to me in idiot proof language?
Comments
-
I'm not a TPS expert (there should be one along before too long) but based on the info here:
The normal accrual rate is 1/57th. So, if spend your entire 20-year career earning £40k pa your TPS pension entitlement will be worth 20/57ths of £40k, which is about £14k pa. That together with your state pension of about £12k would mean a retirement income of £26k pa before tax.
Faster Accrual improves the accrual rate. The fastest rate offered is 1/45th. If you took that accrual rate for your 20-year career you'd retire with a TPS pension entitlement of 20/45ths of £40k, which is almost £18k pa. Plus your state pension that makes £30k pa before tax.
I don't know what NormalPension Age is in TPS but if it's older than 65 you'll see a small actuarial reduction to those figures of you take it early, or you can bridge the gap with savings etc.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Ofgem cap table, Ofgem cap explainer. Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Best kettle!
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.2 -
Do you understand that the Teachers Pension Scheme is a bit like buying deferred salary, not a pension "pot"?
If you get that basic principle, and like it, then faster accrual is likely to be an option you should focus on first.
2 -
There is a group on Facebook run by David Fountain that will answer your queries but it cannot give advice.
The way the teachers pension works is as stated 1/57 of your salary added to your pension every year. The following year this gets revalued by the CPI rate in the September of the previous year plus 1.6%
Normal retirement age for you is 68.
As an example someone opting for faster accrual at 1/45th for that year earning £45,000 will pay an additional 9% in contributions. You will roughly be doubling your contributions to £4054 for an extra £210 in pension.
However you cannot accrue more than £6,500 in total, but this is revalued each year. If you were on £45,000 it would take you 30 years so this may not apply depending on your salary.
If you did this for 20 years and retire at 65, you get in the above example £4,200 extra pension reduced by 9% to £3822 at a cost of £81000 gross. Your CA pension would also reduce by 9% at 65. Again using a salary of £45,000 and applying the reduction this would be £16700 approx. Total pension £20,522.
Buy out allows you to cancel the automatic additional 3% pa reduction in the CA scheme that takes place - it's 0% at 68 rising to 3% at 67, 6% at 66 and so on up to a maximum of 9%. The reduction factors are the same as for normal pension age 65 so for you with normal retirement age 68, if you retire at 65, 9% is taken off your pension in addition to the normal retirement factors. However to buy out you have to elect to do so in the first 6 months of joining the scheme. On £45,000 this costs 2.85% or £1282.50 a year but you need to do it for every year until you retire. On the £45,000 salary quoted this will provide a pension of £18400 approx with no reduction at 65 at an additional cost of £25,650 gross.
You can of course do both. If you opted for 1/50th and you opted for buy out then it would cost you £3613 pa gross and you'd get your full £18,400 pension with no reduction plus £2200 again with no reduction. Total pension £20,600 at a cost of £72260.
I'm not an advisor but if you want to send me your figures I can produce an estimate for you on your likely pension at a given age either with or without faster accrual and again with or without buyout.
Hope that helps.
2 -
I've not altered my TPS contributions (though I'm hoping for more years of service than you'll be able to accrue), instead I'm saving into an AVC which still comes from my salary, but will be accessible from 55 or 57, and I can use that to bridge the gap before I can take my TPS pension unreduced. This may not be the right option for you, but wanted to make sure you're aware that is also an option. You can also do this alongside higher accrual etc in TPS.
0 -
If you started teaching before November 2021, you can access your pension at 55.
You may not feel like doing that now but it's one of those jobs where full-time work can become wearisome for many, whereas accessing your pension early while continuing to work part-time can improve work-life balance while allowing you to earn for longer and maintain some financial security.
You'll find more info on David Fountain's website and facebook page. Judging by the people posting there many older teachers prefer tapering their workload as they transition from work to retirement. I've been doing the same and it suited me very well.
There is no honour to be had in not knowing a thing that can be known - Danny Baker1 -
I used to think teacher's pensions were good, but this doesn't sound great tbh. I guess what you are giving up salary wise for what you are getting is okay, but it doesn't seem like your final annual amount reflects the hard work that being a teacher these days entails!
A DC pension is very flexible in comparison.
Think first of your goal, then make it happen!0 -
I’m in the TPS. I looked into AVCs a few years ago. I chose to contribute to a SIPP instead as it was more flexible. I’m happy with my decision.
1 -
I used to think teacher's pensions were good
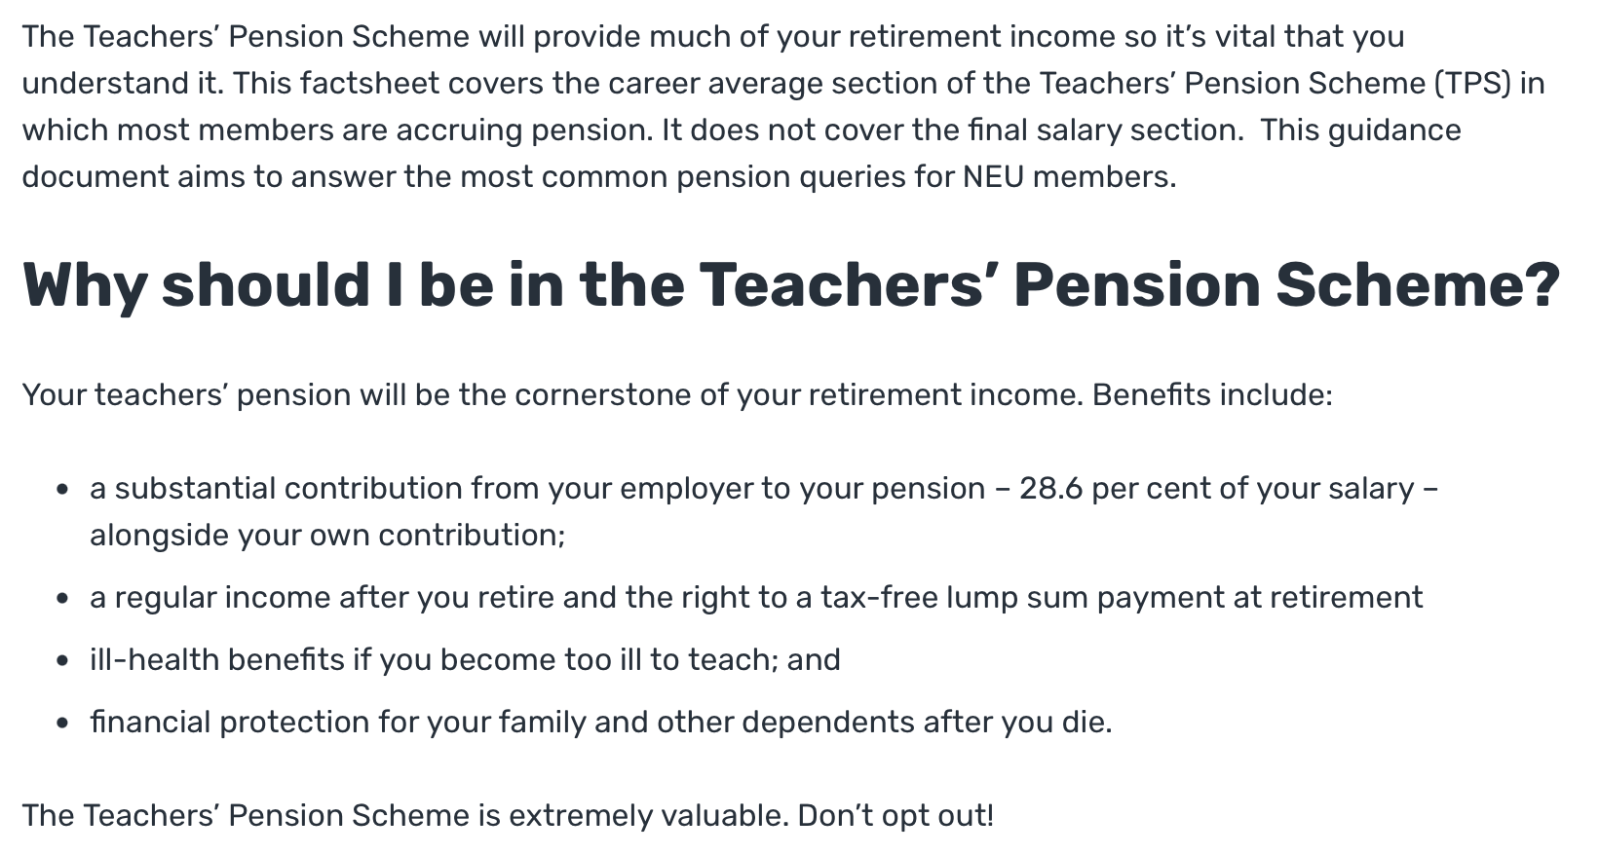
They still are - and not just good, but excellent. The problem isn't the pension scheme; it's understanding what it offers. For sheer complexity, it really is hard to beat. Unfortunately the downside of that complexity is people don't appreciate just what a great deal they're getting by being a member, taken from https://neu.org.uk/advice/your-rights-work/pensions/teachers-pension-scheme
 Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!5
-
I've read online that you could replicate the Teachers pension yourself by using private pensions and life insurance, but it would be difficult and could cost you about a third of your income.
There is no honour to be had in not knowing a thing that can be known - Danny Baker0








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.5K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards