We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Found forgotten Workplace Pension
Comments
-
Edited to add, Cannot see any specific mention of GAR on annual statement. It just gives an annuity rate but does state for 5 years guaranteed somewhere in all the text. I have requested a pack for further information.
You wouldn't expect to see safeguarded benefits mentioned in the statement. It was in the original policy document and doesn't get repeated in statements. However, it is an explicit question that should be asked of the provider: Are there any safeguarded benefits, and if so, what are they?
The five years you're seeing mentioned is just one of the assumptions on death benefits in the projections. Projections are made up of a range of assumptions which are statistically unlikely to be accurate. They're just a very, very simple guide, and typically understated the position.
I have done hundreds, if not thousands, of pension transfers away from Pru over the years and never had a problem. In modern times, they've all used Origo. The amount doesn't matter as that is not a measure for whether they use Origo or not. The measure will be if there are safeguarded benefits or it's a non-standard plan. They won't allow a transfer out on a plan with safeguarded benefits via Origo unless you've had an IFA sign to say they've given advice.
The reference to £30,000 suggests that the plan you have has safeguarded benefits.Under £30,000 they can transfer out without an advisor being involved. Over £30,000 they would need an advisor involved.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.0 -
OK So the pension I had with a GAR was with Scottish Widows and they changed the format of their annual benefit statements just before I took my annuity. The new version was over 30 pages long and had 2 mentions of the GAR but looking back at the older (much shorter versions) they did not mention it.
So yes you should ask the question. When I used Retirement Line to buy an annuity in 2024 they suggested I should ask the following questions of the pension companies operating the pensions I was using to buy the annuity:
"Does this pension plan have any safeguarded benefits? For example Guaranteed Annuity Rates (GAR), Guaranteed Minimum Pension (GMP) or Protected Tax Free Cash?
Does this pension plan have any penalties for transferring? For example, Exit Penalties or Market Value Adjustment?
Are there any other benefits attached to my pension plan which would be lost on transfer?
Do I require transfer forms or can transfer of funds be made by ‘Origo’ transfer. (Origo transfer allows the pension providers to communicate directly without the need to complete any further paper documentation)."These questions could apply just as much to a pension transfer as to buying an annuity. I mention it in case you might want to ask these questions of the Pru (probably best in writing - it has been suggested to me that the average customer service agent won't know the answers) And you have had answers to some of those questions already - eg exit charges. Anyway I put it out there in case it helps.
Just as an aside on the Origo thing - one of the pensions in 2024 did not use Origo so paper forms were needed. It was the quickest transfer of the five! Having said that Origo is meant to speed things up.
0 -
Thankyou that’s a great help. It was a workplace pension back in the early 90s which I honestly didn’t even recall signing up to. But being younger probably didn’t take much notice of most things back then!
The annual statements do state £0 in the MVR but I have now found this below which mentions “protected rights” so could that be it? The total transfer rate is over £30kBased on assumptions we've made, the value of the non-protected rights part of your plan on 1 January 2031 could be
Also based on assumptions we've made, the value of your former protected rights part of
your plan could be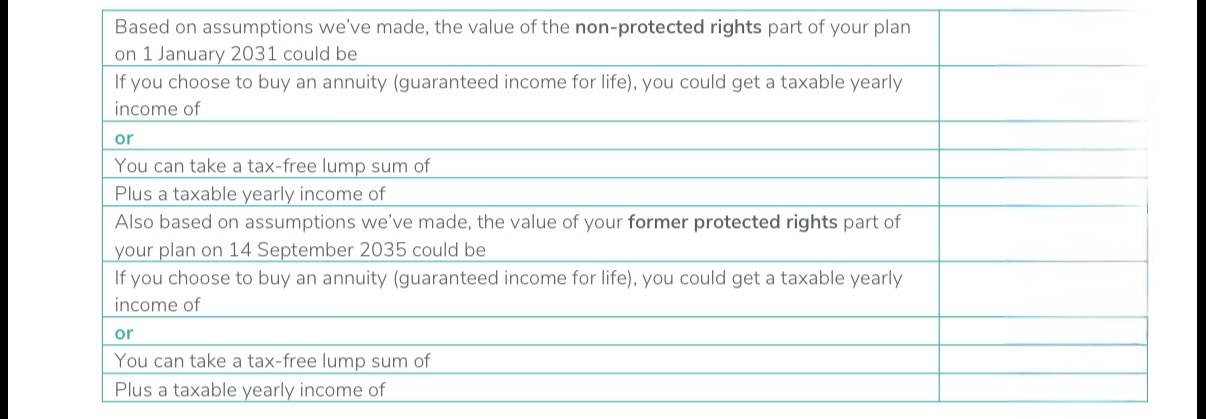
I have asked for an information pack, whatever that will contain, but will go back with questions first. No immediate rush as I have only just found it anyway but it would be good to know whether it’s worth adding to my SIPP given that I will be doing drawdown in 5 years.
0 -
You will note "former" protected rights.
Protected Rights were the part of your defined contribution fund that
related to contracting out of the State Earnings Related Pension Scheme
(SERPS) and State Second Pension (S2P).In return for contracting out, the government paid a National Insurance rebate or minimum contribution into your workplace pension This section of the pension was legally ring-fenced and subject to strict rules and restrictions as to how the funds within it could be used.
On April 6 2012, the government abolished the separate legal status of protected rights; the specific rules about how these funds had to be applied were removed.
In effect they became subject to the same rules that applied to the rest of the pension and could be used in the same way.
Having had protected rights does not mean that you must
also have had
a GAR - see
With regard to transfer to your SIPP, if there is a GAR see
See also which may be relevant.
0 -
The annual statements do state £0 in the MVR but I have now found this below which mentions “protected rights” so could that be it?
The MVR is nothing to do with protected rights. It is to do with the with profits nature of the policy. Essentially it is to cover the Pru in times of financial downturn - ie if the markets plummet then they can reduce the amount transferred so they are not robbing those who stay behind to pay those who transfer out.
I must admit I do not know why the Pru distinguishes between non protected rights and former protected rights in the statement. Maybe it is just a carry over of what they have doe in the past when there was a distinction. Actually I have just noticed they project the two things forward to different dates (2031 and 2035). Presumably 2035 is when you hit 65.
0 -
Well spotted! I had not noticed that. To be honest it’s as clear as mud with “former rights” being repeated with differing values in possibly the most complicated annual statement reading! Either way I will stick to the suggested questions and see where it ends up and then look to add to my SIPP if possible. Thanks for all the insights.
0 -
From my memory I believe the NHS pension wouldn't accept protected rights. It would only accept non-protected rights. This could explain why the former protected rights have been left behind.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.0 -
Wrong thread?
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards