We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Fiscal drag and withdrawal strategies
Comments
-
Indeed but I think as you get older you realise that time is worth more than a few extra quid.2 -
This is my thinking.
Surely if you do some of the fun stuff now, whilst younger and still gainfully employed, you will have the same amount of money overall as if you did it in retirement?
Just like I was sal sac down to low £30k but realised this is really stupid. For my circumstances I'd be better paying myself £43662 making best use of the Scottish BRT band allowing some more fun stuff/more in ISAs now as fiscal drag will be brutal later on?
1 -
oh my wife has clearly decreed an ‘essential discretionary’ budget from the start. I’m treating it as discretionary from a planning perspective so can take a little more risk, but its still important.
my fun money part there was my timing of DB means from 67 potentially £0 draw needed from my DC so it all becomes flexible for extra treats for us or for helping the kids. Taking the DB at the start meant a small but continuous draw requirement. that neatness appeals to me (although inflation/personal inflation/tax bands etc will all mean that won’t be that neat in 12 years time but it looks nice on paper!)
0 -
Or possibly "the worse you have planned"…
Although it's hard to plan when the tax goalposts keep getting shifted.
0 -
My mindset was always of flying just under the higher rate tax band but this thread prompted me to do some modelling of withdrawing the maximum amount from my pot via drawdown without triggering higher rate tax, taking into account my DB (£14.5k) and also State Pension when it becomes payable.
I made a few assumptions in the projection, ignoring inflation and assumed no changes to the tax bands or LSA.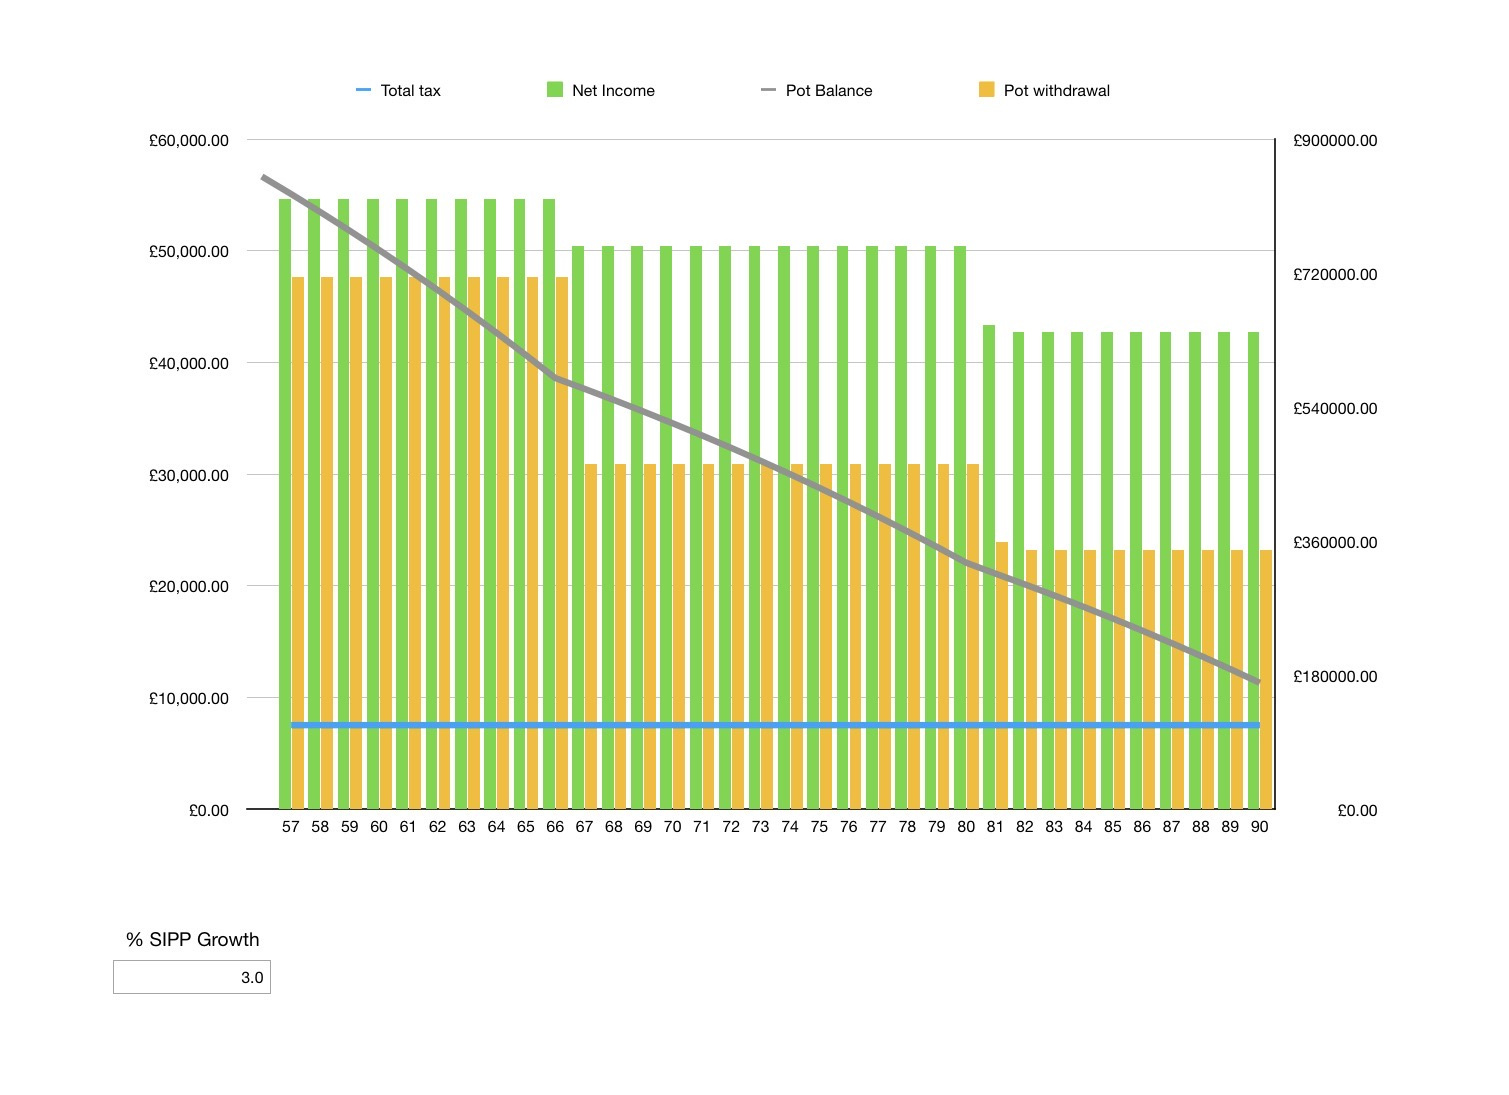
To stay completely under the higher rate threshold then I will need to accept a reduction in net income when the SP becomes payable at 67
At 81 the LSA will be exhausted and a further reduction in net income will occur.
Accepting this is only a simple linear model then if the SIPP grows at anything above a 2.5% average each year then it means in all likelihood I will have to pay higher rate tax at some point unless I both accept the reductions in income and leave the rest as an inheritance, which had never previously factored in my planning.
So far my strategy has always been focused on what I can take at retirement but it's becoming clear that I will need to keep a close eye on future pot growth and long term strategy.
2 -
If the 40% threshold continues to decrease in real terms (i.e. the drag goes on) then nothing is going to prevent hitting it at some point, if you have many years to go before pension time say. As others have mentioned, paying tax is sort of a luxury, but it makes no sense to pay more than one should.
Your pot is rather large, and you still have 180k left at 90. Would this be destined for kids? Presume if you withdrew it sooner, the dashboard tax threshold light goes on?
0 -
While we're all busy rubbing our crystal balls in a mood of fiscal gloom. It is safe to assume that the government (of any colour) will continue to incentivise pensions saving through the tax system, while attempting to curb avoidance. Government finances are currently very tight and will continue to be for some time, but this won't last forever.
Do plan ahead to make the best use of tax bands and allowances. But be realistic in your expectations and don't over-complicate things.
🐻 A little FIRE lights the cigar3 -
Yeah, exactly that. If there is anything left when we are gone then the kids are welcome to it but we never actually planned on there being anything. They've had their lift up being subsidised through University and into good jobs (well, one of three left to finish in this regards) so the money is there for ourselves as it stands.
I've been fairly conservative in my planning and assuming that growth will be a couple of % above inflation but then I look at the 2yr performance of my funds and one is 28% and the other 47%!
I had thought that managing the withdrawal process would be a sort of one-off, rinse and repeat type process but it looks like it might become more of a careful balancing act between making sure we have enough money and having too much! (Never thought I would be saying that).I'm actually retiring this week 😀 so it has suddenly all become very very real.
1 -
I had thought that managing the withdrawal process would be a sort of one-off, rinse and repeat type process but it looks like it might become more of a careful balancing act between making sure we have enough money and having too much! (Never thought I would be saying that).
I am expecting the permanent move to no employment income and being dependant just on my investments to be a new set of skills. Equity risk, %age bonds, taxation, cash buffers, LTA, SIPP providers quirks of handling the pot, MPAA, SoRR and so on. You're prudent to assume it's a bit of work to get into a good system… just before taxation and limits change again.
1 -
My pre-retirement modelling demonstrated to me that taking my DB at 55 (a year after retirement) increased my probability of success appreciably due to SORR, even though slightly less tax efficient. Of course that would depend on relative contribution of DB / DC etc. to retirement income.
1












Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards