We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Self managed DMP advice



Hello,
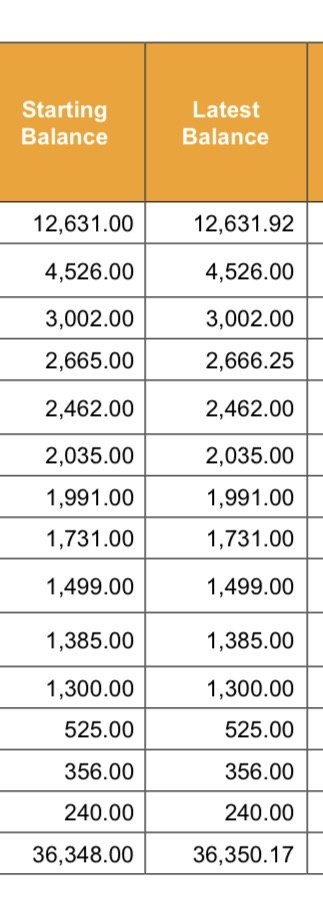
Wish I had found this site before but we learn! I’ve been in a DMP since December after panicking and going with a managed company who charge £50 a month. I’m now feeling much clearer after having time to really review my options and would like to go self managed however the company are warning that the chances of a CCJ being issued is much higher if I go self managed than if I stay with them. Is this the case or are they just trying to protect their £50 a month? By going self managed I would be able to clear my debt approx 3 years quicker bringing it down to 5/6 years vs the 8/9 currently and the lenders would get more per month than now. Most lenders have accepted the payments and defaulted me already, including a £12,000 loan lender. Step change recommended bankruptcy despite the impact on my job so would not go through them. I have no assets and private rent so a CCJ seems pointless for the lender but would be a big concern for me professionally. Total debt is £36,000 ish (£34,000 if the loan full interest isn’t charged, paying £450 to the DMP)
Comments
-
OK Cancel the vultures NOW. Of course they are going to spin you a tale about CCJs as they want your monthly fees.
You don't need to rush into self management, nothing will happen if you go 1 or 2 months without paying anything despite what the vultures tell you.
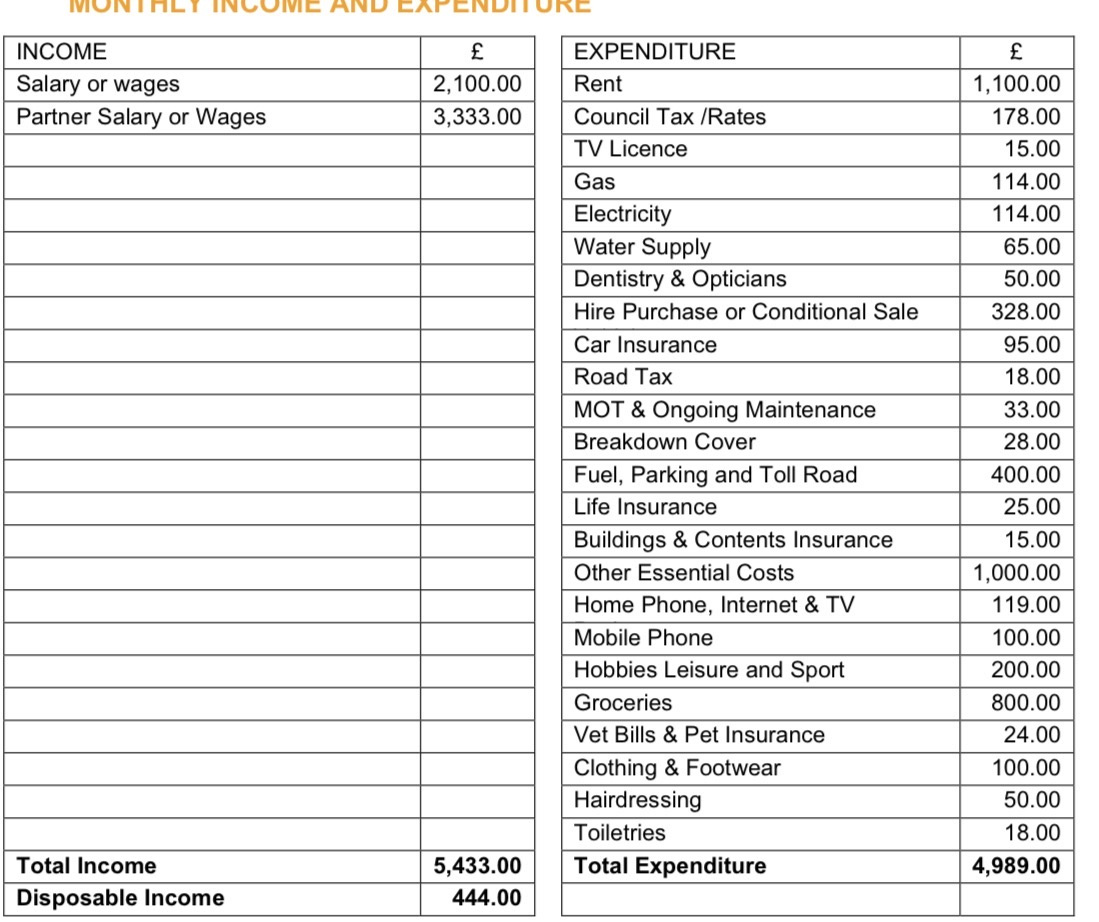
For us the give you the best advice that suits you we will need to see a full SOA.
If you go down to the woods today you better not go alone.1 -
Ditch them. There are no good reasons to go with a fee-charging dmc.
0 -
Have any of your creditors registered defaults yet? The sooner they do, the quicker your credit record will recover.
If you're getting Arrangement to Pay markers, your creditors can't even start legal action. But your credit record will take longer to repair.
What level of emergency fund do you have?
If you've have not made a mistake, you've made nothing0 -
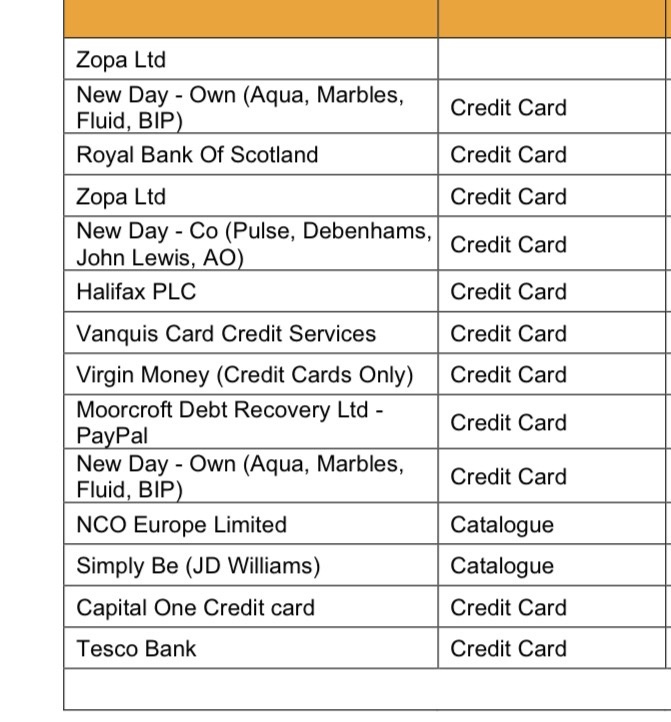
Can we see a list of the current debts, or even better a Statement of Affairs, see https://www.stoozing.com/soa.php
There are NO good reasons for carrying on with one of these fee charging firms. But
a) if would be good to know that you don't have any particularly difficult creditors and
b) if you are only paying 50 a month in a 450 payment, then stopping paying this (good idea though it is) will not cut an 8-9 year DMP to 5-6 years
c) StepChange would not normally recommend bankruptcy if you can afford to pay 450 a month
There may be other ways to speed up a DMP, either through a non fee charging DMP firm or self managed though.1 -
-
-
Debt management companies do nothing that you cannot do yourself, they simply facilitate payment of your account on your behalf, they click a few keys on a computer key pad, and that is it.
Ask a shoe salesman if you need shoes, they will say yes, do you get my point?
Pay them yourself, just like you did previously, except now its a smaller amount, paid according to your budget, instead of a minimum they specify, its as simple as baking bread, your just throwing £50 a month in the bin basically.
I’m a Forum Ambassador and I support the Forum Team on the Debt free wannabe, Credit file and ratings, and Bankruptcy and living with it boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.For free non-judgemental debt advice, contact either Stepchange, National Debtline, or CitizensAdviceBureaux.Link to SOA Calculator- https://www.stoozing.com/soa.php The "provit letter" is here-https://forums.moneysavingexpert.com/discussion/2607247/letter-when-you-know-nothing-about-about-the-debt-aka-prove-it-letter1 -
You need to complete the SOA Many Ways links you to.
We need full details of Interest rates and balances of all the debts and more details of your expenditure, Car on finance? Details of the £1000 expenditure etc.
If you go down to the woods today you better not go alone.0 -
completely agree. It was part of my partners IVA I “had” to have a debt solution in place so naively just agreed to allow his IVA to go through.
0







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.9K Mortgages, Homes & Bills
- 179K Life & Family
- 263.7K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards