We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Pension transfer with GAR




I wonder if anyone can help me with a query.
My partner has 2 policies with Royal London (ex CIS) they both have GAR. One is listed as a personal pension plan the other says appropriate personal pension plan, the former has a transfer value of approx £18500 the latter £40,000.
She enquired about transferring the £18500 one but has been told that she must take financial advice, I was under the impression that if it was under £30k then no advice was necessary or do they take the sum of the 2 separate policies, which is obviously above the £30k?
Comments
-
She enquired about transferring the £18500 one but has been told that she must take financial advice, I was under the impression that if it was under £30k then no advice was necessary or do they take the sum of the 2 separate policies, which is obviously above the £30k?
RL are correct. The two plans are almost certainly linked. One being from personal contributions and the other being from contracted out. CIS used two different policy numbers for each segment.
Linked plans use the total of the linked segments/plans.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1 -
Thanks very much for clearing that up, much appreciated.
So has the appropriate personal pension been her company pension? She asked RL if it was they said no, to be fair I have no idea what that pension even means.
Unfortunately she's not good at keeping records so has no information on any of her pensions and is just starting to chase them up
0 -
So has the appropriate personal pension been her company pension?
The appropriate personal pension would have been used for contracting out of SERPs.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1 -
Sorry if I sound dense but does that mean she has a company pension somewhere else?
0 -
So has the appropriate personal pension been her company pension? She asked RL if it was they said no, to be fair I have no idea what that pension even means.
The 'vanilla 'personal pension with RL might have been an employer-sponsored arrangement, if her employer actually offered a pension scheme at all. Auto enrolment only started to be phased in from 2012 and the smallest employers didn't become subject to the 'employer duties' to auto enrol staff until 2017. She asked about the 'wrong' pension - RL should be able to confirm whether or not the personal pension received employer contributions, or it should be apparent from any paperwork she now has.
'Appropriate' was just a bit of jargon and had nothing to do with suitability. Your partner and her employer were both paying full NI at the time she started the appropriate personal pension (APP). Once the APP had been set up:
- Part of her and her employer's NI contributions were paid over ('rebated') directly to the APP
- Her entitlement to the basic state pension continued to build up
- She built up a fund in the APP in lieu of the State Additional Pension (SERPS and later the State Second Pension) based on these NI rebates
- At the time, the benefits built up from NI rebates (jargon alert: 'Protected Rights') had to be treated in a special way, unlike contributions from an employer or individual. That requirement was abolished some years ago, and protected rights are now just ordinary rights with no special treatment needed
- BUT because of the GAR, she now has Safeguarded Benefits, which is where the requirement for advice creeps in.
If you managed to plough through that list of jargon and abbreviations, I can but commend you! I hope this answer helps…
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
Thanks for that. Yes it is a lot and nearly all of it went straight over my head.
One thing that definitely helped is you saying the vanilla pension might have been an employer pension.
When I checked the very small amount of information she has, she joined in Oct 91, she has told me the company didn't allow entry until you were 21 which sort of ties in with her birthday but last payment was Jan 95 but she didn't leave the company until May 95 so a bit of a mismatch there.
When they said the pension was not a company one she was asking about the vanilla one, the small one as she calls it.
I think she needs to speak to RL again and search out information on the Norsk Hydro pension scheme which is where she was employed.
Thanks again
0 -
CIS stopped writing new pension business in 2011. So ex-CIS plans now under the Royal London brand would have been set up prior to 2011. They had stopped offering guaranteed annuity rates many years before that.
CIS never offered group personal pensions. It did have a group stakeholder pension introduced in 2001, but that didn't have guaranteed annuity rates.
So two ex-CIS plans that both have guaranteed annuity rates won't have come from an employer.
As mentioned higher up, CIS segmented the contracting out of SERPs into one plan, and if regular contributions were made, such as by direct debit, these would go into the other. Both segments would have guaranteed annuity rates, though they would differ.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.2 -
I think she needs to speak to RL again and search out information on the Norsk Hydro pension scheme which is where she was employed.
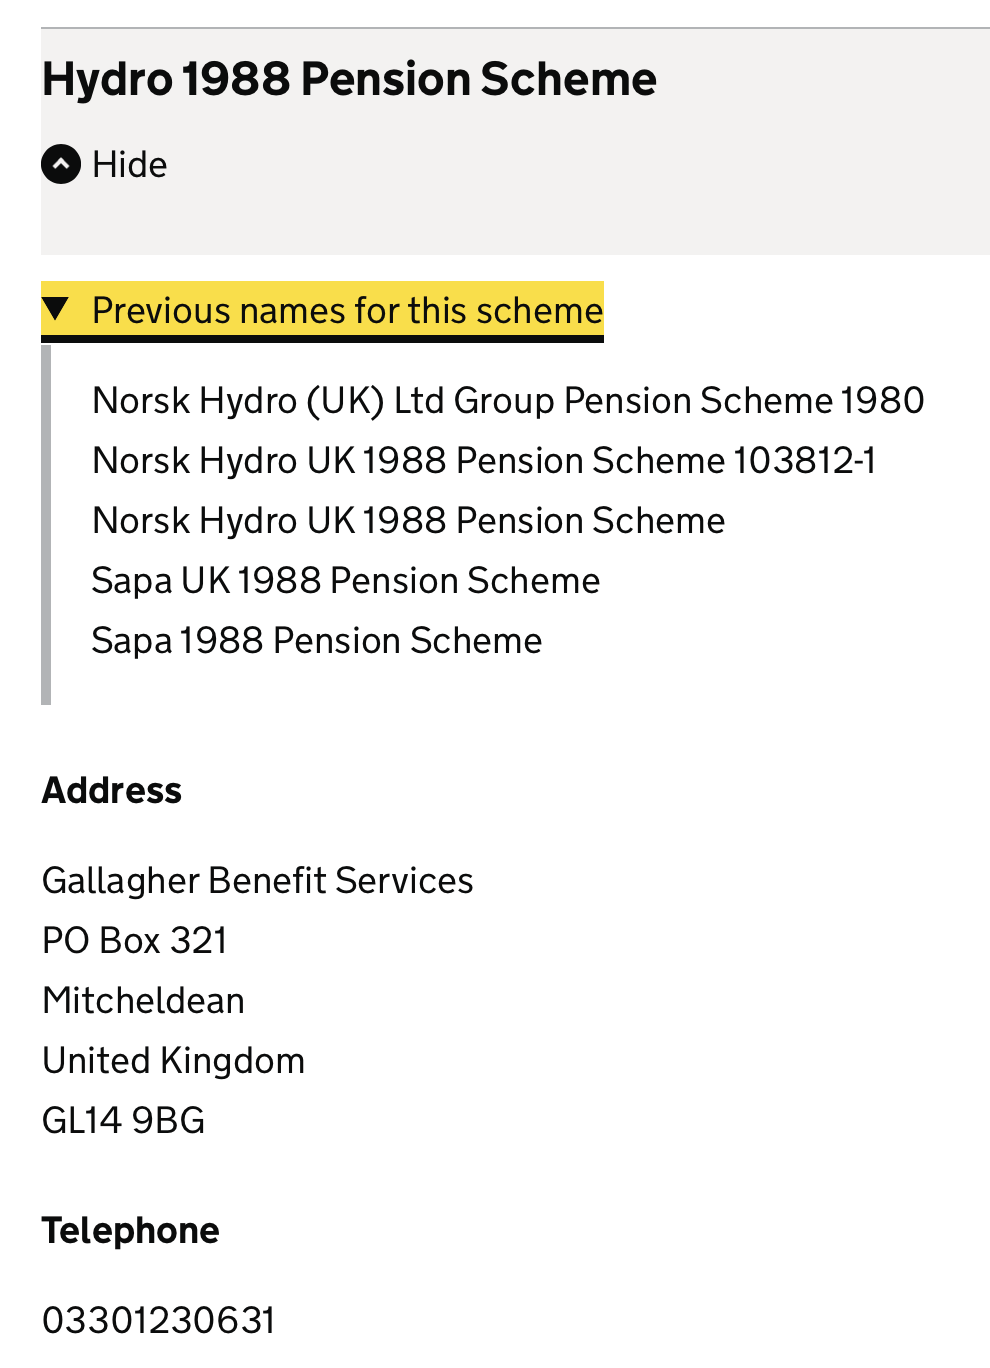
I think I can save her (and probably RL) a frustrating phone call. At the time she was employed by them, Norsk had a defined benefit pension scheme which was contracted out of the State Additional Pension. Had she been a member of that, she would have been paying lower rate NI contributions, so there would have been nothing to 'rebate' to her APP.
I wonder if she was persuaded to take out a personal pension rather than joining/staying in the Norsk scheme? Given her age and the dates you mention, that's far from improbable. Can she remember anything about such a possibility and/or being contacted about possible 'pension mis-selling' in the late 1990s/early 2000s?
It's worth contacting the administrators of the Norsk scheme and asking if they have any record of her ever joining it:
 Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1
-
Thanks @Marcon I'd just found the information you posted about the Norsk scheme, I'll get her to contact them. She can't remember anything about transferring out but to be honest it wouldn't surprise me if that's what could have happened. On the Gateway site is does say she's been in a contracted out pension scheme, so does that make it more likely she has been persuaded to transfer it over?
@dunstonh Thanks for the reply. Yes both pensions have different GAR. Also the APP increases yearly while the vanilla one is level
0 -
Thanks @Marcon I'd just found the information you posted about the Norsk scheme, I'll get her to contact them. She can't remember anything about transferring out but to be honest it wouldn't surprise me if that's what could have happened. On the Gateway site is does say she's been in a contracted out pension scheme, so does that make it more likely she has been persuaded to transfer it over?
It was a long time ago, she was much younger and pensions generally weren't exactly high profile at the time, so hardly surprising it's not something she instantly recalls with utter clarity - not many people would.
She was contracted out using the APP with Royal London, so the reference to being contracted out could simply be that. You can't be contracted out twice in respect of the same period of employment.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1




Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards