📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Is what I am doing sensible? What would you do
Comments
-
So i did it!
Took a while to complete a partial transfer of 200K from my workplace pension to an AJ Bell SIPP but after that completed I did the following trades today. I split it £75K into normal gilts and £125K into 'linkers' with a spread of maturity from 2035-2038. I am currently 46 so will ideally have access to my pension around 2037/38 (age 57-58)

Me and the missus still have over 900K in global equities in our Pensions/LISA's , with a further 200K in money markets. The idea being we have made 'enough' from risky growth so want to ensure a decent chunk is preserved but protected against inflation.Thanks for help and advice
Left is never right but I always am.1 -
As a matter of interest why have you bought two conventional gilts? Was it for comparison purposes to see how they fare against the ILGs? Or did you want a decent income coming in over the next 10 years to cover fees?
0 -
because I’m a meddler basically :)
the coupon at 4%+ seemed pretty good to me and they were priced below £1 so thought why not.Also learning for me to watch how all this lot perform over the coming 10 years
Left is never right but I always am.2 -
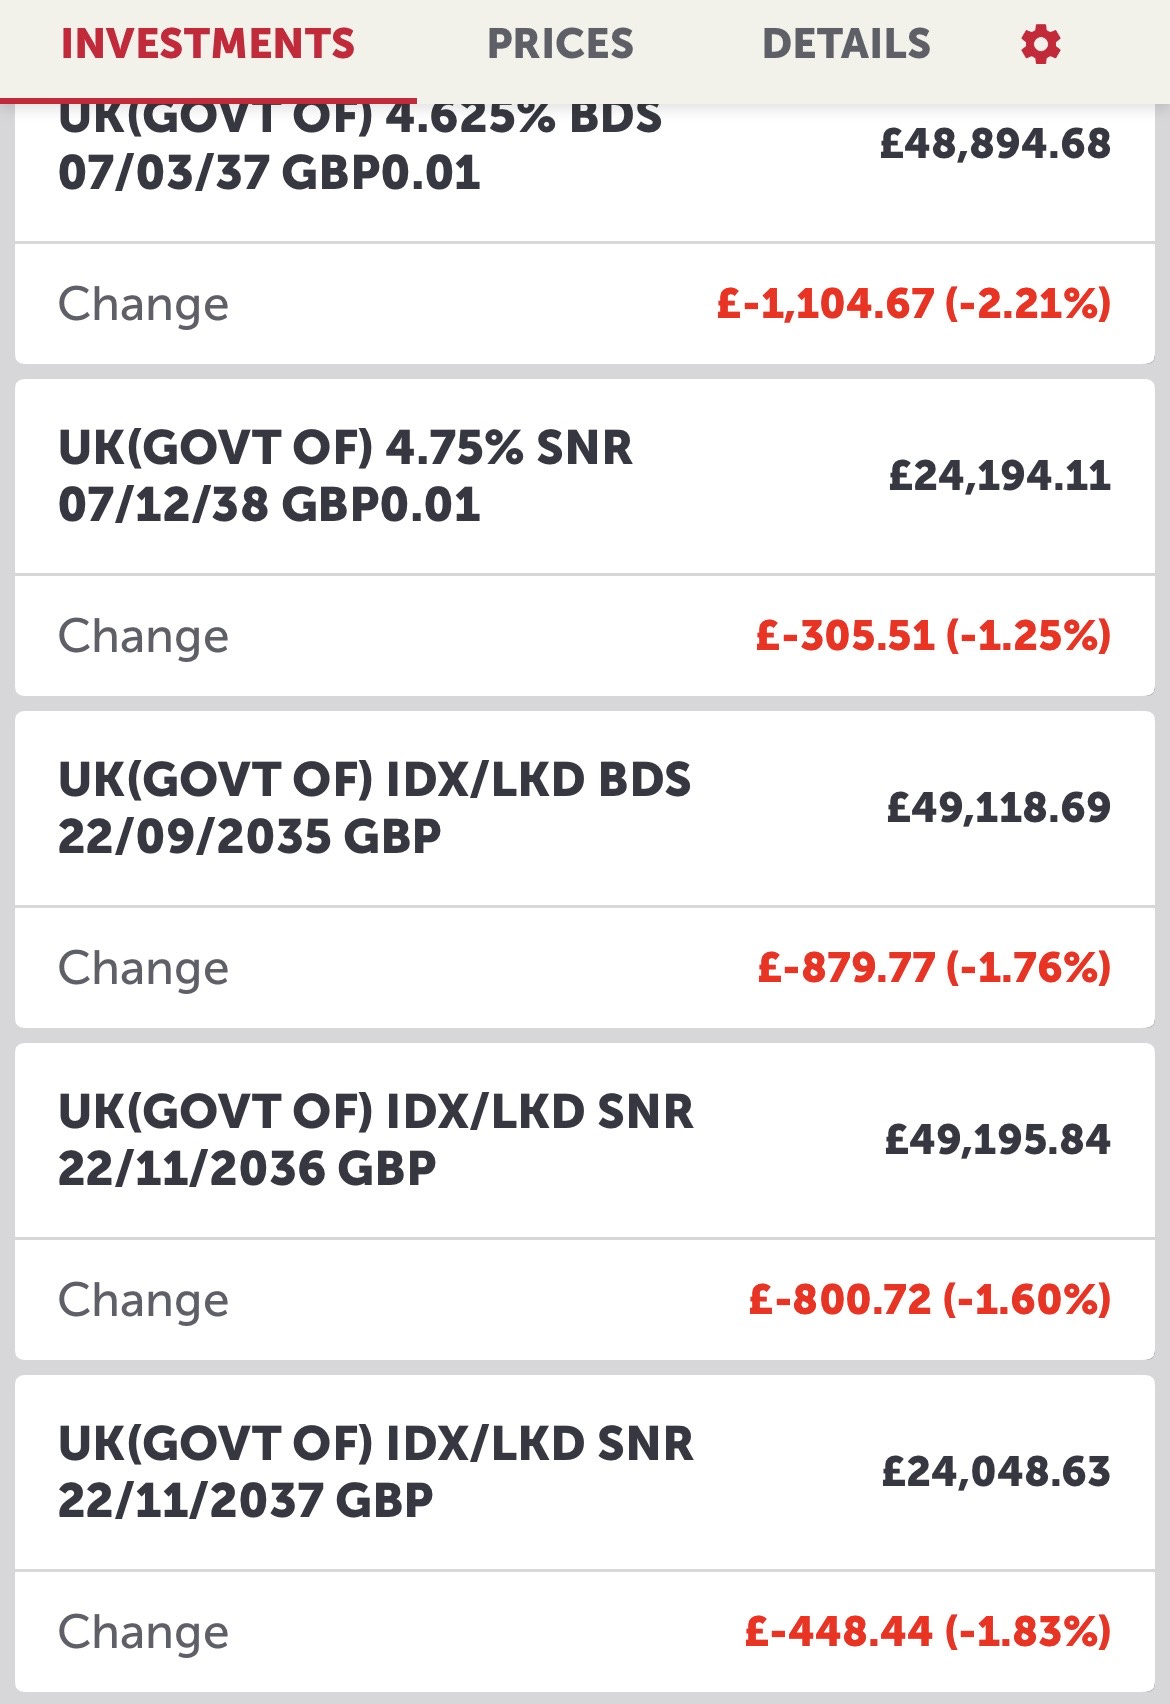
looking for a bit of reassurance ….
per above thread having hit my number I transferred 200k out of my workplace pension to a sipp and bought some gilts maturing around when I’ll be able access my pension
my investments appear to be losing value - to help further my understanding can someone explain what’s going on with these …
Have they really lost value?
if I sold today would I lock in those losses for r would the actual sale proceeds be different ?
if I hold to maturity (which is the plan) is it all good as this is just paper losses ?Thanks
Left is never right but I always am.0 -
Assuming those numbers are based on dirty prices, yes, yes and yes.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
You have completely won the game. Having over £1.4 million in total assets at age 46 with a modest lifestyle means you are effectively done. Shifting from wealth accumulation to preservation is highly sensible, but you have a few structural bottlenecks:
First, your biggest hurdle isn't your total net worth; it is accessibility. You cannot touch your pensions for 11 to 12 years. Your current ISA bridge (£82k) is too small to cover two people for over a decade.
Second, holding 40% cash to de-risk is fine. However, planning to use that cash to "buy the dip" if markets tank completely contradicts your goal of preserving your win. Pick a lane and leave the cash alone as your safety blanket.
Third, the Lifetime Allowance is gone, but the Lump Sum Allowance caps your maximum tax-free pension cash at £268,275. Everything else in your £1M+ pot will face standard income tax upon withdrawal.
And finally, your partner cannot touch her LISA until age 60. So prioritise standard ISAs instead to fund your early retirement bridge.
What I would do now is calculate your exact annual living costs. Max out both of your £20k standard ISA allowances every single year to build that 12-year bridge, and accept that your pension cash is an insurance policy, not a market-timing fund.
1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards