We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
42 Year olds diary for last min retirement planning and debt free living





I guess you get to a point in your life where you wonder what will my retirement actually be like? I am at that stage now…. This is going to be a long post!!! My plan for this diary is to update it weekly with what I have done, and keep a running total of side hustle earnings (i want to keep under the 1k limit) and the current years isa contributions.
A bit about my situation, I am a 42 year old male (43 in June) … For a long time I was self employed and did not save for a pension. I work full time at royal mail and will have been ther 5 years in December. Married with wife working 28 - 34 hours a week at tescos, no kids. So dual income no kids, however a low combined earnings of approx 45K-50k per year.
We have left everything really late, But Im going to prove that its not TOO late.
Four years ago we managed to get on the property ladder with a small one bed flat - its small, apartment living isn't perfect neither, but its cheap to live and in a nice area with a short walk to the beach! our mortgage was 122K , fixed for ten years at 2.59%, we have 6 years remaining on that fix. We were all set to take out a massive new mortgage and move into a bigger place, but decided we are actually just fine here and it gives us many more options.
We run a 10 year old Japanese car and intend to keep it on the road indefinitely.
We are debt free aside from mortgage (so as of today £101268.23 in debt!)
Our pensions are very low for our ages (43 an 38) that said now i'm working full time I think we will be ok, my company's scheme is pretty good (i contribute 5% they add 13%) I also have 16k in an old DC pot from the old scheme. That's it!
THE PLAN……
Firstly - I want that mortgage cleared before the fix ends. To accomplish this I will save into a cash isa aggressively. because our mortgage rate is low i have prioritized savings instead of overpayments, With our time frame I am aware the money could perform better on the stock market, but its fairly close at six years.. and I'm not comfortable with our funds there knowing I need them in six years. (for retirement different story)
If we make no overpayments out mortgage should be sitting around £75000 at the end of our fix, So that is my cash isa goal!
This is my current savings.
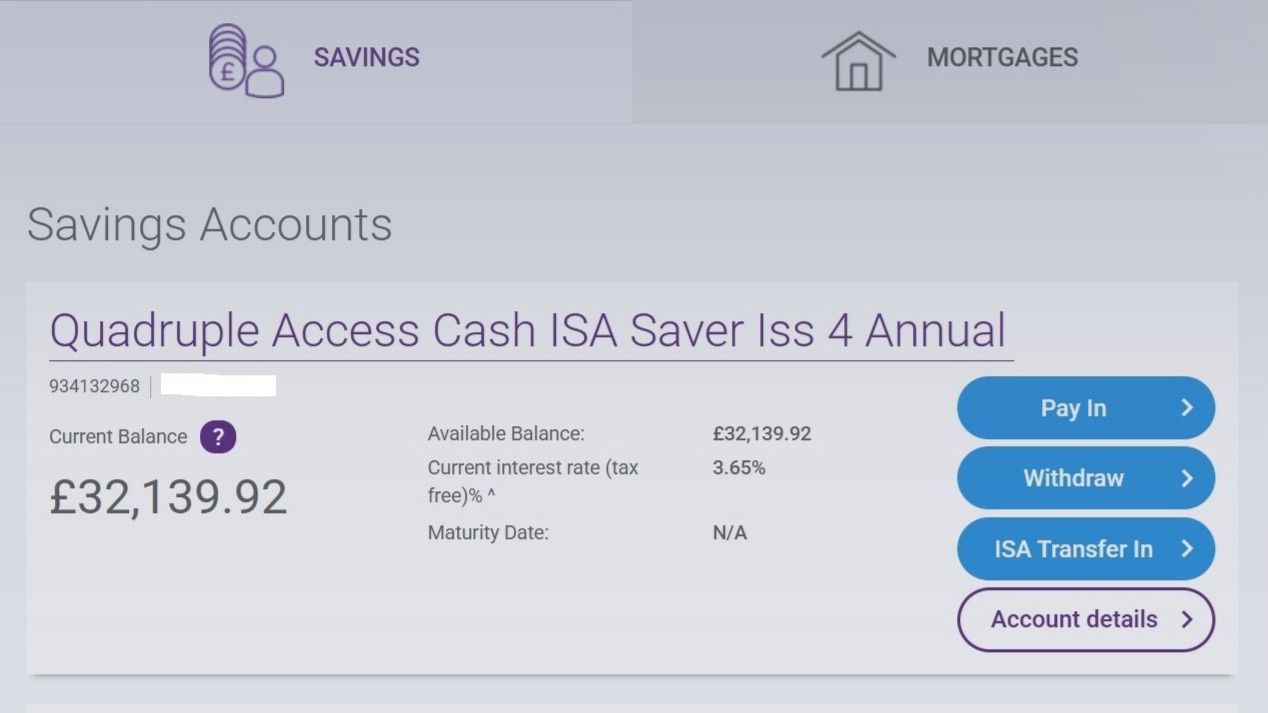
The interest rate isn't cutting it right now so i have transferred into HL active savings. (waiting for that to go through)
To get this amount up to the sum I need (75000) in 6 years I will need to add £445 per month.
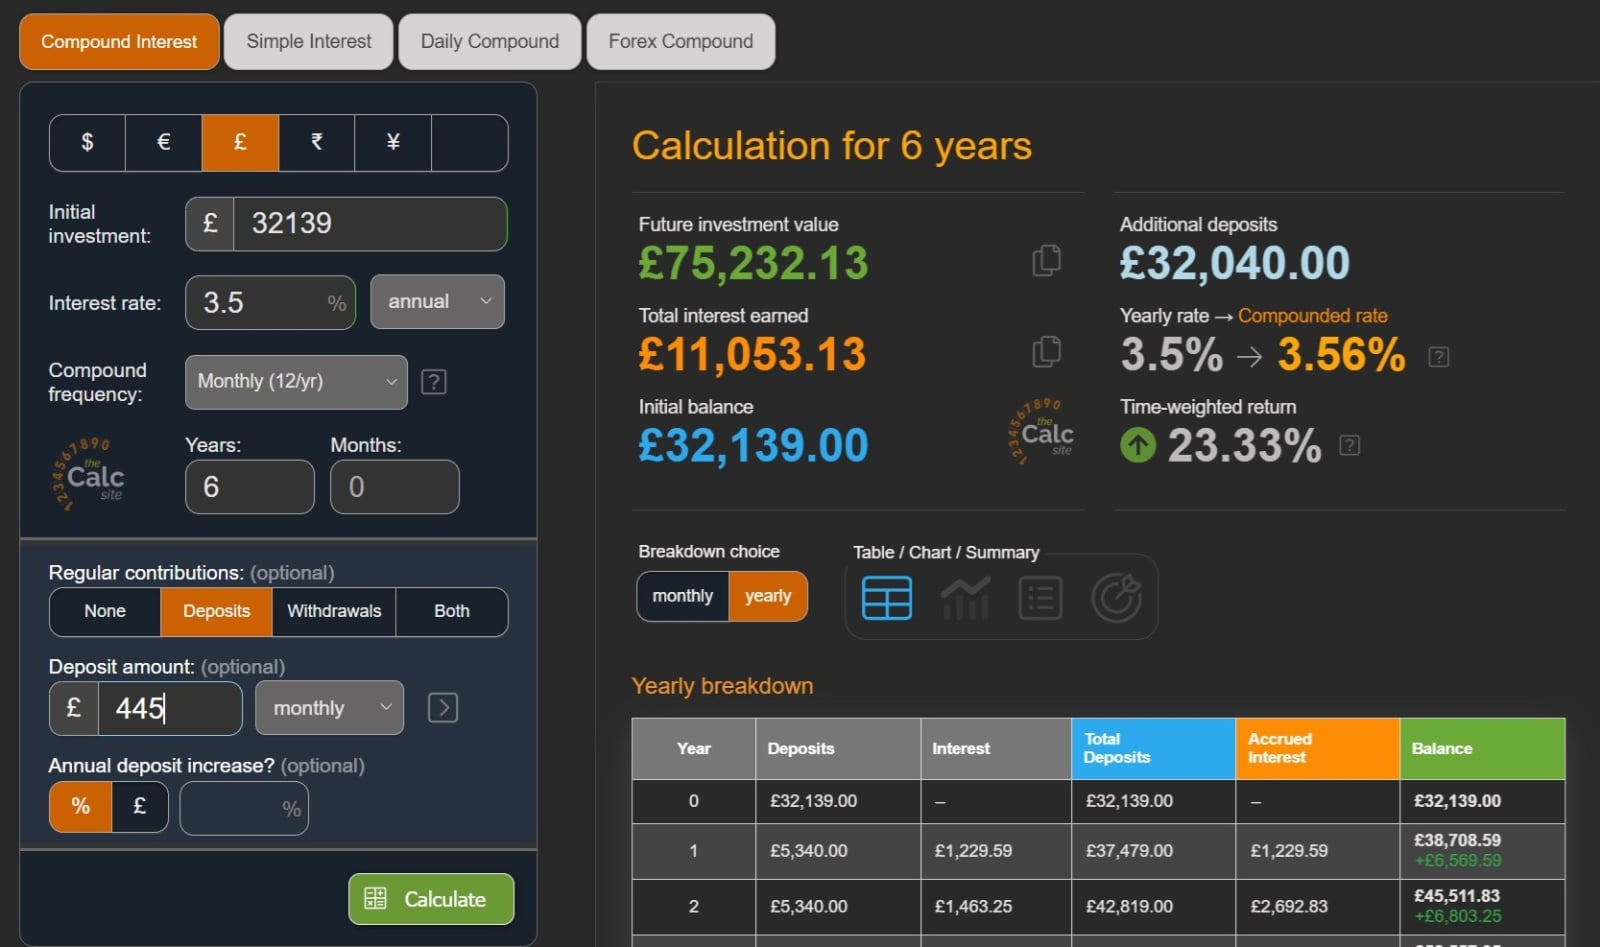
That is assuming a interest rate of 3.5%, so could be a bit of variance there. But £445 will get us close enough!!. So this is investment priority number one. Its worth noting this is also emergency funds if needed!
Other funds..
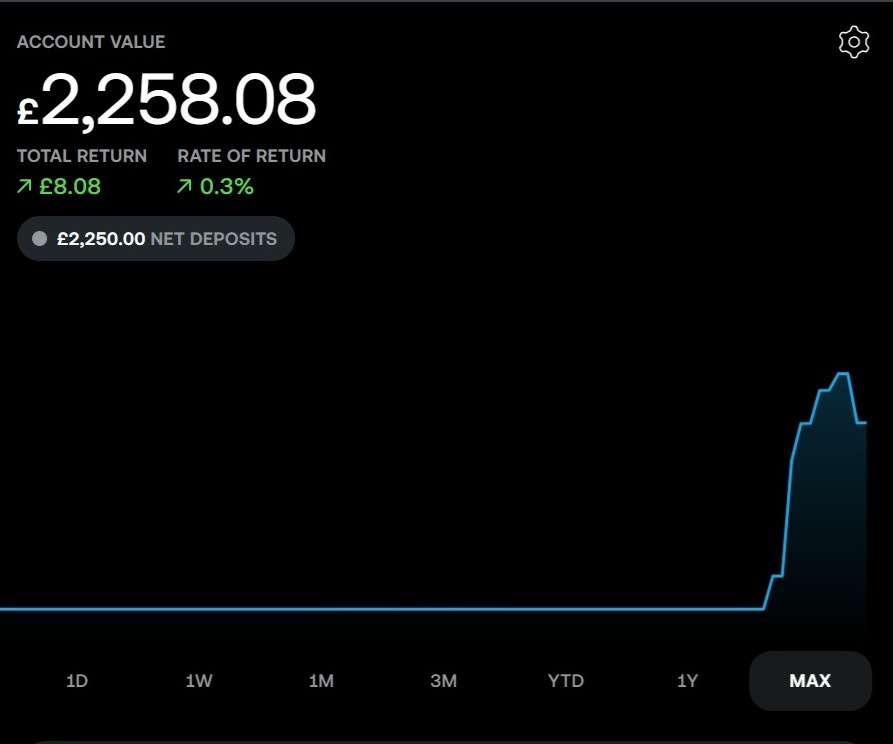
I keep a sum on trading 212 for general use - this is easy access and not in a isa, It's paying 3.8%, I tend to save money here put aside for known expenses we will need soon - like car servicing, apartment service charge, holiday funds ect. This is the current sum.
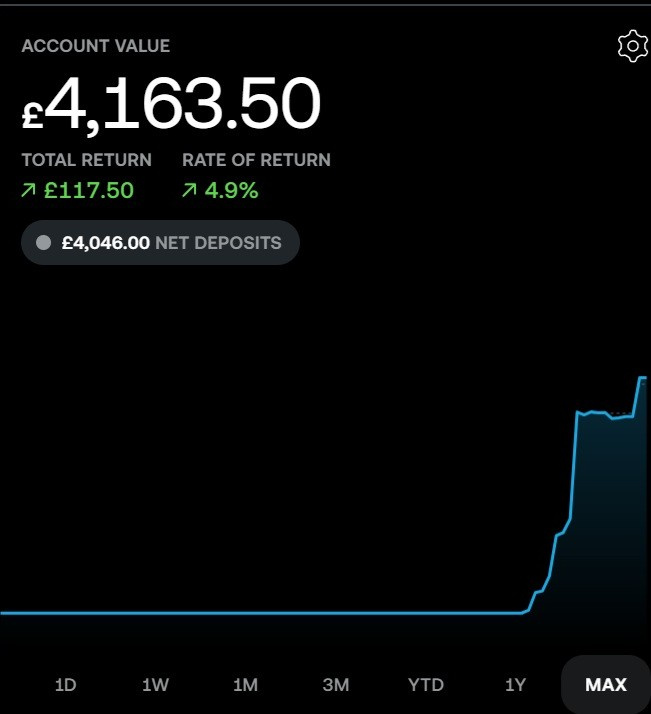
Stocks and shares isa - I do have one, but not sure where it will be in the future as my hands will be pretty full with LISA and Cash ISA contributions, but maybe i can add to it, here it is currently, its mainly on ETFs.
Future goals -
So paying of the mortgage is great but what about the future? we both work physical jobs, and who wants to be working into their late 70s? ( i realize some may but I would like the option to choose if that's not me when the time comes!) So what's the plan??? firstly get that mortgage clear and then start SIPPS
We will be using stocks and shares Lifetime Isas, These will be maxed out at £333 a month each. I have 7 years contributions left and the wife has has 13 years left. I have done the sums and if we max out or contributions, based on a return of 5% annual we could expect a joint sum of 220k at 60 years old, This can be used to move home or reduce working hours until we are ready to draw our pensions.
Oh yeah, one last thing - £300 a month for a holiday fund, no good not living now too!
The plans in place, the start of a very long journey is already under way.
Mortgage overpayments in 2022 - £3515
Mortgage overpayments in 2023 - £600
Mortgage overpayments in 2026 - £2700
Comments
-
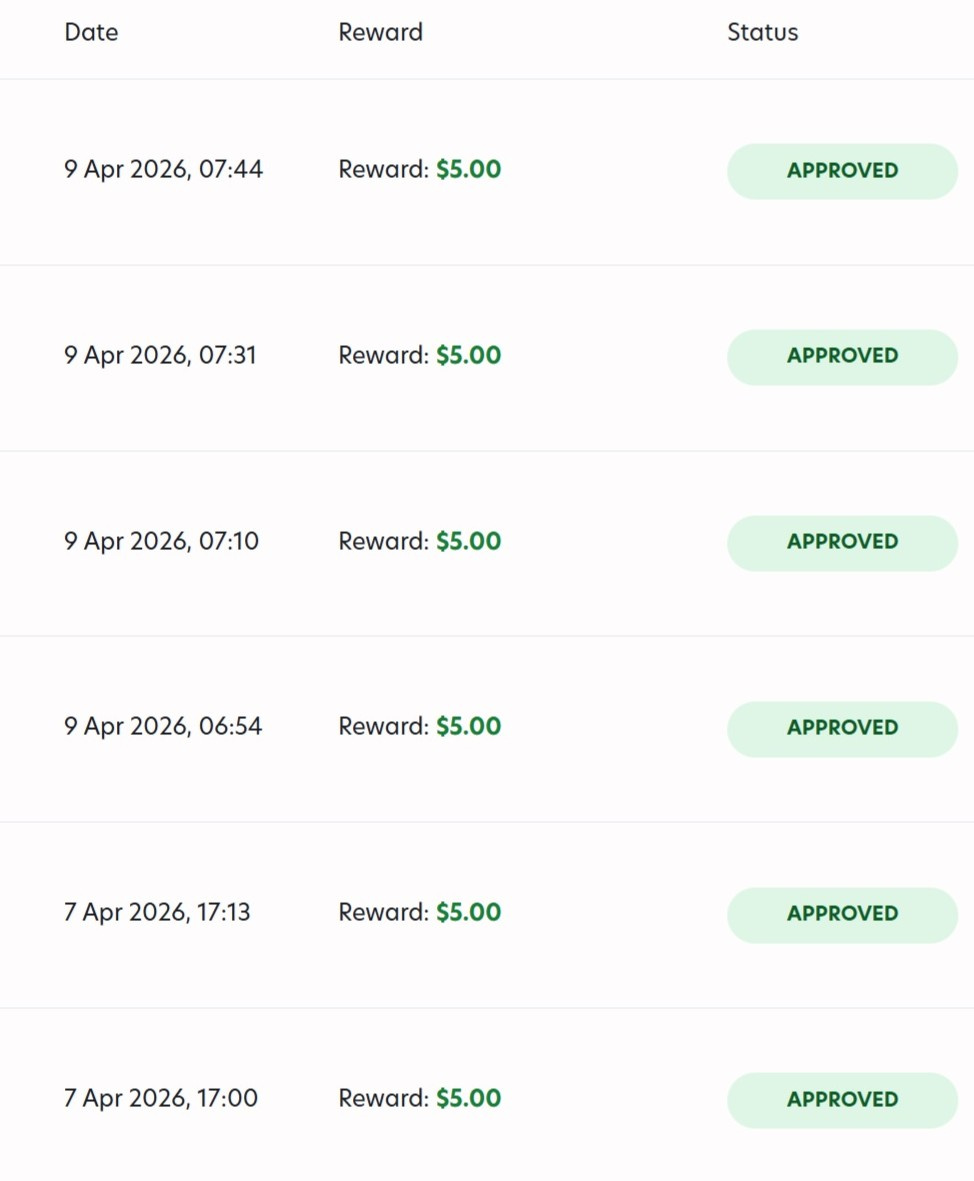
Todays side earnings doing surveys
Total side hustle earning this Tax year - £21.90
Total ISA contributions this tax year - £515
 122k mortgage started 10th June 2022. Outstanding balance - 99.7k
Mortgage overpayments in 2022 - £3515
Mortgage overpayments in 2023 - £600
Mortgage overpayments in 2026 - £27000 -
So the key points from that seem to be:
Assets and liabilities
- Mortgage: £101,000 (fixed to 2032 at 2.59%)
- Cash ISA saving, essentially being used as mortgage offset: £32,000
- SSISA: £4,000
- Non-ISA savings to be used for known future expenses: £2,000
- Old DC pension:£16,000
Current saving plan:
- £10,000 p/a into LISAs (both partners)
- Royal Mail Tesco via work
- Tesco pension (assumed) via work
- Everything else into cash ISA
Future saving plan:
- Bring cash ISA to mortgage level by 2032
- When cash ISA equals mortgage, shift to using SIPPS instead of cash ISA
- At age 50, redirect LISA saving into SIPP (assumed)
Here are some observations from me:
- The clickable Reddit flowchart is worth looking over to ensure you have everything covered, such as ill-health protection, death protection, etc.
- The £2,000 of instant access saving is very low as a precautionary savings fund, but presumably the cash ISA could be accessed in an emergency. So you should plan to increase precautionary savings when the mortgage is paid off and the cash ISA is no longer there.
- After 50 you cannot contribute to a LISA, so presumably, as you each reach 50 the LISA contributions will be redirected into SIPPs, along with the previous saving that would have gone into cash ISAs.
- 5% real returns after costs is quite high, not implausible, but you should also consider outcomes with lower returns. If you intend the 5% to be nominal return, then it would be better to work in real terms.
- You should consider whether it is possible to transfer the old DC pension into the Royal Mail Scheme or a new pension, and if so, whether that is something that would be sensible if charges and investment options were better.
- You should probably consider where you see the SSISA fitting into things at some point soon
- It is always prudent to check both people's State Pension and ensure you are both on course for a full new State Pension.
- You might want to look into Stoozing given you have no debt and will be keeping the mortgage for 6 years, and perhaps bank switching for yourself and partner to harvest the incentives. Matched Betting can also be a nice sideline if you enjoy that sort of thing.
5 -
Thank you for arranging this is a much easier to view format!
Checked the reddit flowchart and im good there, thats a good point about increasing savings for emergency funds as mortgage gets cleared as that cash isa is our main emergency fund. even though £445 should clear the mortgage I will probably aim for £500 per month so that will build up some extra for emergency's.
The S&S isa I'm not 100% sure on, its for money i want to save longer than I should have in cash but that can have access to before retirement should we wish.
My old DC pension i plan to transfer into my SIPP.
We are both on plan for state pension (im only just though so something to watch)
Matched betting is not for me but I have previously done stoozing so thanks for jogging the memory!
122k mortgage started 10th June 2022. Outstanding balance - 99.7k
Mortgage overpayments in 2022 - £3515
Mortgage overpayments in 2023 - £600
Mortgage overpayments in 2026 - £27001 -
I keep a sum on trading 212 for general use - this is easy access and not in a isa, It's paying 3.8%,
Trading 212 have an instant-access ISA too; is there any reason why you're not using that for your slush fund? While the cash ISA currently pays 3.6%, the SSISA pays 3.8% on cash balances.
I agree with hugheskevi that 5% real growth is an optimistic planning assumption. Some might suggest that 1% or 2% would be more reasonable. I do my planning based on 0% real, ie. barely keeping up with inflation.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
The main reason is i dont want it to eat into my ISA allowance as i know that i will use that money pretty soon (car service in may, 6 monthly service charge June, holiday July ect)
To be honest I had not considered growth vs real growth. I guessed 5% based on long term past performance of the stock markets but did not account for anything else. I thought i was being conservative! But at least the cash isa returns and the debt are fixed for now.
122k mortgage started 10th June 2022. Outstanding balance - 99.7k
Mortgage overpayments in 2022 - £3515
Mortgage overpayments in 2023 - £600
Mortgage overpayments in 2026 - £27000 -
To be honest I had not considered growth vs real growth. I guessed 5% based on long term past performance of the stock markets but did not account for anything else. I thought i was being conservative!
Of course it also depends a lot on what you are invested in. I think historically being invested 100% in equities, with around two thirds in the US , would have brought around 7% on average ( before inflation). However you can expect a lot of volatility and the possibility of a big slump that could last for many years. Most people prefer something a bit less racy, such as the classic 60% equity/40 % bonds. In the long term you will most likely lose out on some growth, but the ride should be less bumpy.
Inflation is also difficult to predict and can be a big issue. Although investment growth over the last 5 years has been healthy, inflation has been around 25%. Hopefully the next 5 years will see a lower figure than that, and that investment growth continues on the same path ( fingers firmly crossed !)
Would either Royal Mail or Tesco add more to your pensions, if you added more ?
1 -
To be honest I had not considered growth vs real growth. I guessed 5% based on long term past performance of the stock markets but did not account for anything else. I thought i was being conservative! But at least the cash isa returns and the debt are fixed for now.
While that is true for the past 10-15 years, we can't be sure of it for the next 10-15.
For exmapl although I have managed a (unitised) average of a little over 7%pa for our pension and S&S investments over the last 11 years, on the way the returns have varied between -7% and +18%. But then there were the 1970's, the Russian stockmarket collapse in the 1990's, the dot-com bust and the financial crisis of 2008, which all caused a dent in returns, and threw a spanner in the works for anyone actually retiring then.
Worth looking up "sequence of returns" and how to mitigate the effects as much as possible as you get nearer to pulling the trigger on retirement.
1 -
Firstly, well done for taking the red pill and starting to work towards a better tomorrow. A lot of people complain about things but never put the effort in to get anywhere!
Six years ago, when I was 43, I had less than £80k in an ISA and pensions combined, now I have just shy of £275k total.
My goal is not to pay off my house however, but to retire as early as possible. Which is why at 43 I actually increased my mortgage term from 8 years back up to 25 years again, to lower my monthly payment, and to allow me to invest the difference.
I pay into my works pension, and (currently) am putting £500 a month into a globally diverse fund within my stocks and shares ISA with Vanguard.
I am not overly concerned about the volatility of the stock market, as I have a lot of leeway as to when I pull the trigger, and how much I will withdraw during good and bad times etc.
I am not suggesting that you extend your term, but if you are prepared to be a bit more flexible about when you pay the mortgage off / retire, you may want to take a second look at the stocks and shares ISA.
Food for thought if nothing else! : )
Think first of your goal, then make it happen!3 -
Yes thats true, I will be 100% equities for the next ten years minimum, and then will probably start adding some targeted retirement funds, but I am willing to take the higher risk route for higher potential returns. When I say equities i should be clear and say its 90% funds and ETFs, with a higher weighting to Europe and the UK than a standard all world fund. Honestly I'm not keen on how the US has so much of its value in a few tech stocks and so I'm taking a slightly different route than just lumping everything into WVRP as seems to be recommended alot!
No scope to increase workplace pension contributions sadly.
Yeah that's true, never know what's round the corner. I think for this reason its good to have a bit of cash too… I will look into that, thanks!
Thank you, and wow that's some amazing progress! That's a fair point on the early retirement, because our mortgage monthly payments are so low (558 a month) clearing it wont have the effect it will for some people, but its a mental thing I guess - the Standard Variable rate for nationwide currently is 6.49%, I think at those levels I will just want to clear it rather than pay for another mortgage deal - but nothings off the table, its something I will certainly consider when the time comes.
122k mortgage started 10th June 2022. Outstanding balance - 99.7k
Mortgage overpayments in 2022 - £3515
Mortgage overpayments in 2023 - £600
Mortgage overpayments in 2026 - £27000 -
Since I'm on weekly pay Fridays is the day i add money somewhere, this week the cash isa has a £500 contribution.
Total side hustle earning this tax year - £21.90
Total ISA contributions this tax year - £1015
(trading 212 S&S ISA - 515, HL cash ISA - £500)
122k mortgage started 10th June 2022. Outstanding balance - 99.7k
Mortgage overpayments in 2022 - £3515
Mortgage overpayments in 2023 - £600
Mortgage overpayments in 2026 - £27001









Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards