We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Pension consultation



Hi, we have been informed at work that there is going to be a change in our pensions and that this will be changed to a net pension scheme, and asking if we want to opt out of this. At the present time our contributions go in from our gross pay. This is due to the national minimum wage increasing and breaches that may happen and for anyone earning under £16.29 per hour.
I have attended on line meetings regarding this, by I cannot pretend to understand what anyone is saying and feel slightly stupid.
Is it beneficial to stay in the scheme or opt out? If I opt out of the scheme will the employer also stop their contributions.
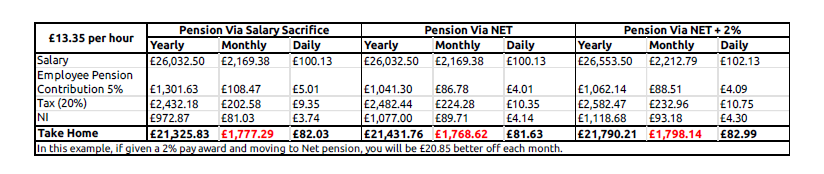
They have given an example of what would happen if we were given a 2% pay rise, and advise that we would be better off. Is this sugar coating what they are doing?
What would be my options if I decided to opt out and pay directly into an existing pension each month.
Any help gratefully appreciated.
Comments
-
The question is, does "opt out" mean to opt out of the Net scheme (and stay in the gross scheme), or to opt out of the new net pension altogether?
I don't think anyone will be advising the second option!
Do you have any info (redacted to avoid any identifiable information) that you can post about the specifics of the switch which you were given, or was it all verbal?
• The rich buy assets.
• The poor only have expenses.
• The middle class buy liabilities they think are assets.1 -
Have the words 'salary sacrifice ' featured in this process?
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!2 -
So it sounds like your pension was salary sacrifice which is not allowed to take your pay below minimum wage - sal sac is the only pension method that is affected by minimum wage rules as you exchange salary for employer contributions, technically you are not making any pension contributions - they are all employer. With sal sac you save on the tax and NI. Net pay is still taken from your gross pay, the real difference is that you now have to pay the NI. Why would you opt out and take an effective pay cut of the employer contributions ? They will not pay them if you are not in the scheme. There could be some confusion over terminology though as "net pay" could actually mean relief at source which is taken from net pay which saves you no tax in your pay packet but instead has a basic rate tax credit applied by the pension provider and higher rate tax payers have to make a claim from HMRC for that tax refund.
Never associate with idiots on their own level, because, being an intelligent man, you'll try to deal with them on their level - and on their level they'll beat you every time.
Being hated by idiots is the price you pay for not being one of them.
Jean Cocteau 1889-1963
3 -
Is it beneficial to stay in the scheme or opt out? Opting out of free money would be a bit crazy .
If I opt out of the scheme will the employer also stop their contributions. They would .
2 -
Do you mean that currently your employer offers members of the workplace pension scheme the choice of salary sacrifice in respect of contributions but is now withdrawing the opportunity to make this choice on the grounds that certain issues arise in respect of NMW?
If so, in future, will the scheme use net pay or relief at source?
If you opt out of your workplace pension scheme in favour of making your own contribution to a personal pension, you will lose the employer's contribution (in effect take a pay cut), UNLESS your employer is willing to contribute to your personal plan (unlikely).
1 -
Hi @Marcon, yes it does.
0 -
Hi @vacheron
I believe, if I am reading it correctly, they are saying opt out of the new pension all together.
They are also using an example of a 2% pay rise making us "better off". This in itself seems a ridiculous thing to say as a 2% pay rise isn't going to make us worse off. However, it is not a given that we will receive a 2% pay rise as I didn't last year.
I don't find this sort of thing easy to understand, so is causing me a small amount of anxiety 🙄
0 -
Is it not misleading to include an example of a 'X% pay award' showing you as better off (duh), but specifically just applying it to only the scenario they want you to move to? Why would they not apply it to both scenarios as a fair comparison (rhetorical question, it's obvious why)… why show that at all (again rhetorical question, obviously it's because they need to convince everyone to agree to be a tenner worse off a month by their own calculations).
I'm not getting warm vibes from this so far!
Know what you don't1 -
Hi @Exodi
Thank you for your response. So basically, its a heads they win, tails we lose situation. It's not so much a consultation but something we either agree to or lose their contribution?
I feel that I am understanding this better now, but also that my initial feelings were correct (that this is not a benefit for us)
0 -
Well as I understand it (happy to be corrected) if you are in an employment pension scheme of any sort then your employer is obliged to contribute towards that. And as far as I'm aware (again someone correct me if I'm wrong) if you say you want to remain in salary sacrifice they cannot refuse you a pay increase for that specific reason (they might come up with several others of course).
And if you are in a salary sacrifice situation they save money as well as you do - some on tax but mostly (as I understand it) on NI contributions. So ignoring the 2% pay rise red herring you appear to be better off remaining in a salary sacrifice situation.
I’m a Forum Ambassador and I support the Forum Team on Debt Free Wannabe, Old Style Money Saving and Pensions boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com. All views are my own and not the official line of MoneySavingExpert.
Click on this link for a Statement of Accounts that can be posted on the DebtFree Wannabe board: https://lemonfool.co.uk/financecalculators/soa.php
Check your state pension on: Check your State Pension forecast - GOV.UK
"Never retract, never explain, never apologise; get things done and let them howl.” Nellie McClung
⭐️🏅😇🏅🏅🏅🏅🏅🏅1












Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards