We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Applying for pension - quick question
Comments
-
I suspect everyone gets the same form whether they are caught by the LSA or not. For some people the answer may trigger another form to fill in.
0 -
Just on tax codes does she currently have a job with a tax code attached? If not then when HMRC gets the two pension schemes reporting a start to her pensions I wonder what they will do about her tax codes. You probably don't want them allocating 1257L to one pension and BR to the other. You may want to check her personal tax account soon after the pensions start to see what HMRC have done and see if you can get them to allocate her personal allowance across both pensions.
1 -
So no-one seems to know why they need to ask the question?
It's that splendid answer: because HMRC says so!
Part of it is to do with monitoring the Lump Sum Allowance, and ensuring that if someone has taken their full tax-free £268,275, a provider doesn't inadvertently dole out more tax free cash to which the individual isn't entitled.
There is also a requirement for a scheme member who has 'flexibly accessed' their DC pot to notify the administrators of any other pension scheme of which they are a member that they've done so. Failure to do so within 91 days means the member could be fined by HMRC. It matters because once you've triggered the Money Purchase Annual Allowance, DC schemes need to monitor future contributions to avoid excess contributions being paid.
Not to mention the little matter of possible recycling…
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!2 -
I think they have to ask it. Someone may not realise that a lump sum from another pension might reduce what they can take.
0 -
There is also a requirement for a scheme member who has 'flexibly accessed' their DC pot to notify the administrators of any other pension scheme of which they are a member that they've done so.
Does that include if the "other pension" is a DB in payment, or is this only for other DCs?
0 -
HMRC can fine you for not answering a question that is asked without any context/reason being given at all?
This is how the question is asked:
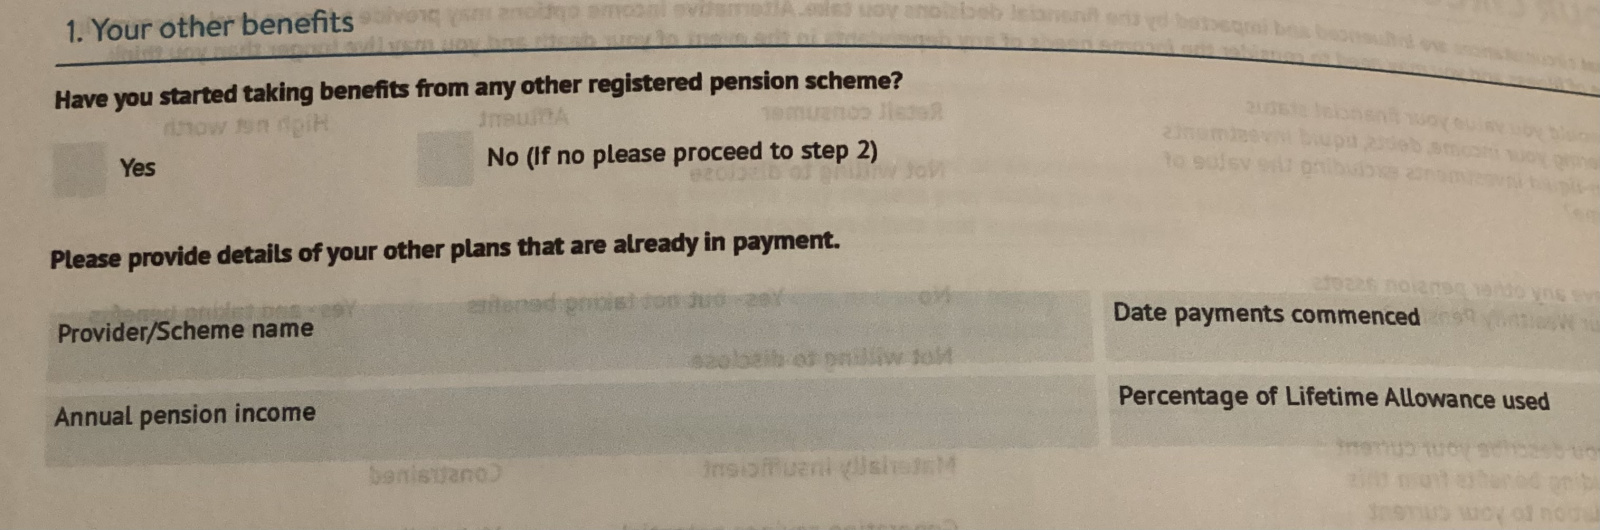
As Mrs GenX is applying for her DB pension and SIPP at the same time there doesn't seem any other way to answer except to say 'No' as neither pension is in payment and the question re LA can't be answered yet.
None of the forms I have seen make any reference to 91 days whatsoever or having to inform other pension providers.
0 -
I've answered what you asked: why is the provider asking the question. I didn't say you would be fined for not answering it; I pointed out that someone could be fined for not taking action once they have flexibly accessed their benefits. Your wife hasn't yet done that, so hasn't had formal notification from her DC provider that she's done so. That notification will include confirmation she needs to advise other schemes accordingly. Chapter and verse here if interested:
As Mrs GenX is applying for her DB pension and SIPP at the same time there doesn't seem any other way to answer except to say 'No' as neither pension is in payment and the question re LA can't be answered yet.
Nothing sacred about forms. Simply add a note saying that's what's happening.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0 -
There is also a requirement for a scheme member who has 'flexibly accessed' their DC pot to notify the administrators of any other pension scheme of which they are a member that they've done so. Failure to do so within 91 days means the member could be fined by HMRC. It matters because once you've triggered the Money Purchase Annual Allowance, DC schemes need to monitor future contributions to avoid excess contributions being paid.
I am pretty sure that is the first time that this 91 days requirement has ever been mentioned on this forum. Every day is a schoolday with pensions!
I accessed some of a crystallised DC pot for the first time quite recently. For sure there were warnings about MPAA, but I do not recall any warning that I had to inform the providers of any other DC pots that I have. I suppose it is possible something was said but as I do not intend to make any more pension contributions in my lifetime, I just ignored it. However I do not recall seeing anything about it.
I can see the logic, but I suspect in practice not many people will do this, or be aware that they should do .
1











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards