We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Getting the money!
Comments
-
Thanks, but no, I'm not being scammed. Repairs are required.
1 -
As above , some DC pension providers will not accept a DB transfer without expensive financial advisor advice, whatever its value.
0 -
So… £22895.03 DB pot, you need a lump sum, you have other means of support, don't see any need for the future DB income and are willing to lose it.
Defined Benefit puts the risk on the provider whereas a SIPP loads the risk on the individual (until and unless you buy an annuity). Sometimes pensions (both DB and DC) come with guarantees that aren't necessarily reflected in transfer values too. So keeping a DB is usually best for most people - but not all and even less so when they are small. Anyway…
As others have said, you could transfer it to a SIPP provider. Choose one with a fee structure you are comfortable with for the time you expect to use it. Check for instant wins (cash-back on transfers, check topcashback/quidco, ask for referral links). Make a transfer-in request with the SIPP provider, whole pot, as cash. That shouldn't take more than a couple of weeks (it's never guaranteed but cash only should be straightforward) - it probably depends on the DB provider more than the SIPP provider but it's the SIPP provider that drives the process so keep asking for updates if it seems stalled.
Once the transfer is complete make a request to go into drawdown taking the full 25% tax free cash (£5723) but no non-tax free income (unless you need it all). Many providers let you do that online. Since it's all in cash that should be reasonably quick too, another couple of weeks maybe. The remaining £17171 stays in your SIPP and still counts as a pension so can grow tax-free. You can also add more to it if you want.
If you need some of the taxable cash be warned that the tax man will adjust your tax code on the assumption that it's going to be regular monthly income. So take £1 of the taxable first, let the SIPP provider do the HMRC notifications and they'll get a tax code to use for you. Then you can request further lump sums or regular income. Check how your provider handles it - regular income requests are usually monthly, lump sum requests may or may not be more immediate. If you can't wait skip the £1 step and take what you need - you can ask HMRC to re-adjust your tax code after they've messed it up but it's a bit of a faff.
And finally… if you leave anything at all in your SIPP remember to do something with it. Buy something like a global growth & income and/or a global bond fund if nothing else. Cash is guaranteed to get eaten by inflation, funds have at least a chance of gains (even if it doesn't look like it at the moment).
2 -
There's a knee jerk reaction on this forum whenever someone mentions transferring out a DB pension scheme: 'don't do it'. That reaction is very often correct, because the person posting doesn't understand what they are giving up, or the risks of having a defined contribution scheme instread.
However, such a 'blanket ban' overlooks the fact that sometimes it is the only option, even if financially it's not a great one. The cost of not sorting out serious issues with a roof are likely to far outweigh the modest future pension given up (and with a transfer value of that level, it'll be a very modest pension, even if it does increase in payment). You've recognised that you'll be taxed on 75% of the amount transferred when you withdraw it, and someone else has pointed out that you'll almost certainly need to reclaim overpaid tax from HMRC. See and make sure you use the right form!
Then last time I saw someone transfer their DB pension was to fund hip replacements for themself and their spouse - both were in intolerable pain and the waiting list was upwards of 6 months. Quality of life was transformed within a couple of weeks for both of them.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!5 -
I really appreciate everyone's input here, you've all been brilliant, thank you.
2 -
Well, this is going swimmingly!
So, I opened an HL account and they're happy to take the transfer. I've filled on loads of forms, and was asked by the company currently holding the pension (I'll just term as P) to provide the name of an HL SIPP I was going to transfer to.
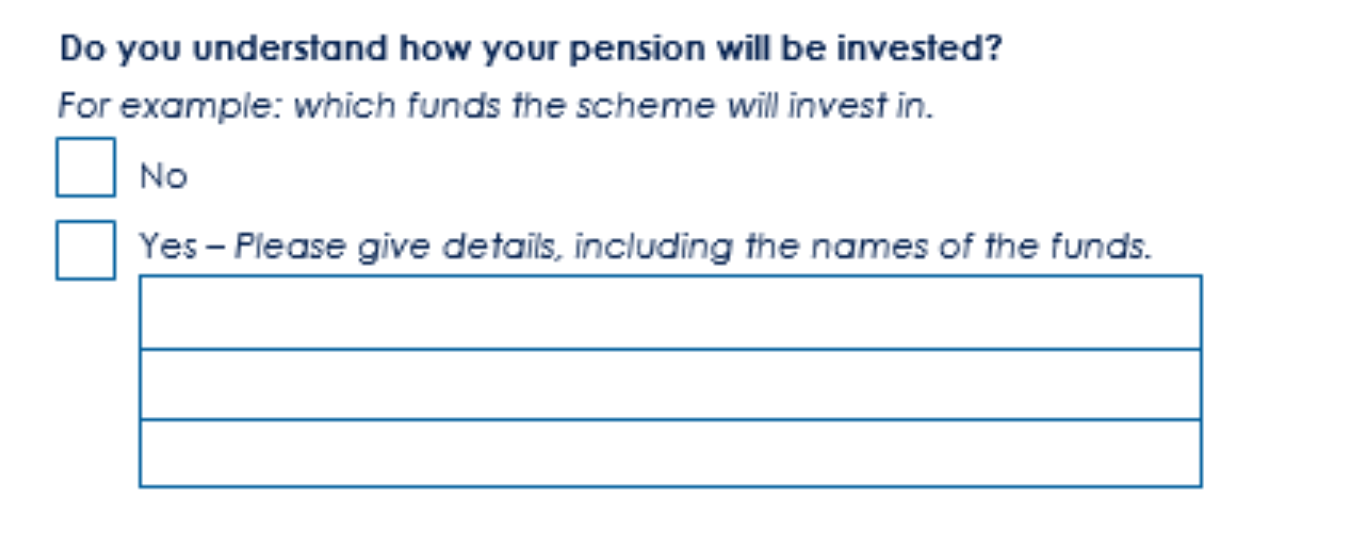
I selected the HL MULTI-INDEX CAUTIOUS (CLASS D) and then receiving this from P:
"We note that the funds you are investing in include overseas funds.
As this raises an amber flag, before the transfer of your benefits can proceed, you must attend a free Pension Safeguarding Guidance appointment with MoneyHelper."
So, I'm now stuck until I have that appointment, first available space 21st may or come up with the name of an HL fund that doesn't include overseas fund investment. In the meantime the transfer value has gone down by over £1.5k and my quote for my essential repairs is now outdated and will cost more.
Is there a particular HL fund I should be looking at? I thought it was a cash transfer and that I choose what I want to do with it once transferred. This is what I need to get right:
 0
-
the transfer is cash but you have then told them that you will invest in that fund. They seem to have criteria around overseas funds being slightly concerning so they are insisting that you get a bit of free guidance so that you understand what you are doing. This does come up with some providers.
I’m a Senior Forum Ambassador and I support the Forum Team on the Pensions, Annuities & Retirement Planning, Loans
& Credit Cards boards. If you need any help on these boards, do let me know. Please note that Ambassadors are not moderators. Any posts you spot in breach of the Forum Rules should be reported via the report button, or by emailing forumteam@moneysavingexpert.com.
All views are my own and not the official line of MoneySavingExpert.0 -
You wait 11 days for your appointment. Start faffing around and trying to change things now and the transfer is likely to be delayed for longer than that.
In the meantime the transfer value has gone down by over £1.5k and my quote for my essential repairs is now outdated and will cost more.
DB transfer values don't drop if you accept during the guarantee period (3 months from the date of calculation), so it sounds as if your transfer value was already out of date when you started the process and the scheme provided a new one - is that correct? If so, it's fixed now you've accepted it and waiting for less than a fortnight won't change anything.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0 -
Transfer value when I asked for one 1st March was £22,895. I confirmed I was transferring it 3rd April and the amount was given to me as £22,895. Transfer value on latest documentation give to me 20 April is showing £21,832.
0 -
Do you have a defined contribution AVC as part of your DB pension? If not, that sounds a bit odd. You are within a year of your scheme's Normal Retirement Age so this is classed as a 'non-statutory transfer' (ie different rules from statutory transfers) but even so, I wouldn't expect the scheme to be constantly recalculating. Might be asking them to confirm.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0










Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.3K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.8K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards