We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
HMRC Tax Confident Website


I have just come across the above-mentioned HMRC Website which aims to help people understand the tax system.
Since I’m retired I was intrigued to see a specific section entitled ‘Savings, investments and tax in retirement’. I tried to post a link the website but it won’t let me because I haven’t posted to this Forum before.
On reading the content it seems that HMRC do not understand the provisions of their own regulations governing Starting Rate for Savings. This is not the first time I have encountered this issue because I have had problems in the past trying to explain the rules of Starting Rate for Savings to HMRC staff. Furthermore, I know that Martin Lewis has written extensively about this specific tax regulation to make people aware of its existence but it’s in vain if even HMRC staff are totally incapable of understanding it.
At the link above, HMRC give an example of an individual, Alan, who is retired with an income from a state pension, a small private pension and some interest from savings. In their example Alan has a basic tax allowance of £12570 and receives £14000 in pension income as well as £1500 in interest from savings. They then correctly explain that he must pay tax on £1430 of his pension income (i.e. 14000-12570). They then go on to state that because his savings interest is in excess of his £1000 personal savings allowance then he must pay tax on £500 of his savings interest.
Surely this is incorrect? Since Alan’s non-savings income is less than £17570 he is entitled to take advantage of the Starting Rate for Savings. Of course, he is not eligible for the full £5000 allowance because his non-savings income is more than £12570. However, I calculate that he should get a starting rate personal savings allowance of £3570 (17570-14000). Since he is also still eligible for the standard personal savings allowance of £1000 then I calculate he should not pay tax on his savings interest until it exceeds £4570.
Am I correct in my calculations or am I the one who doesn’t understand the rules governing Starting Rate for Savings?
Comments
-
EDIT
I’ve able to post the link by putting quotation marks around it but you’ll need to remove the quotation marks to follow the link
https://taxconfident.campaign.gov.uk/tax-in-retirement/savings-investments-tax
1 -
You couldn't make it up. But HMRC appear to have managed it 😳
3 -
You are correct and the HMRC info is wrong.
Luckily 'Alan' will not pay tax on his savings interest, because at least the HMRC computer knows how to apply the Savings Starter Rate correctly.
2 -
I’m glad to hear that at least two people agree with me. I just hope that the HMRC computers have been programmed by a staff member who understands the Starting Rate for Savings rules.
0 -
Another example is the very muddled wording and misleading graphic here.
They define larger gift as a gift of more than the £3,000 annual gift exemption (and not covered by the wedding or small gifts exemptions).
Here is the misleading graphic for example
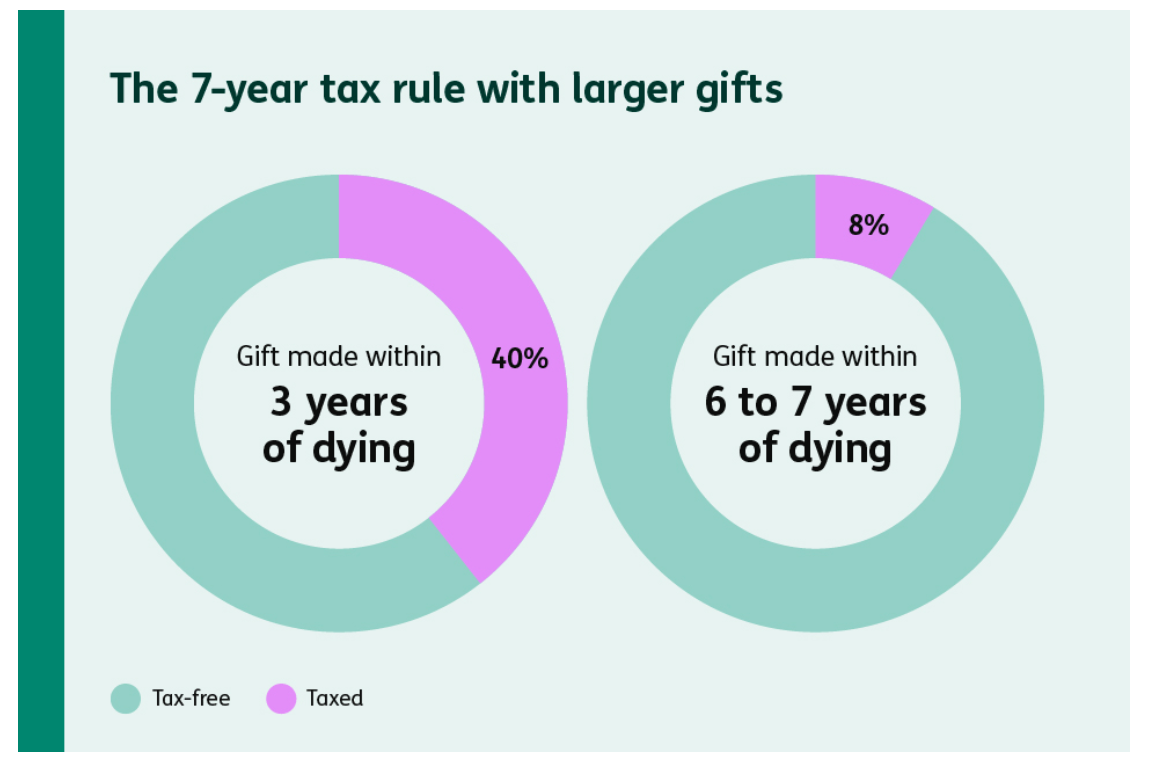
Would someone making a gift of say £330,000 between 6 and 7 years before death (and having an estate of say £500,000 excluding the gift on death) understand how the tax free threshold, taper relief and inheritance tax interact from that wording and graphic?And would someone making a £40,000 gift (i.e. a larger gift by their definitions) between 6 and 7 years before death (who had an estate excluding the gift of £400,000 on death) be able to reconcile the wording with the graphic, given £40,000 is a larger gift by their definition?
And if other large gifts are made within 7 years of death would someone understand how things work from that section?
This is the main gov.uk explanation which is by contrast decently set out and worded
I came, I saw, I melted0 -
No wonder so many people are confused about gifting rules, taper relief etc !
2 -
After posting my first comment in this thread, I looked at the HMRC Facebook page and found that I was able to contact HMRC using Facebook Messenger. So, I sent them a message pointing out their mistake but I’ve had no response.
However, I have just checked the HMRC Tax Confident website and they have now corrected their mistake by changing ‘Alan’s’ total pension income to £18000 instead of £14000. Of course, he is then no longer be able to claim a Starting Rate for Savings Allowance. They then point out that if his total pension income had been less than £17570 he ‘would have been eligible to use something called the Starting Rate for Savings’. I’ve no idea if my message prompted their correction or if it came from another source.2 -
I certainly don't want to do it but what if someone wanted to gift 500k of his 2 million to a relative and only had one year to live, to circumvent the rules he bought his relatives beat up Ford Cortina for 500k and exactly a year later popped his clogs?
Butt Spelle Chequers Two Khan Make Awe Full Miss Steaks0 -
The clogs are now worth 750k each.
1








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards