Ready, steady… save!
You don’t need a chart to join in. Here are 2 ways to record your savings:
1. Cross it off
Pop a chart into your first post. Saved an amount? Cross it out! Read more »
£0.01 £0.02 £0.03
2. Write it down
Skip the chart and add updates to your first post. Read more »
“Another +£3 saved today. Go me!”
Use +£ before each new saving so it counts towards your total.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
Short Term Money Market Fund



Folks
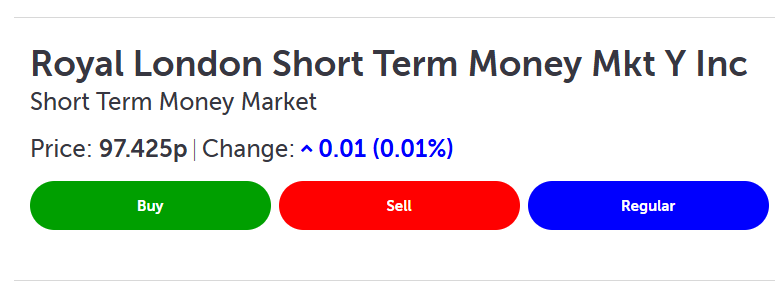
Put me right here please. I noted the below on Bell as a possible alternative to setting up a gilt ladder to preserve what I have in the SIPP. Couple of Qs.
What is the risk compared with gilts?
It seems I may receive a wee bit of growth? Is this right?
The primary aim is to preserve what I have in the SIPP until SP kicks in some 6 years down the line. Is the below a viable alternative in this respect?
Comments
-
You will get a return rate very close to the Bank of England base rate. So normally a bit better than just keeping cash in your SIPP.
The risk is minimal, especially with a large company like Royal London.
1 -
The only real risk is that interest rates fall below the coupon rate of whichever Gilts.
Looking at 2027, 28 and 29, they are all hovering around 3% real yield, taking into account the dirty prices. So for the next year at least, a STMM fund ‘wins’ and you don’t have the risk of losing money if you have Gilts and need to sell them before maturity.
The other consideration is Index linked Gilts, far more expensive, hardly any coupon payments but you are covered in the event of inflation spiking1 -
What is the risk compared with gilts?
shortfall risk and inflation risk and variable rate of return that is likely to head lower over the next 12 months.
Its a great fund for money needed in the short term or a defensive diversifier but it doesn't work well with a gilt ladder beyond the short term bucket.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.2 -
I was considering an IL gilt ladder held to maturity for each year so perhaps inflation is covered. Can you elaborate on your last phrase? Doesn't work well? Is a gilt ladder a better option for the 6 years?
0 -
If you are buying gilts to maturity, you know what you are going to get and can map it out over time. With STMM you do not know what you are going to get.
When using drawdown, a popular strategy is to have buckets covering different times. Platform cash and STMM is good for the short term bucket. So, if you had 3-5 years of cash/STMM, you can then use gilts for 6 years onwards.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1 -
What is the risk compared with gilts?
As well as the interest rate risk, there's the risk that Royal London lend your money to a bunch of businesses that go bust and can't pay it back.
That's not an especially likely outcome, but if we were to have a sudden collapse in the economy (maybe a bubble bursts) then it could come to pass.
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.0 -
With gilts you're lending to one "company" and if they default.. sure hasn't happen to UK but if there's some big crash that's always a possibility.
I see short term money markets as very safe, they come with diversification (many companies, many countries) and all short debts like couple of months..
RL Short Term Money Market was launched in 2012 and always brought positive return (with exception of small daily changes).
But the main key is as mentioned earlier - 6 years gilts you know what you get, with MM of the rates drop to 1% they will follow.
0 -
All understood - I think - and many thanks.
0








Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.8K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.2K Spending & Discounts
- 248.4K Work, Benefits & Business
- 606K Mortgages, Homes & Bills
- 179K Life & Family
- 263.9K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards