We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Aegon s.32 Buyout Plan
Comments
-
Good morning All
I have just started looking at my policy, has anyone actually accessed their enhanced tax free cash, how can they keep changing the rules years later.
Any help with options would be. Appreciated0 -
I am trying to transfer a very old Aegon plan which has Protected Enhanced Tax Free Cash to ii.
They (ii) are saying that I must get a Financial Advice Declaration form signed by my financial advisor.
He is refusing to do so. Yes I have paid him.
He says PETFC is not a safeguarded right.
Regards Mike0 -
You've already posted about this
and received very helpful replies, so not sure what you're hoping for by resurrecting this very old thread and repeating the same issue?
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
None of the earlier replies have given any hints on how to get past the impasse where ii are insisting that the FAD form needs to be signed and my advisor is refusing to sign it saying it's not required.
Regards Mike0 -
On the contrary - one of the first replies (from an experienced IFA) explained exactly what you needed to do:
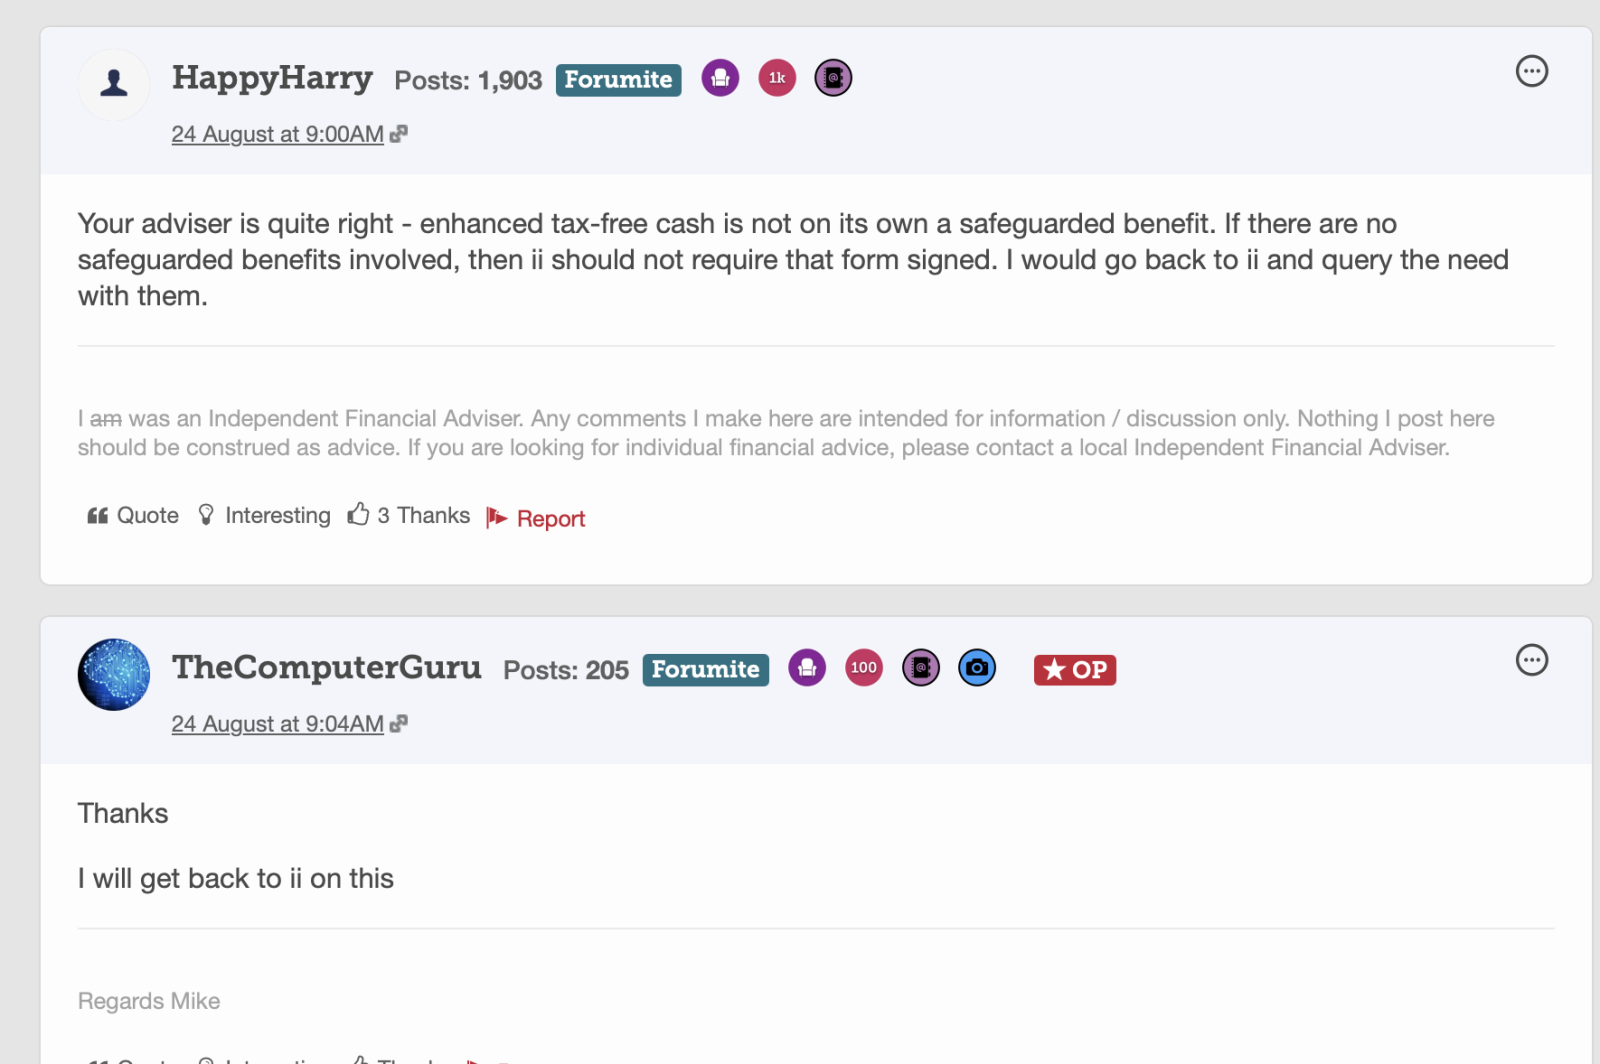
Are you saying that ii are continuing to insist the form needs to be signed? If so, you need to go down the formal complaints route.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0 -
Are you sure that there isn't any safeguarded benefits? Many Aegon S32 plans have GARs and/or GMP. Both of which would trigger the need for advice.
If Aegon have confirmed in writing that there are no safeguarded benefits, then your problem is with ii. Not Aegon or anyone else. You would raise a complaint with ii. However, technically, providers are allowed to make commercial decisions which go beyond regulatory or legal requirements. So, if they insist on advice, then you just need a better provider.
I am an Independent Financial Adviser (IFA). The comments I make are just my opinion and are for discussion purposes only. They are not financial advice and you should not treat them as such. If you feel an area discussed may be relevant to you, then please seek advice from an Independent Financial Adviser local to you.1 -
However, technically, providers are allowed to make commercial decisions which go beyond regulatory or legal requirements. So, if they insist on advice, then you just need a better provider.
Indeed - unless they are a stakeholder pension - but what a provider shouldn't do is claim something is a S48 requirement if it isn't.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!0 -
This thread has peaked my interest again. I have just asked Aegon to confirm if my pension has any safeguarded benefits. Assuming the answer is no (based on comments from various folk above), I will ask my SIPP provider, ii, to see if they might execute the transfer without the IFA advice.
If I hit the inevitable brick wall, I still reserve the right to access my Protected Enhanced Tax Free Cash using a Fixed Term Annuity.
0 -
I have just asked Aegon to confirm if my pension has any safeguarded benefits.
If Aegon says that you do have safeguarded benefits, ask them to confirm exactly what those safeguarded benefits are. If they come back and tell you the PTFC is a safeguarded benefit, make a formal complaint and ask them to cite a legislative or regulatory reference to support this view.
Assuming the answer is no (based on comments from various folk above), I will ask my SIPP provider, ii, to see if they might execute the transfer without the IFA advice.
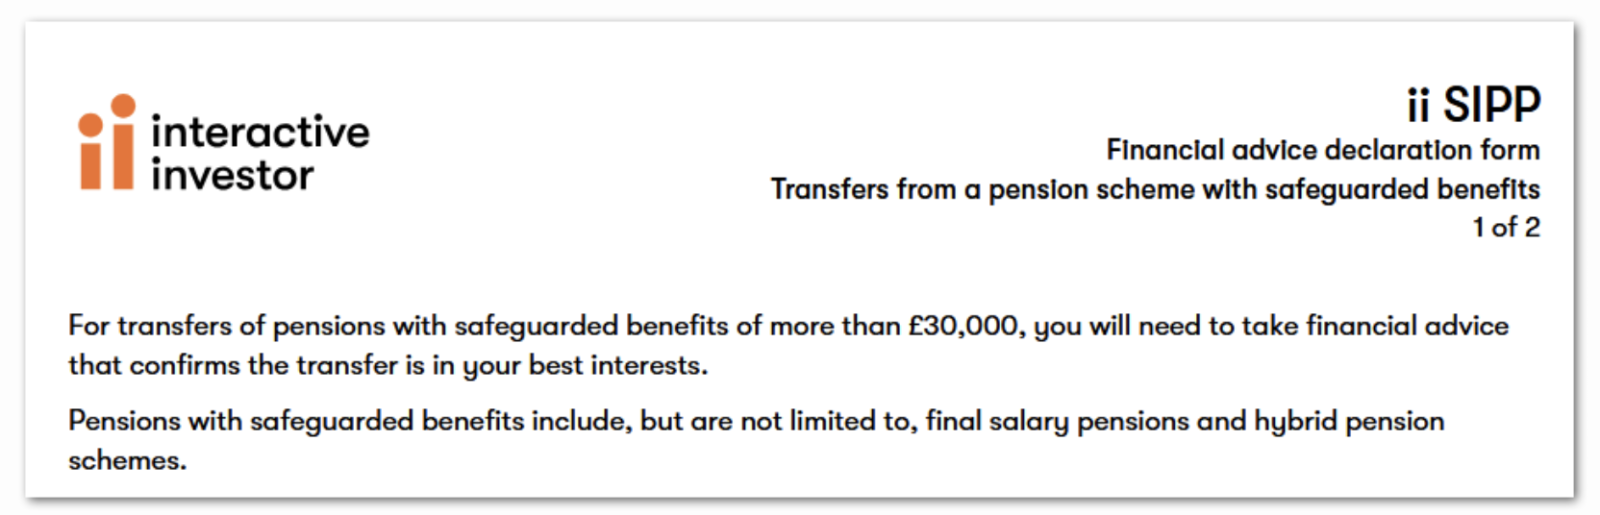
If Aegon confirm there are no safeguarded benefits, you've then got that in writing to give to ii if they try to insist on a S48 certificate. Although any potential receiving scheme (other than a stakeholder pension) can impose any rules it likes, or simply decline a transfer without giving any reason, from what @TheComputerGuru cited, ii only appears to be seeking to impose an advice requirement where there are safeguarded benefits and a transfer value of £30,000+:
If I hit the inevitable brick wall, I still reserve the right to access my Protected Enhanced Tax Free Cash using a Fixed Term Annuity.
Keep in mind that a fixed term annuity (as opposed to a lifetime annuity) constitutes 'flexibly accessing' your benefits.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!2 -
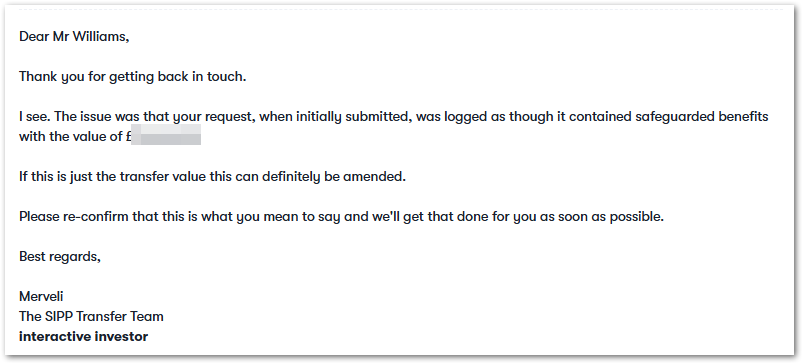
I found out yesterday that my issue was primarily caused by me filling in the ii transfer request form incorrectly.
🙈🙉🙊
Hopefully all will go smoothly from here on …
Regards Mike3











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.6K Banking & Borrowing
- 254.8K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.2K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.1K Discuss & Feedback
- 37.7K Read-Only Boards