We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
Pension mis-selling in the 90s
Comments
-
What are the relevant time limits for making a pension-misselling complaint for a DB to personal pension transfer in the 1990s frenzy?
What level of documentation is needed for a successful claim, if there is a case of compensation?
Thus the old Gentleman ended his Harangue. The People heard it, and approved the Doctrine, and immediately practised the Contrary, just as if it had been a common Sermon; for the Vendue opened ...THE WAY TO WEALTH, Benjamin Franklin, 1758 AD0 -
Be aware that very many cases were reviewed automatically:
In October 1994, the Securities and Investments Board (SIB) recommended that financial advisers review all cases where, on the basis of advice given between 29 April 1988 and 30 June 1994 inclusive, individuals had transferred from, opted out of or failed to join an occupational pension scheme and had instead taken out a personal pension scheme, buy-out contract or retirement annuity contract. The purpose of the review was to identify any cases where the customer had been disadvantaged by taking this action.
Assuming the case hasn't already been reviewed (you don't get a second bite at the cherry if so), then see:
The onus will be on you to prove that you were given unsuitable advice, so you will need all the documentation you can lay hands on to support that case - and a VERY good reason to persuade FOS that at no point during the last 30 years could you have wondered if you had a problem. That isn't easy to do.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!1 -
Since this thread's been bumped, I'm wondering how it all turned out for Mrs @NSG666 in the end. The OP never told us, as far as I can tell from a cursory review of their posts.
Back in 2021 they wrote:
As of today the personal pension pot is £54,186
…
£247/month lost [at age 60] by taking out the PP rather than the DB scheme.
We don't know how they were invested, but from October 2021 to October 2025, VLS60 was up by 20%. So perhaps when Mrs NSG666 got to age 55 they might've had £65k in the pot.
And I just so happen to have a saved screenshot from HL's annuity best buy table from October 2025.
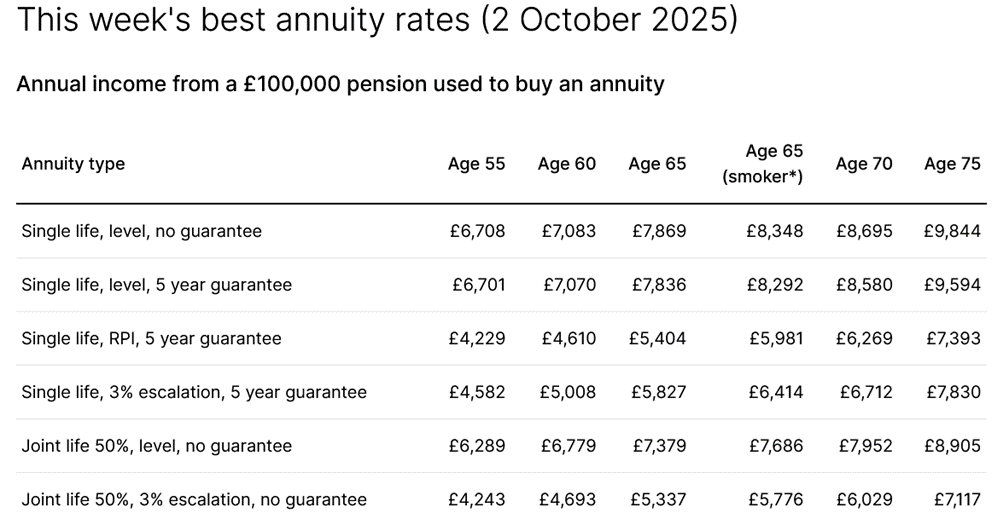
So £65k would have bought the 55-yo Mrs NSG666 £2750/yr (£229/month) as an RPI-linked single-life annuity.
The OP also said that the scheme pension was reduced by 20% (to 80%) by an ERF when taken at 55. So the £247/mo shortfall at age 60 would have been equivalent to £198/mo at age 55.
They might not have been so hard done by after all?
N. Hampshire, he/him. Octopus Intelligent Go elec / Fuse gas / Vodafone BB / iD mobile. Kirk Hill Co-op member.Economy 7 cap explainer. Gas vs E7 vs peak elec heating costs, Ecoflow Stream, Best kettle :-)
2.72kWp PV facing SSW installed Jan 2012. 11 x 247w panels, 3.6kw inverter. 37 MWh generated, long-term average 2.6 Os.3 -
Although far too many people were indeed mis-sold, there were many others who wanted to go ahead regardless of any advice - not much different from the situation a couple of years ago, although back then advice wasn't mandatory however hefty the CETV.
Unfortunately there are far too many claims management outfits still plugging the notion that anyone can claim for anything, anytime, often quoting hugely unrealistic success rates and suggesting that people 'couldn't have known' there was an issue until they got to the point of retirement. Funnily enough that's not an argument which sways FOS too often, given the vast amount of publicity surrounding the whole issue back in the 1990s and since.
Googling on your question might have been both quicker and easier, if you're only after simple facts rather than opinions!2 -
Back in the day, pensions 'advisors' were even advising members of the (notionally) non-contributory Armed Forces Pension Scheme to opt out and join their schemes instead. Although the rules did allow for transfers out at that time, my Unit had their own 'advisory system'.
Stage 1 would be the pay clerk telling them that if they did opt out, then their take home pay would drop, as they would have to pay more NI. This stopped most of them in their tracks.
But there's always the stroppy ones - who were referred to our old school Warrant Officer for their 'advisory interview'. Cue a couple of minutes during which the windows of Station HQ rattled with the force of the WOs advice. ie, "Don't be so effing stupid, get out of my effing office". Or words to that effect.
No-one from my Unit opted/transferred out.
4 -
The onus will be on you to …
Not on me. On the former scheme member.
(For the avoidance of doubt)
Thus the old Gentleman ended his Harangue. The People heard it, and approved the Doctrine, and immediately practised the Contrary, just as if it had been a common Sermon; for the Vendue opened ...THE WAY TO WEALTH, Benjamin Franklin, 1758 AD0 -
To be fair, CETVs then had got to almost silly levels, and for anyone with a reasonably good grasp of DIY, they could well have been a good trade off versus the annual pension they offered. Mine was nearly 50x at one point.
That said, can't argue with the compo culture that's allowed these ambulance chasing firms to operate though… does unfortunately create a bit of a nanny state approach to regulation, but what can you do when there are stroppy uninformed idiots that will sue at the drop of a hat.
0











Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards