We’d like to remind Forumites to please avoid political debate on the Forum.
This is to keep it a safe and useful space for MoneySaving discussions. Threads that are – or become – political in nature may be removed in line with the Forum’s rules. Thank you for your understanding.
📨 Have you signed up to the Forum's new Email Digest yet? Get a selection of trending threads sent straight to your inbox daily, weekly or monthly!
3 year plan to get debt free

[Deleted User]
Posts: 0

 Newbie
Hello!
After reading a few threads here and lots of articles on the MSE webiste I decided to start my own DFW thread/diary.
I have been paying more than minimum on all CCs since spring last year when nurseries closed and then m youngest started school in Sept (no more £1k+pm going on childcare!), but my defnite LBM was in November when I decided to spend no more than £100 weekly. It didn't always work out, we had some unexpected expenses and no emergency fund, but I was able to pay for them without using any credit. I just paid very little on CCs some months.
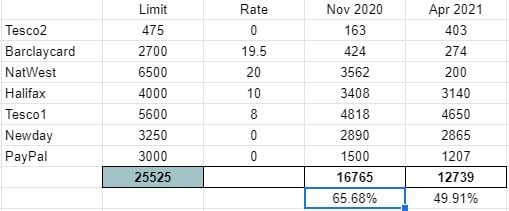
These are the credit cards balances now vs Nov and I also had a £700 overdraft which has been covered. I am happy I started logging, it is encouranging to see progress.
We also have a mortgage and a car on HP which is accounted for in the bills budget.
The biggest debt which we have to get rid of is a secured Oplo - £43k for 10 years, 8% in the first 5 years, £548 monthly. The plan is to pay it off in less than 2 years as in 2023 our mortgage fixed rate term ends. Our LTV (taking into account the main mortgage only) will be just under 80% which should mean a better rate.
We used the Oplo to cover 2 expensive NatWest loans, one each for my partner and I. This freed up some cash to pay off other cards in the meantime.
I have about £1100 monthly after bills and spending budget, this is if nothing major comes up. This month I am getting a bonus so I will have double the amount, but I don;t expect this to happen again this year.
I don't think we can pay off Oplo without consolidating?
This is my plan for the next few months:
- pay Barclaycard and Natwest this month (payday 28th)
- pay NewDay and Paypal by August when the 0% rate ends
- move Halifax and/or Tesco to a 0% BT when I get a good pre-approved offer. Or maybe ask NatWest which is my main bank for an offer? Not holding my breath though, I never had very good offers from them,
- get a £20k 2 year loan to cover half the Oplo and my partner can cover the other half. At the moment I can get a pre-approved Admiral loan at 6.4%. A few months ago it was 8% so I'm hoping in a couple of months the rate will get even lower. I don't want to get the loan until I pay off PayPal and NewDay as I might not be able to close them before the 0% ends.
My only worry is that the loan will be most of my 'spare' money - even with a top rate of 3-4% the monthly repayment will be close to £900 and I don't have an emegency fund for any other unexpected expenses. So I might taek a loan on a 30-36 months term?
Thanks in advance for your thoughts!
Geo
After reading a few threads here and lots of articles on the MSE webiste I decided to start my own DFW thread/diary.
I have been paying more than minimum on all CCs since spring last year when nurseries closed and then m youngest started school in Sept (no more £1k+pm going on childcare!), but my defnite LBM was in November when I decided to spend no more than £100 weekly. It didn't always work out, we had some unexpected expenses and no emergency fund, but I was able to pay for them without using any credit. I just paid very little on CCs some months.
These are the credit cards balances now vs Nov and I also had a £700 overdraft which has been covered. I am happy I started logging, it is encouranging to see progress.
We also have a mortgage and a car on HP which is accounted for in the bills budget.
The biggest debt which we have to get rid of is a secured Oplo - £43k for 10 years, 8% in the first 5 years, £548 monthly. The plan is to pay it off in less than 2 years as in 2023 our mortgage fixed rate term ends. Our LTV (taking into account the main mortgage only) will be just under 80% which should mean a better rate.
We used the Oplo to cover 2 expensive NatWest loans, one each for my partner and I. This freed up some cash to pay off other cards in the meantime.
I have about £1100 monthly after bills and spending budget, this is if nothing major comes up. This month I am getting a bonus so I will have double the amount, but I don;t expect this to happen again this year.
I don't think we can pay off Oplo without consolidating?
This is my plan for the next few months:
- pay Barclaycard and Natwest this month (payday 28th)
- pay NewDay and Paypal by August when the 0% rate ends
- move Halifax and/or Tesco to a 0% BT when I get a good pre-approved offer. Or maybe ask NatWest which is my main bank for an offer? Not holding my breath though, I never had very good offers from them,
- get a £20k 2 year loan to cover half the Oplo and my partner can cover the other half. At the moment I can get a pre-approved Admiral loan at 6.4%. A few months ago it was 8% so I'm hoping in a couple of months the rate will get even lower. I don't want to get the loan until I pay off PayPal and NewDay as I might not be able to close them before the 0% ends.
My only worry is that the loan will be most of my 'spare' money - even with a top rate of 3-4% the monthly repayment will be close to £900 and I don't have an emegency fund for any other unexpected expenses. So I might taek a loan on a 30-36 months term?
Thanks in advance for your thoughts!
Geo
1
Comments
-
My own inclination would be you have to get out of this consolidating mindset as it's bringing you a lot of grief.
Personally I would throw everything at that secured loan. Yes the rate may be lower than the CCs but while it's there you're at risk of losing your home.3 -
I know what you mean but I really think this time is different

I had a Fluid card I used for a 0% BT that I paid on time to avoid any interest and then closed it. I am going to close the Barclaycard next month and if NatWest doesn't give me a 0% BT I will close that one as well. If I can transfer I will close the Halifax.
In the end I want to keep the Tesco card with the higher limit only, use it for shopping in Tesco for extra points and pay the full balance each month. The other Tesco is on 0% until August 22 but it will get cleared by then with a £25 minimum payment.
I really want to close the secured loan asap and I'd rather pay for an unsecured one. Doesn't it make sense to get one if I put the full value of the new loan into the secured one? The rate will be lower as well.
I had a thought about building an emergency fund. For a few months I can split the £1100 (minus minimum payments) into savings and secured loan overpayments. Once I have 3 months covered I can look into getting the new loan.0 -
Good luck in your journey, keep posting it helps in staying focused.
I highly recommend the emergency fund, makes me feel a lot less on edge whilst throwing money at the debts. Just in case there is a little problem, that needs money. I also have a £100 slush fund for backups. I am fiercely protective of both of these now and will do virtually anything to keep them intact. I have b=never done this during my debt free battles before, it really helps me knowing there is money there if I really do need it
That loan is a but hair raising for you - just wondering why you haven't included it in your spreadsheet?Signiture dated 23/09/2025
3-month emergency fund (Cash ISA and PBonds): £5,382/ + £1,500 = £6,882 /£7,500 (Target 1)
Stocks and shares ISA: £2,232.94
Additional pension contributions £0 (target £450pcm)
Overpayment on mortgage: 1% at a time (£1,518)
Big Renno...and appliances. Front of the house, fridge freezer, dishwasher and washing machine)1 -
Thanks @DrCarrie! I will keep posting, it feels really good to see progress and get encouragement. And finally it looks like there is a DF future for us.
We got into debt after buying our house. We stupidly bought furniture on CCs, then we had our second baby and maternity pay didn't cover for all the bills I used to pay. Just as I got back to work my partner didn't work for a few months and most of the mortgage was paid using CCs. He then got a job that didn't pay enough to cover all his outgoings but it was still a better option than what we were doing. A year after in summer of 2019 he started a new job which allowed him to start paying off. It was very slow at the beginning but it goot much better in the last year or so since we started paying much less (0 now) for childcare.
I have decided to start the emergency fund next month with £400 since I get a bonus. I also have regular savings account for the kids which I can acces this/next month and I most certainly will and add the money to the EF. It's not a lot as I only pay £25 monthly into each of the 2 accounts but it will get the EF close to £1k. I will close the accounts after that.
I have just opened a new current account with First Direct to use as a spending account starting next month. I will open a savings account with them to build the EF there and will set up a spare change transfer into it too. When I get the free £100 for switching to them that will go in the EF as well.
Last nigth I couldn't sleep of excitement and had another idea to make some money. I sew and knit as a hobby and over the last 7-8 years I have accumulated a ridiculous amount of fabric and yarn. I'm off next week and I will spend a day or two going through the stash and try to get a good amount listed for rehoming. I've already planned to clear the toys in the loft next week as well, not sure how many are good to sell but even clearing it out will feel good.
Re loan - it is a joint one and my partner is paying for it at the moment. He is paying much less for it than we were paying for our NatWest loans together and we decided he will pay for now so I can build up my credit rating and get an unsecured loan to cover half. Then that should free up his affordability and he can get a good deal for a loan to cover the rest. I will create a signature today and add that in there.
I had a look in the NatWest app who I have my main current account with and they are offering me a £5000 overdraft. There is no way I will take it but it's a good sign I'm on the right track, a few months ago they were offering £140. One hundred and forty, I didn't miss a digit 0
-
Hi welcome to the forum its really great to see you taking personal responsibility and dealing with the debt a few things stand out to me, You need so do a household budget/soa and you need to include all of the debt including the loans and the Hp car as its still debt just like cc's and loans are as you are paying for it every monthThe next thing is you need to work on this as a houshold and have one sets of accounts it seems you are paying for half of things and your partner is paying for the others, it can be very difficult to see the progress being made when money is all over the place, complete a soa including all of the debt and expenses as a complete household only then you will have a true picture of the balance sheeti know it can a little disheartening when you see the full pictures rather in small chunks but its important and only then you can see the complete picture and come up with a plan of attak, i would not borrow any more money really shifting debt around is not the answer the only way it goes away is to pay it off and if it means paying interest in the process then so be it. Being sill tax i call it and i have paid plenty of it trust me i have been there and done it all. it does not work the only real way it goes away is paying it off £1 at a time.look at it as a journey i used to say to my self it didnt happen overnight and its not going to go away overnight but little by little we will get there but one thing is for sure we never want to be here againhope that helps“People are caught up in an egotistic artificial rat race to display a false image to society. We want the biggest house, fanciest car, and we don't mind paying the sky high mortgage to put up that show. We sacrifice our biggest assets our health and time, We feel happy when we see people look up to us and see how successful we are”
Rat Race0 -
Hi @ratrace and thanks for your advice!
We both knot what the other one owes and discuss progress at least monthly but for some reason we kept it separate, I think it was what we've always done and didn't think about it? But I can see your point and it makes absolute sense. It makes so much sense I don't know why we never thought of it.
Why work to cover my 20% or under CCs when we could focus on his, some of which have a 30% rate? He also has an overdraft which makes it difficult to plan, at least for me, I never had one and don't fully understand how it works but I know that the rate is ridiculous and I can never tell what is available. So we had a little chat today and decided to cover and close the overdraft as soon as possible, it will probably take a few months. Then we can set up a household budget trying to clear as much of his CCs while also overpaying that secured debt. I think in the end we might still need to cover some of it with an unsecured loan, I don't want it to stand in the way of a better mortgage rate when we come to the end of our current fixed rate in 2 years from now.
2







Confirm your email address to Create Threads and Reply

Categories
- All Categories
- 355.7K Banking & Borrowing
- 254.9K Reduce Debt & Boost Income
- 456.1K Spending & Discounts
- 248.3K Work, Benefits & Business
- 605.8K Mortgages, Homes & Bills
- 179K Life & Family
- 263.6K Travel & Transport
- 1.5M Hobbies & Leisure
- 16.2K Discuss & Feedback
- 37.7K Read-Only Boards